


Critical minerals just moved from background story to front page, as Fluor Corp and a US-led consortium vie for Kenya’s Mrima Hill deposit while Chinese bidders step aside. That kind of shift can change how investors view potential future cash flows and where they focus their attention. If you care about where capital could cluster next, keep reading. The article breaks down 3 stocks exposed to this news and what this could mean for each one.
The three stocks covered below are only a sample of what this theme touches, as the full screen surfaced 7 more US-listed and Kenyan-linked developers with equally compelling critical minerals narratives that are not unpacked in the article. To go straight to the source, use the US-listed critical minerals and rare earths developers screener to identify, compare, and analyze the highest conviction rare earths and critical minerals ideas for your watchlist.
Evolution Metals & Technologies (EMAT)
Overview: Evolution Metals & Technologies produces rare earth magnets, battery metals and recycling services that tie directly into US critical minerals supply chains.
Market Cap: US$1.0 billion
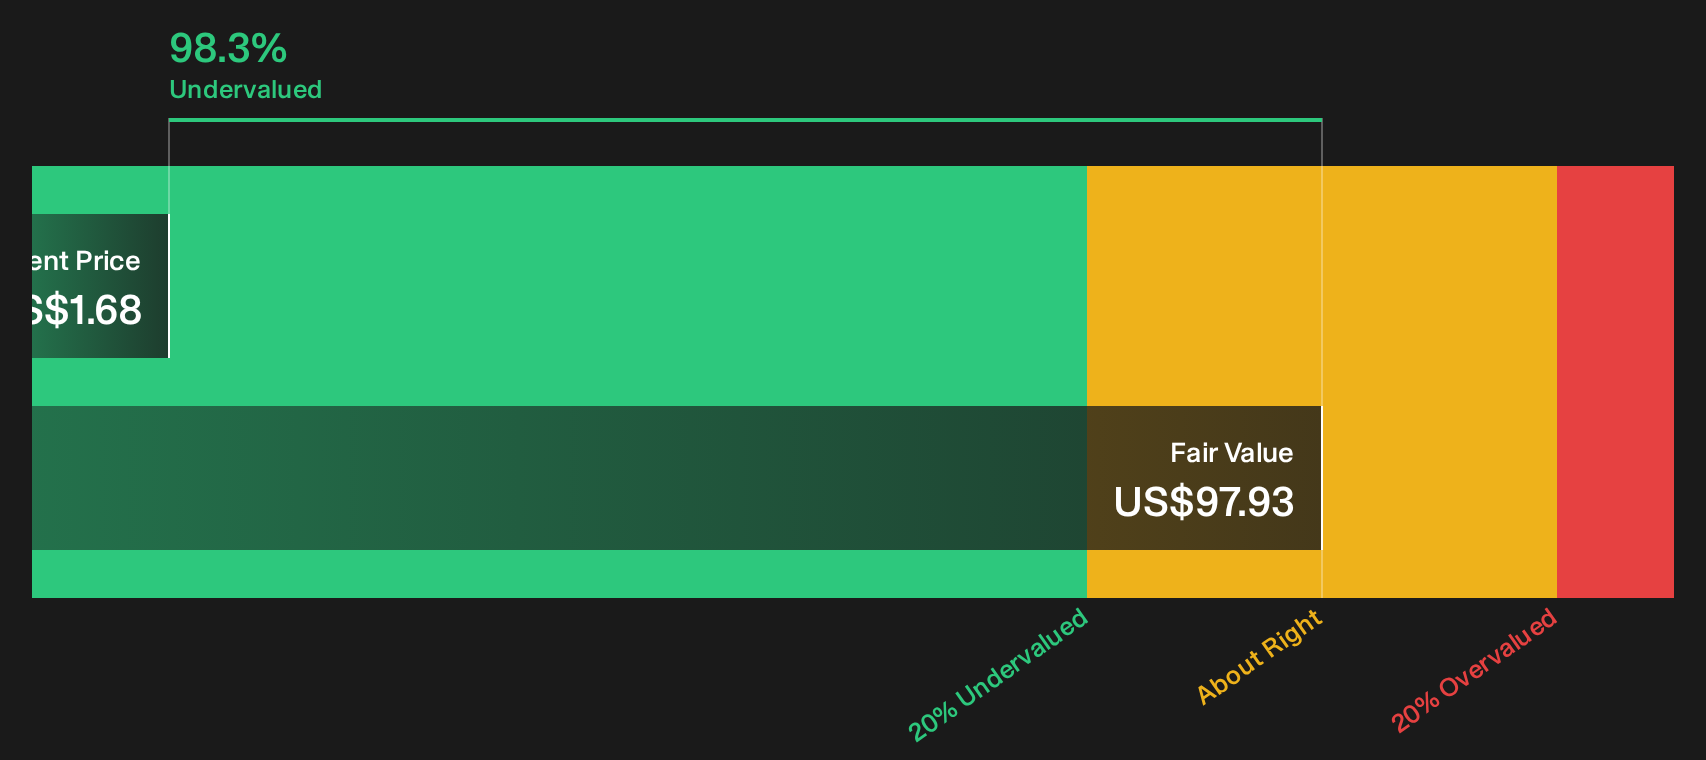
Evolution Metals & Technologies provides pure-play exposure to non-China rare earth magnet and battery metals development that aligns with current US policy initiatives. The company is pursuing expansion of large magnet facilities and energy partnerships, while operating from a relatively small current revenue base and facing ongoing funding requirements. The outcome for investors depends on how one underlying pressure ultimately affects future pricing power and the returns generated on new capacity.
That pressure point is exactly what the DCF valuation analysis for Evolution Metals & Technologies unpacks, helping you see how funding needs and pricing power could reshape the story from here.
ATI (ATI)
Overview: ATI Inc. produces high performance titanium, nickel, cobalt and specialty metal alloys and precision components for aerospace, defense, medical and industrial customers worldwide, linking it indirectly to critical mineral demand.
Market Cap: US$23.8b
ATI gives this screener a different angle, since the company turns critical mineral rich alloys into high value parts for jet engines, defense platforms and specialty energy projects rather than mining the ore itself.
Discrete investments in premium quality titanium, nickel remelt and manufacturing footprints, including the EB2 furnace, a planned 15% to 20% increase in nickel capacity that is tied to about US$350m of potential annual revenue by 2028, and the new Chihuahua machining, inspection and forging operations, are set to add capacity that can improve volume, mix and EBITDA margins as assets qualify and ramp.
For investors tracking ATI, the real swing factor is how much pricing power sticks as this fresh capacity meets tight, high-spec demand.
That pricing puzzle is exactly where the full narrative for ATI comes in, explaining how ATI’s capacity build, contracts and risks could be decoupling from surface-level headlines.

REalloys (ALOY)
Overview: REalloys is a North American rare earth metals and permanent magnet producer, providing direct exposure to policy driven clean energy and advanced manufacturing demand.
Operations: REalloys reports approximately US$2 million of revenue from a single Metals & Mining, Miscellaneous segment tied to rare earth related activities.
Market Cap: US$505 million
REalloys aligns with the screener theme as a US listed rare earth and magnet specialist with around US$2 million of early revenue. Its mine to magnet model has attracted attention through reported top line expansion and index inclusion, while future returns depend on how one unresolved cost and funding pressure affects eventual cash generation.
Those funding and cost pressures are exactly why the REalloys financial health report could be critical, as it may reveal how REalloys’ balance sheet might handle a serious scale up.

Seeking Alternatives Before Everyone Else?
Fresh themes can gain momentum quickly, and the most interesting watchlist candidates rarely stay under the radar for long. Consider your options before potential entry points change.
- Spot sturdier balance sheets before money chases safety by using the list of solid balance sheet and fundamentals (23 results) to find businesses that still price in caution.
- Track gold producers when fear is quiet and use the 35 elite gold producer stocks to identify miners that may benefit from changes in sentiment.
- Follow the buildout of smarter grids and use the 42 power grid technology and infrastructure stocks to focus on companies connected to long term electrification spending.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com