


Alma Media Oyj walked into its Q3 2026 earnings release with a stock that had quietly inched higher over the past month, closing today at €13.7. The headline was far louder than the share price. Revenue reached €84.2m while basic earnings per share hit €0.25, supported by an all time high operating margin around 31% in the quarter.
The price reaction looks restrained compared with that profitability jump. Traders focused on modest top line growth in a tough media and classifieds market. Yet the real story sits in a powerful margin step up that reframes what this business can earn on each euro of sales.
Love Alma Media Oyj’s 31% operating margin but concerned that revenue momentum looks muted in a tough media and classifieds market? Check out our 201 high quality undervalued stocks for ideas that pair strong profitability with balance sheets built to handle slow top line conditions.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): €84.2m vs. €79.3m (+6.2%).
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): €20.5m vs. €16.6m (+23.5%).
- Basic EPS (Earnings Per Share, Q3 2026 vs Q3 2025): €0.25 vs. €0.201804 (+23.9%).
- Operating Margin (Q3 2026): approximately 31% of revenue, described as an all-time high for Alma Media Oyj and aligned with the long-term adjusted EBIT (Earnings Before Interest and Taxes) margin target of about 30%.
Alma Media hit record Q3 margins after years of platform spend. Ask Charlie what unlocked Alma Media’s record 40% marketplace margins.
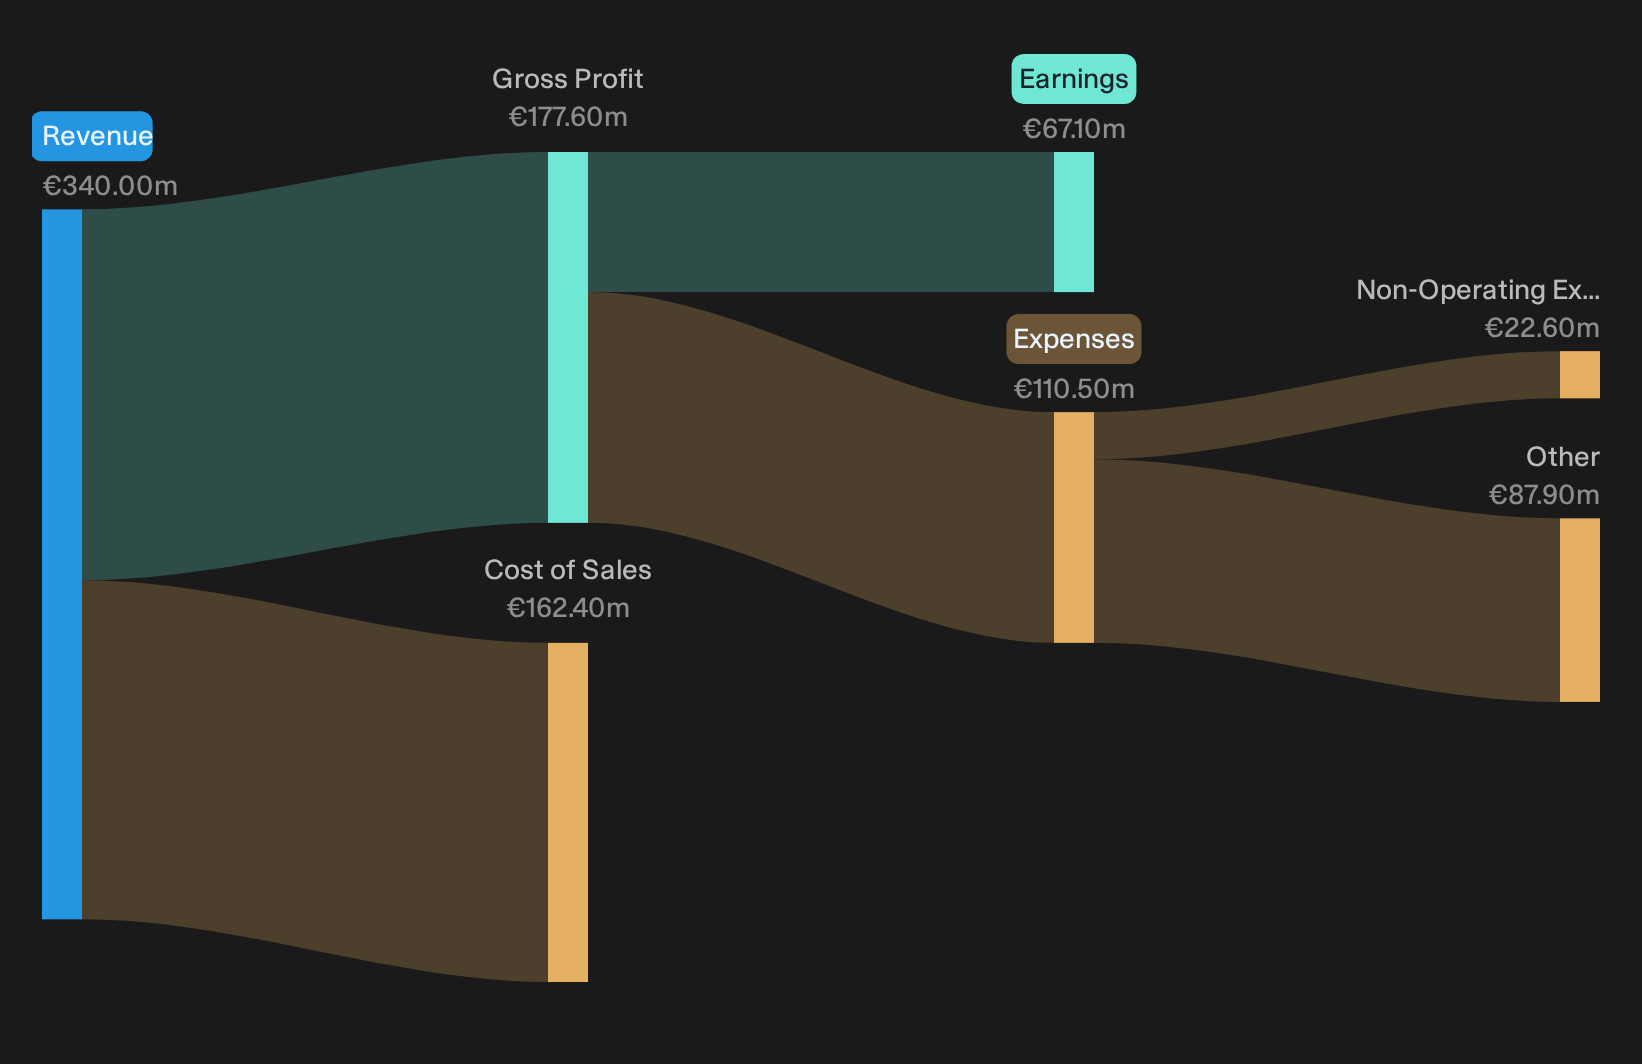
Alma Media bullish thesis meets margin reality
The upbeat view assumes Alma Media can turn a largely digital base into richer products and higher profitability.
"Alma Media Oyj's ongoing integration of AI and automation across digital classifieds, services and news is moving into a group-wide phase that focuses on data driven customer platforms, which can expand digital revenue and support higher net margins as more of the 86 to 87% digital sales base is monetised through higher value products."
Q3 shows progress. Digital reached about 88% of turnover, operating margin hit roughly 31% and Marketplaces delivered close to 40% profitability. Management links this to earlier platform work and data products, so the quarter is a concrete milestone for that ambition.
Bear case on end markets not fully resolved
The sceptical angle is that weak local markets and soft advertising eventually overpower efficiency gains.
"If advertising demand remains uncertain and Alma Media is only able to keep group revenue at roughly last year's level while focusing on profit improvement, then operating leverage could work in reverse during any downturn in ad spending."
Current figures argue partly against that fear. Revenue in Q3 grew about 6% with organic growth of 5.5% in local currencies and all segments contributed. At the same time, management still highlights very weak Finnish housing and mobility activity, so cyclic pressure has not disappeared, it is just being offset for now.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt Quiet Mispricings Like This
Alma Media Oyj just showed how margins can reset even when investors focus on revenue headlines. The real opportunity sits in finding stocks that could be undervalued before sentiment changes.
- Company 1 - 21% below our estimate - builds long term healthcare outsourcing deals as clients move claims and care management onto AI enabled managed services.
- Company 2 - 47% below our estimate - supplies the high voltage cables grid operators need as they replace aging lines to connect data heavy and renewable projects.
- Company 3 - 16% below our estimate - channels surplus capital and new branches into lending to smaller firms as digital banking tools deepen customer relationships and fee income.
Those are three of them. See every one of the 201 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com