


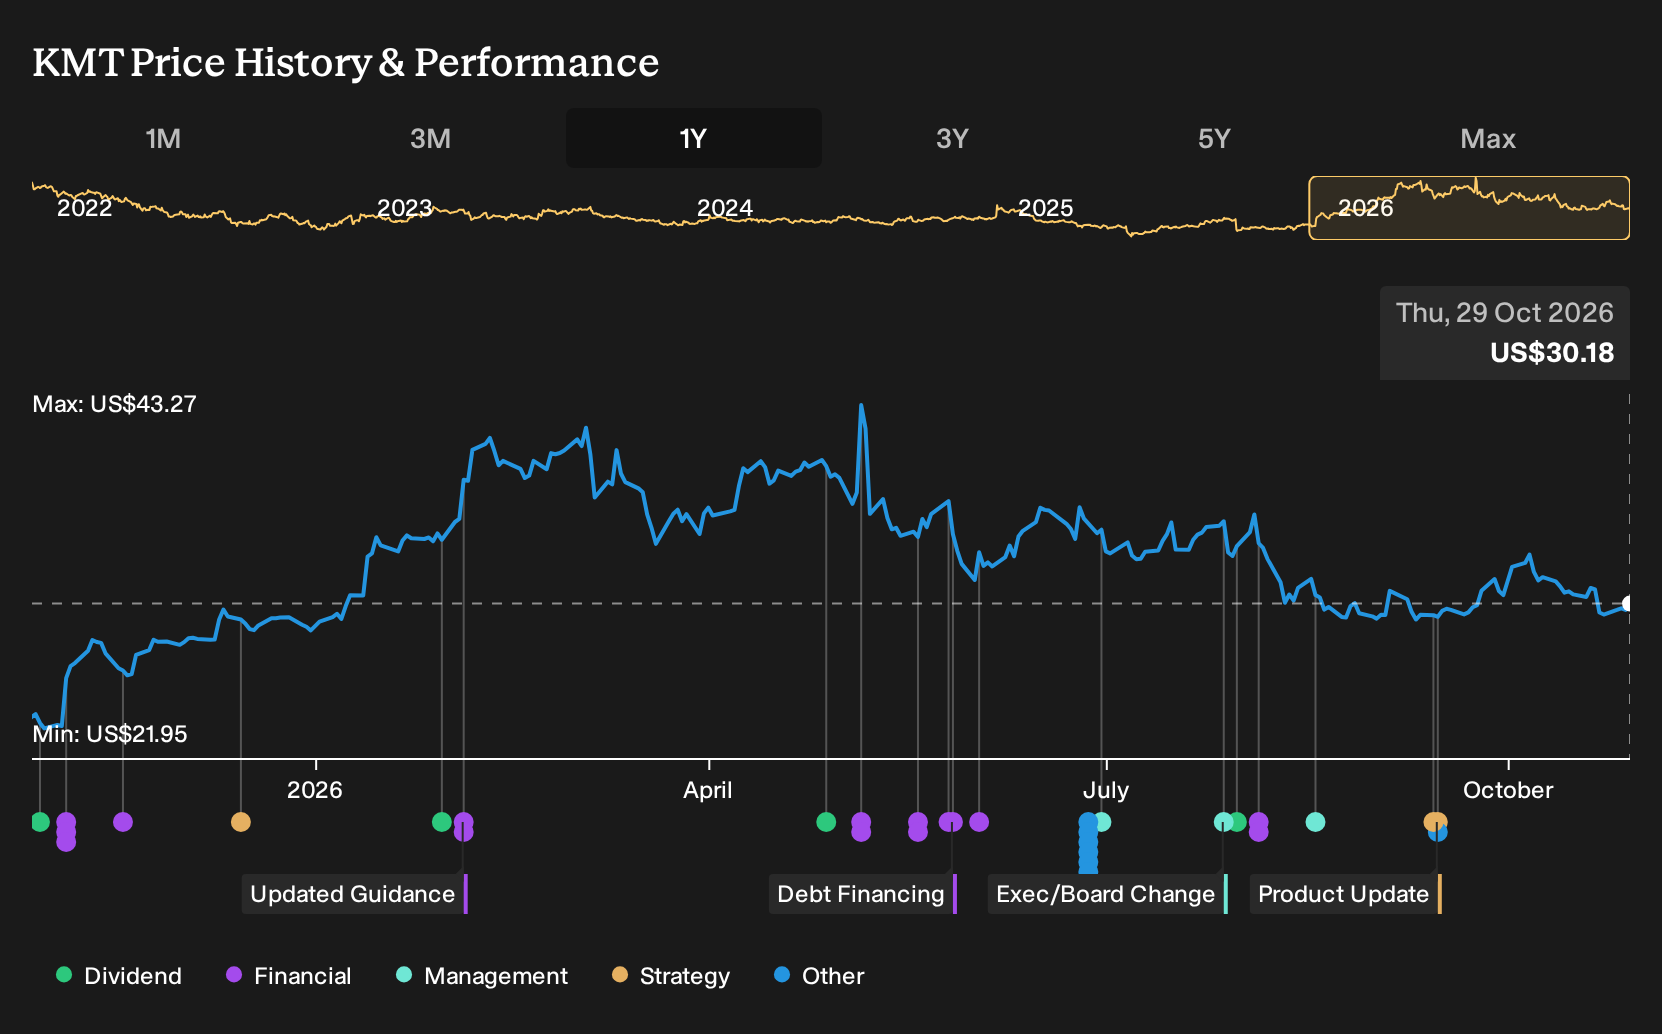
- Kennametal's board declared a quarterly cash dividend of US$0.20 per share, payable on November 23, 2026, to investors on record as of November 9.
- The latest annual meeting recap emphasized 19% organic sales growth, margin expansion, and visible progress toward a US$110 million cost savings target.
- The focus now turns to how Kennametal's margin progress and cost program shape the investment narrative that analysts had already built.
Compare Kennametal's dividend and cost cutting story with other industrials by scanning our curated list of 30 high quality undervalued stocks that pair balance sheet strength with disciplined capital returns.
Kennametal Investment Narrative Recap
To stay invested in Kennametal, you need to be comfortable with an execution story built on cost cuts, restructuring and mix improvement while key end markets remain sensitive to cycles. The big swing factor near term is whether recent margin gains, helped by tungsten pricing and efficiencies, can hold as demand in sectors like energy and transportation moves around.
The most important near term catalyst is the upcoming earnings print because it tests how much of the fiscal 2026 margin profile is repeatable as tungsten timing benefits fade. The main risk is that weaker end market volumes or pricing quickly squeeze those margins and strain free cash flow just as restructuring and capacity actions continue.
The fresh US$0.20 quarterly dividend declaration matters because it sits directly on top of that margin and cash flow story. Kennametal is already flagged for a dividend that is not well covered by free cash flows, so every payout keeps the spotlight on whether restructuring savings and operating cash generation can comfortably fund both distribution and reinvestment.
If earnings on November 4 come in soft while tungsten benefits ease, the dividend could intensify questions around capital allocation, especially with ongoing cost programs and portfolio work running through the system. If operating performance holds up, the same dividend may simply reinforce the existing capital returns pattern without materially changing the near term catalyst or risk profile.
Kennametal's narrative projects US$3.6b revenue and US$273.0 million earnings by 2029. That implies 15.0% yearly revenue growth and an earnings decrease of US$69.4 million from US$342.4 million today.
Discover why Kennametal's fair value indicates a 7% potential upside to its current price, which some investors believe could be realized sooner than expected.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Kennametal’s tungsten driven cash generation story rather than the risk of weaker end markets. Before this dividend decision, the bullish camp was modeling around US$3.8b of revenue and US$254.8 million of earnings by 2029, so the latest payout could prompt them to rethink how secure that cash flow path looks.
Explore 2 other Kennametal fair value estimates, including one that suggests potential upside of up to 33% from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kennametal research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Kennametal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kennametal's overall financial health at a glance.
Looking For More Kennametal-Like Investment Ideas?
If the Kennametal story has you thinking about portfolio fit, use this moment to widen your search and line up a few alternatives that match your risk profile and income needs.
- For investors who want potential upside backed by fundamental strength, scan a curated pool of 18 high quality undiscovered gems that already show solid quality markers.
- If resilience matters more than excitement for you, focus on capital preservation by reviewing a group of 30 resilient stocks with low risk scores that screen well on stability metrics.
- For those who care most about financial strength, stress test your dividend and value ideas against a list of solid balance sheet and fundamentals (23 results) and see which businesses hold up best.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com