


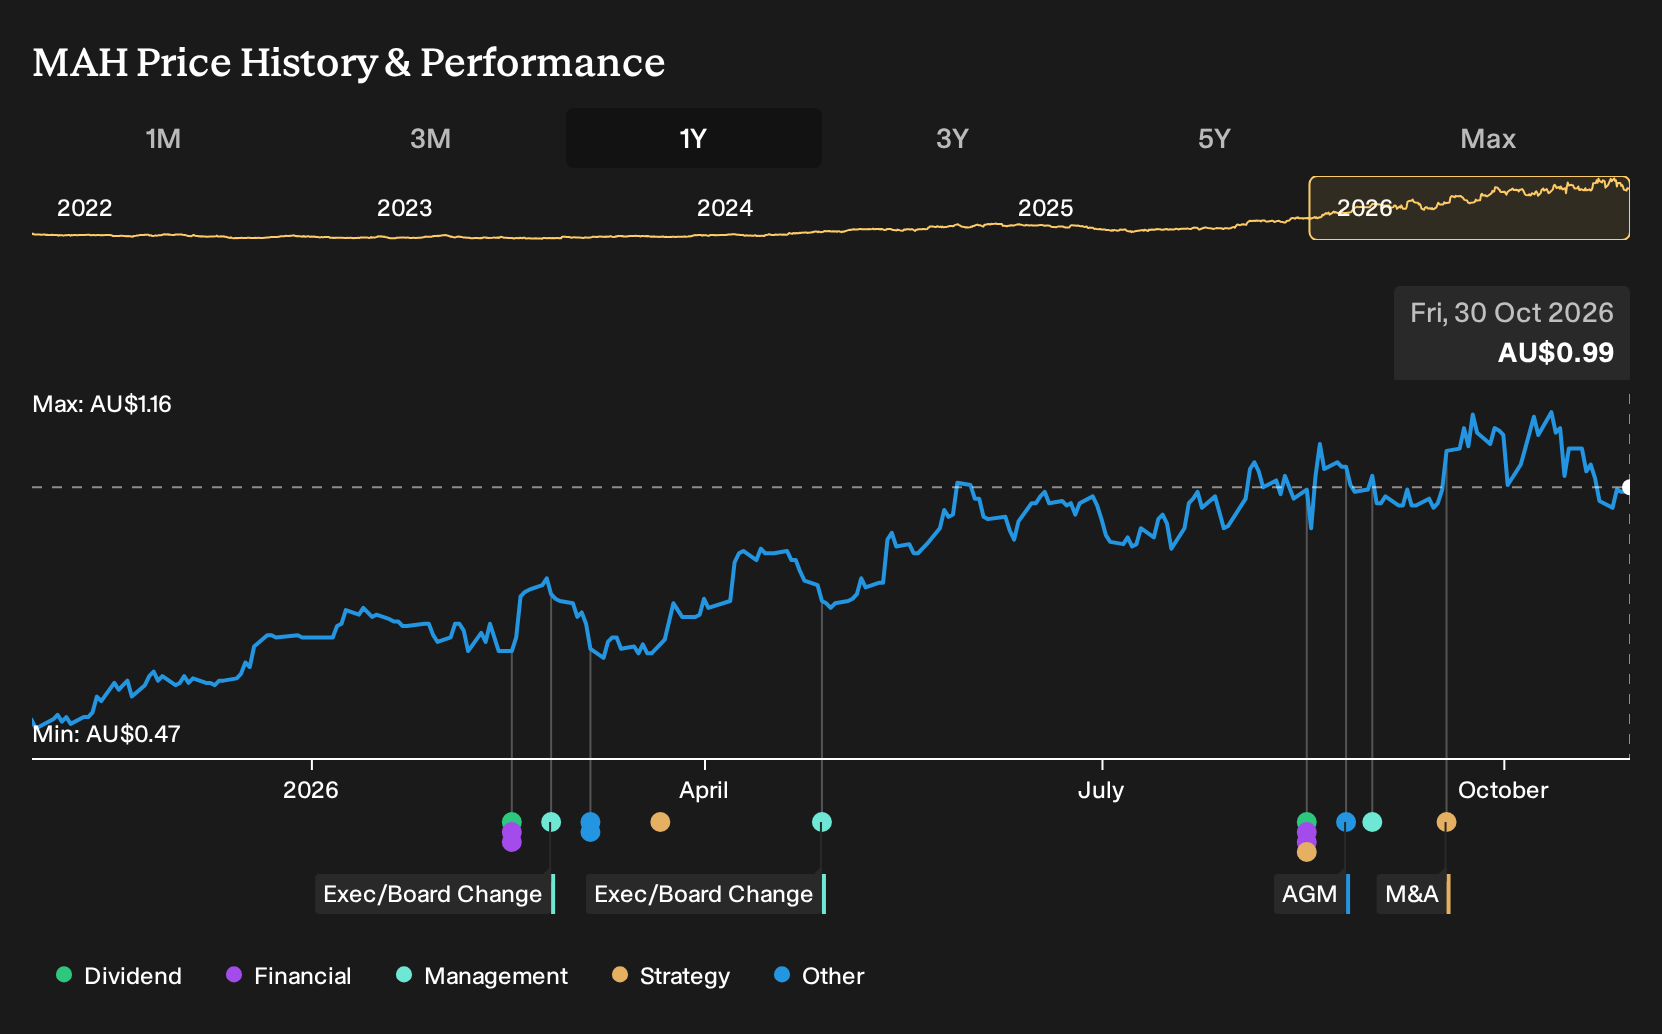
Investors who held Macmahon over the past year are up 117.6%, including dividends. If you had bought on 30 October 2025, with analysts split between a bullish A$0.49 view and a more cautious A$0.44, how would you have weighed that call against the civil push from Decmil, the exposure to battery metals growth, and the risk that concentrated contracts or ESG pressure might blunt those forecasts?
Macmahon has already moved. Pinpoint other ways to investigate the theme among 41 power grid technology and infrastructure stocks.
The Argument Macmahon Investors Faced At The Time
The shares cost A$0.47 at the start of the period, and you were effectively choosing between two tidy but very different stories about where Macmahon could go next.
On the upbeat side, the optimistic Narrative pointed to a Fair Value of A$0.49. That price was implied by assumptions that Decmil would integrate smoothly and that Southeast Asian mining and automation would support revenue growth of 6.5%, with profit margins reaching 4.3% and a future P/E of 10.4x.
The more cautious view anchored on a Fair Value of A$0.44 and treated contract concentration and lower margin civil work as real threats, even while still baking in 4.9% revenue growth, a 4.4% margin assumption, and a future P/E of 9.5x.
What The Macmahon Evidence Put To The Test
Macmahon’s acquisition of Aspect Engineering Solutions supported the bullish argument that broader services could underpin higher earnings quality. Reported numbers pointed in the same direction. Revenue increased from A$1,248.8m in H2 2025 to A$1,312.2m in H2 2026, while net income rose and margin edged up from 3.5% to 4.0%. The period broadly supported the optimistic case, but only over one reporting window.
The key assumption was that integration and contract wins would be reflected in both the top line and the margin. When you assess a different contractor, track whether revenue, net profit and the reported net margin ratio all move in line with the growth story you are being presented.
What Macmahon’s Run Leaves You Paying For Now
Macmahon trades at A$0.99 after a 117.6% gain over the past year. The selected Narrative judges its Fair Value to be above that price and ties the case to how underground, civil and Indonesian work change the mix rather than to simple volume growth.
A buyer today would need to weigh whether the order book, project pipeline and lower capital intensity shifts can support stronger returns on capital and free cash generation than the market credits.
"The main condition for this to work is that Macmahon maintains disciplined capital management so that the shift toward lower capex segments and the A$5.9 billion order book translate into consistently strong returns on average capital employed and solid free cash generation."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
A Step Beyond Macmahon
Macmahon gives you exposure to rock, dirt and diesel. One step away, another miner is working on crop nutrients instead.
This other business is focused on potash, a fertiliser ingredient crops cannot replace. Rather than sinking deep shafts, it adapts horizontal drilling techniques from oilfields.
The method aims to reach known deposits with less surface disturbance and reusable brine loops. That can matter where permits, water use and tailings are flashpoints.
If this approach scales, your mining theme stretches from haul trucks to food security. The unresolved issue is how that different resource risk fits your portfolio.
That argument has a Narrative and a number behind it. → See the company one Narrative values 61% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com