


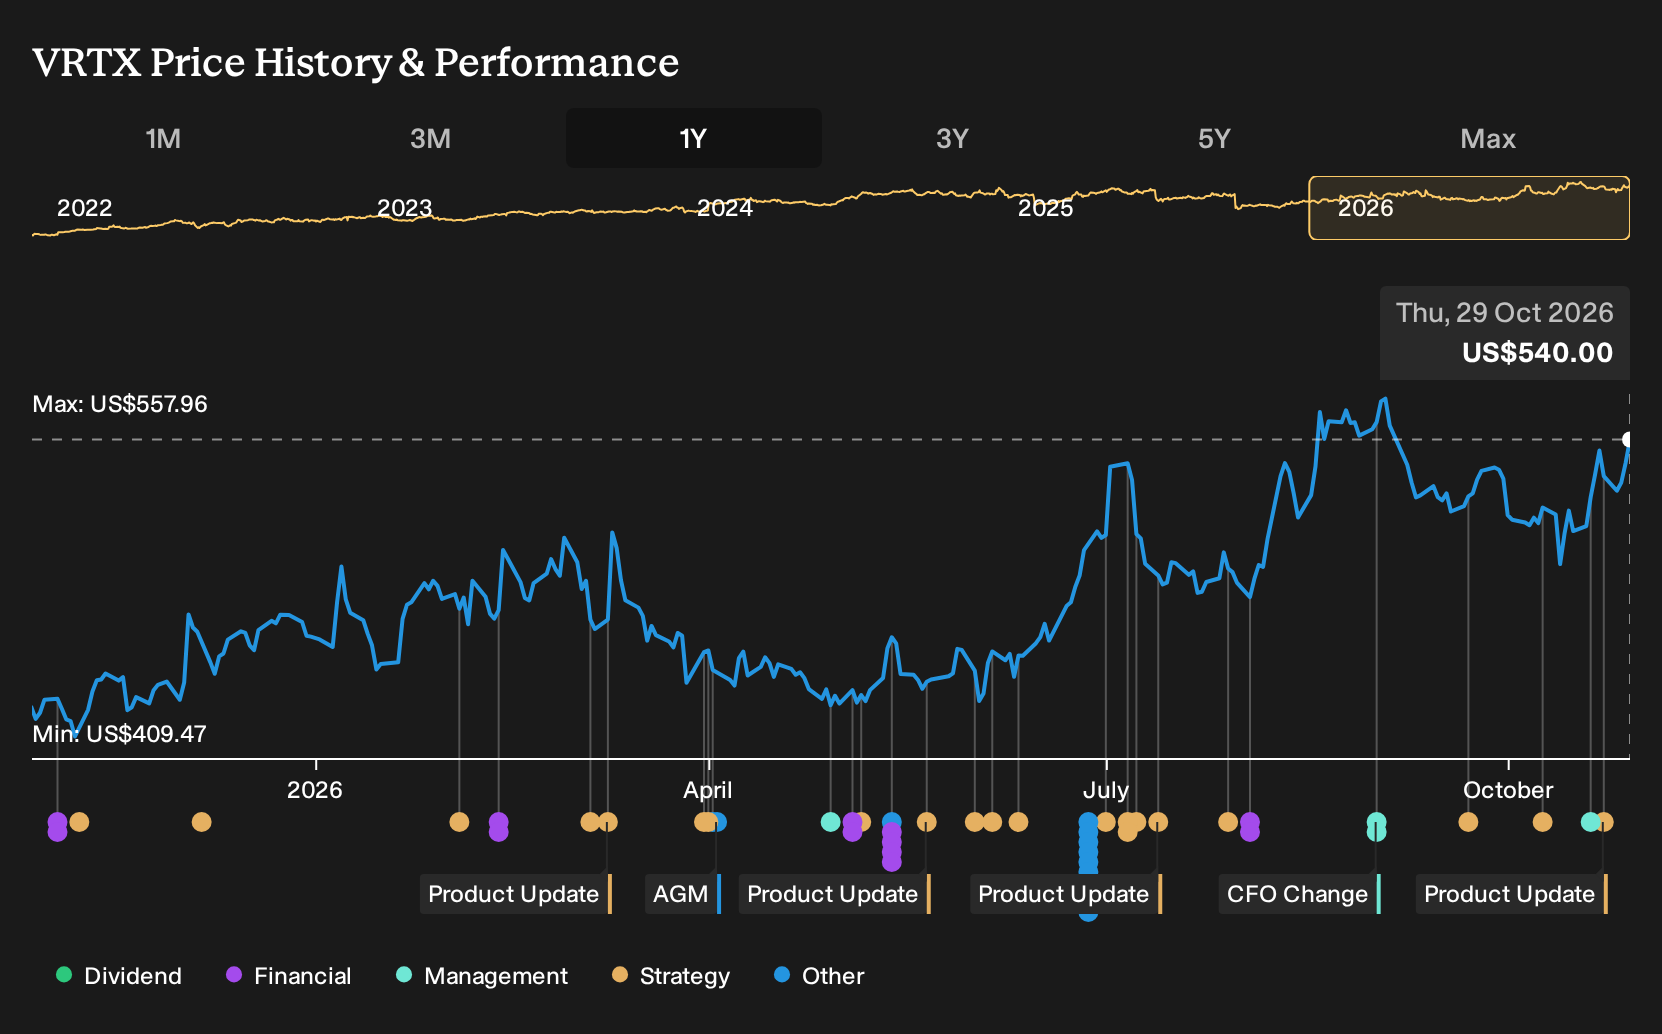
If you only skimmed the headlines on Vertex Pharmaceuticals this year, you probably saw a gene therapy leader juggling regulatory wins, rising R&D spend, and a US$10b acquisition that sparked fresh debate about risk. For Vertex Pharmaceuticals shareholders, the return over the past year was 26.9%, including dividends. If you were weighing up a purchase back in October 2025, how should those conflicting signals now reshape your view of what really mattered?
Vertex Pharmaceuticals has already moved. Pinpoint other ways to investigate the theme among 36 healthcare AI stocks.
The Two Vertex Pharmaceuticals Stories Investors Had To Weigh
The shares cost US$417 at the start of the period, which left you choosing between two sharply different stories about Vertex Pharmaceuticals.
On the optimistic side, the September 2025 bull case put Fair Value at US$480. That price only made sense if assumptions like 9.4% annual revenue growth and a future P/E of 26.5x played out alongside a broader genomics pipeline.
The May 2025 bear view pointed to a Fair Value of US$330, hinging on concerns that tighter drug pricing rules and high gene therapy costs could restrict access and compress margins despite heavy R&D spend.
What The Results Changed For The Vertex Pharmaceuticals Debate
The clearest development came from Vertex Pharmaceuticals securing US FDA approval to expand CASGEVY to children as young as two and pushing povetacicept toward an FDA decision, which backed the optimistic case about pipeline breadth beyond cystic fibrosis. At the same time, net margin slipped from 34.8% to 33.0% between Q2 2025 and Q2 2026, which aligned with the cautious worries about pressure on profitability. Taken together, the evidence cut both ways.
The lesson is simple. When a story rests on high future margins as much as on new drugs, track the reported net margin alongside pipeline headlines and test whether each new launch supports both parts of that promise.
What Vertex Pharmaceuticals' Price Already Assumes Today
Today Vertex Pharmaceuticals trades at US$540 after a 26.9% gain over the past year. The selected Narrative puts Fair Value below that level, arguing the current tag already bakes in successful execution on several fronts.
The key hinge is that buyers now effectively assume JOURNAVX support costs ease, the Crinetics deal pays off, and broader launch spending still leads to strong margin realization. How does the risk that patient support and a wider commercial footprint mute reported earnings affect your confidence in that assumption?
"The main thing that has to go right is that Vertex Pharmaceuticals converts its expanded multi pillar portfolio, including CASGEVY, renal programs, acute pain, and endocrinology assets from Crinetics, into durable high margin franchises that justify the current premium attached to the stock. The numbers on guidance, acquisitions, and pipeline scale imply a share price that already bakes in successful diversification beyond cystic fibrosis and strong long term execution, leaving limited room for disappointment."
The price and this Narrative do not agree. → Uncover what this Narrative says Vertex Pharmaceuticals is actually worth
Looking Beyond Vertex Pharmaceuticals
You have watched Vertex Pharmaceuticals lean hard into specialized medicines. That focus raises a practical question about how broad your healthcare exposure should be.
Vertex concentrates on genetic and specialty treatments. Another large healthcare group is also pushing specialty drugs, paired with medical devices for surgery, joint repair and vision care.
Both are investing heavily in earlier stage science. The other company is also reshaping its mix by spinning out slower divisions and absorbing legal and deal related costs.
If you are testing your Vertex view, that comparison matters. It shows how one diversified platform is handling pricing pressure, exclusivity loss and margin resets differently.
One Narrative has already put a figure on it. → Uncover the company trading 14% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com