


- ALK-Abelló reported positive topline phase 3 results for its ACARIZAX house dust mite tablet in Chinese patients with allergic rhinitis or rhinoconjunctivitis, with or without asthma. The trial met its primary endpoint on total combined rhinitis score and showed a safety profile aligned with previous global studies.
- The bridging trial substantially exceeded its predefined success criterion in China, with ACARIZAX patients 4.3 times more likely to report symptom improvement than placebo. This outcome could help support local regulatory discussions and extend ALK-Abelló’s tablet-based allergy portfolio into a very large new treatment market.
- We will now look at how ALK-Abelló’s investment narrative could shift as Chinese ACARIZAX data points toward potential regulatory traction.
ALK-Abelló Investment Narrative Recap
To own ALK-Abelló you need to believe the tablet allergy franchise can keep scaling, while high margins, strong earnings quality and disciplined manufacturing investment hold up. The Chinese ACARIZAX data supports that broader tablet story, but on its own it does not fundamentally change the near term picture around growth, pricing pressure or capital needs.
The most important short term swing factor still sits in execution on tablet volume, anaphylaxis products and upcoming indications, with German rebate hikes a clear profit risk from 2027. The new China readout mostly adds another potential engine rather than altering that core risk reward balance today.
The ACARIZAX phase 3 success in China lines up with earlier tablet momentum in Europe and other markets. For you as an investor, it connects directly to ALK-Abelló’s existing catalyst of expanding its addressable population across age groups and geographies while keeping its allergy tablet mix rich and relatively high margin.
That matters because planned manufacturing expansion lifts fixed costs and puts a premium on filling capacity with reliable demand. Positive Chinese data, if turned into approval and uptake, could help support that utilization story over time, partly offset volume or rebate pressure elsewhere and reduce the operational risk of underused tablet capacity.
ALK-Abelló's current analyst narrative points to DKK 9.9b in revenue and DKK 2.1b in earnings by 2029, based on forecast top line expansion of 13.1% a year and an increase of DKK 0.7b in earnings from DKK 1.4b today.
Uncover how ALK-Abelló's fair value indicates a 17% potential upside to its current price. This opportunity could narrow quickly if tablet momentum keeps building.
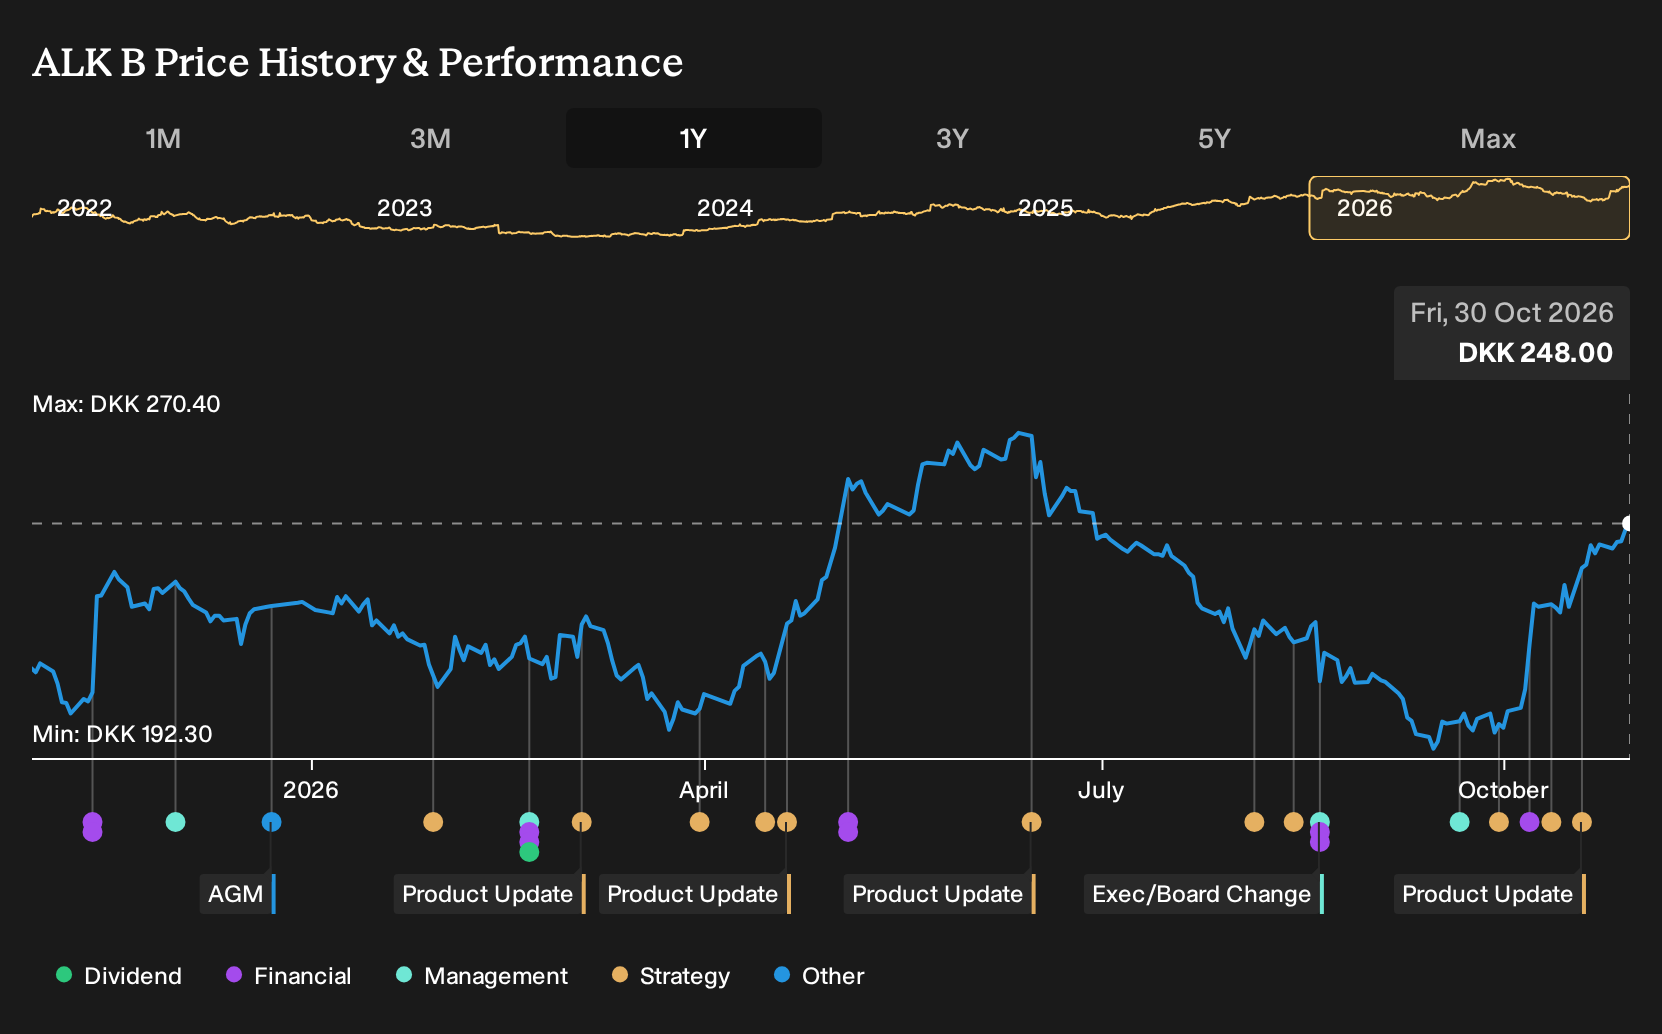
Exploring Other Perspectives
One alternate view on ALK-Abelló focuses on margin risk rather than new tablet demand. The most cautious analysts already expected earnings of about DKK 2.0b on revenue of roughly DKK 10.1b by 2029, with profit margins flat at 19.9%. You can read this China ACARIZAX result and then judge whether that story still fits.
Explore 3 other ALK-Abelló fair value estimates, including one that suggests it could be worth just DKK 287.50.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ALK-Abelló research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for ALK-Abelló. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ALK-Abelló's overall financial health at a glance.
Looking For More Investment Ideas Beyond ALK-Abelló?
Once you have formed a view on ALK-Abelló, it can help to cross check that thesis against other opportunities on your radar. The Simply Wall St Screener lets you scan the market quickly using the same kind of fundamental filters that sit behind this analysis.
- Prefer potential mispricings backed by solid fundamentals and cash generation? Run a check across a curated 201 high quality undervalued stocks that may offer a more appealing risk reward profile than broad market exposure.
- Income first. If reliable payouts matter to you, review a focused 223 dividend fortresses that could help you build a portfolio with yield front and center.
- Comfort comes from resilience. To narrow in on companies with sturdier financial footing, scan a 220 resilient stocks with low risk scores and see which businesses better match your tolerance for downside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com