


Magna International (TSX:MG) just paired a guidance reset with a capital return update. Management trimmed 2026 sales expectations, kept the adjusted EPS midpoint, and unveiled an expanded share repurchase plan alongside its latest dividend declaration.
Magna International shares trade at CA$90.31 after a 1-day share price return of 0.95%, leaving the 90-day share price return down 6.06% but the 1-year total shareholder return at 49.30%, which reflects stronger performance over the past year compared with the more recent period.
Capitalize on Magna International's mix of earnings strength and guidance reset by scanning a curated 4 high quality undervalued stocks that share resilient profitability with potential mispricing.Magna International just reset its sales ambitions while beating on earnings and greenlighting a larger buyback. Is the near 48% intrinsic discount hinting at mispricing, or is the market simply pricing execution risk correctly?
Most Popular Narrative: 1% Undervalued
Magna International's most followed valuation storyline pegs fair value at about CA$91.60, slightly above the CA$90.31 last close. This puts the focus squarely on how margins and cash generation evolve from here.
Magna International is continuing its operational excellence and factory of the future programs, with management pointing to roughly 200 bps of EBIT margin improvement from 2023 through the 2026 outlook and a target of 35 to 40 bps of annual margin expansion, which supports expectations for further progress in net margins and earnings.
See why 74 investors see Magna International as 1% undervalued.
Result: Fair Value of CA$91.60 (ABOUT RIGHT)
Still, the Magna International narrative leans heavily on vehicle production holding up, and on program mix shifts not diluting the margin uplift analysts are assuming.
Find out about the key risks to this Magna International narrative.
Another View: Magna International On Earnings Multiples
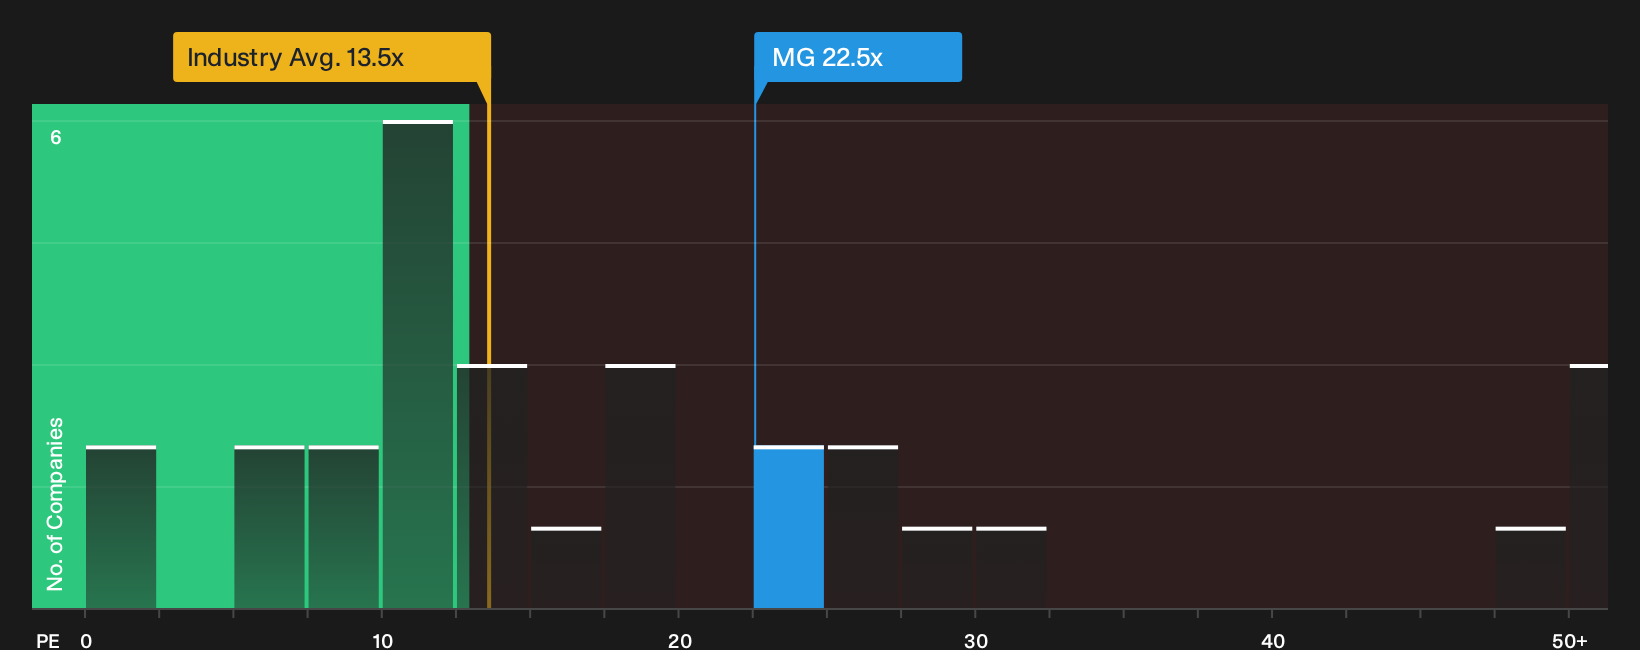
Our DCF work suggests Magna International trades at a wide discount to an estimated fair value of CA$172.50, which points to undervaluation. Yet the market is also paying 22.5x earnings versus an industry on 13.4x and a fair ratio of 11.9x.
That mix of a low DCF price and a rich P/E multiple puts the burden on investors to judge which signal deserves more weight, and to consider how much valuation risk they are comfortable taking.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Magna International's valuation and guidance reset can feel messy, so move quickly to inspect the full risk and reward profile and weigh both sides of the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Magna International?
If Magna International has sharpened your focus on valuation and quality, broaden your watchlist by scanning fresh ideas built from the same disciplined, fundamentals-first lens.
- Spot potential value opportunities early and review a curated 4 high quality undervalued stocks that share strong fundamentals with prices that may not fully reflect their strengths.
- Protect your downside first and run through a 8 resilient stocks with low risk scores that screens for resilient balance sheets and steadier risk profiles.
- Get ahead of the crowd and sift through a focused 8 high quality undiscovered gems that pair solid financials with lower investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com