


Osaka Gas (TSE:9532) just paired an interim dividend increase with higher full year net sales guidance, signaling a richer cash return today and firmer top line expectations anchored in rising city gas selling prices.
Recent catalysts around higher city gas pricing and the upgraded net sales outlook have arrived alongside firm trading in Osaka Gas, with the share price at ¥5,892 and a 90 day share price return of 6.8% contributing to a 1 year total shareholder return of 24.1% and a 5 year total shareholder return of 264.2%, indicating that momentum has been building rather than fading.
Scan how Osaka Gas compares with other potential utility plays and income ideas by reviewing our curated list of 27 dividend fortresses today.
Osaka Gas now pairs a richer dividend and higher sales guidance with a share price that has already delivered strong multi year gains. The key tension is simple: Are you paying too much for that strength today?
Price-to-Earnings of 16x: Is it justified for Osaka Gas?
On valuation, Osaka Gas trades on a P/E of 16x, which puts a premium on the current ¥5,892 share price compared with several benchmarks.
The P/E ratio compares what investors are willing to pay today for each unit of current earnings. For a regulated utility with relatively modest forecast growth and a mature asset base, this measure often reflects how much faith the market has in the stability of profits and the reliability of dividends rather than rapid expansion.
That premium looks demanding when stacked against multiple yardsticks. The stock is described as expensive versus the estimated fair P/E of 11.1x, a level the market could move towards if sentiment cools. It is also flagged as expensive versus the Asian gas utilities industry average P/E of 13.4x and a peer average of 14.6x. This signals investors are currently paying more for Osaka Gas earnings than for comparable utilities.
Explore the SWS fair ratio for Osaka Gas.
Result: Price-to-Earnings of 16x (OVERVALUED)
Still, Osaka Gas faces real pressure points if regulated city gas pricing or overseas energy projects fail to support current earnings power. This could challenge today’s premium P/E.
Find out about the key risks to this Osaka Gas narrative.
Another View on Osaka Gas: Cash Flows Paint a Harsher Picture
The earnings multiple presents Osaka Gas as expensive, yet our DCF model is even stricter. At ¥5,892, the stock trades well above an estimated future cash flow value of ¥2,769.44, which frames the current price as overvalued on this basis.
This gap suggests investors are paying a substantial premium for stability and income. The key consideration is whether that perceived comfort justifies a valuation that the cash flow analysis does not currently support.
Look into how the SWS DCF model arrives at its fair value.
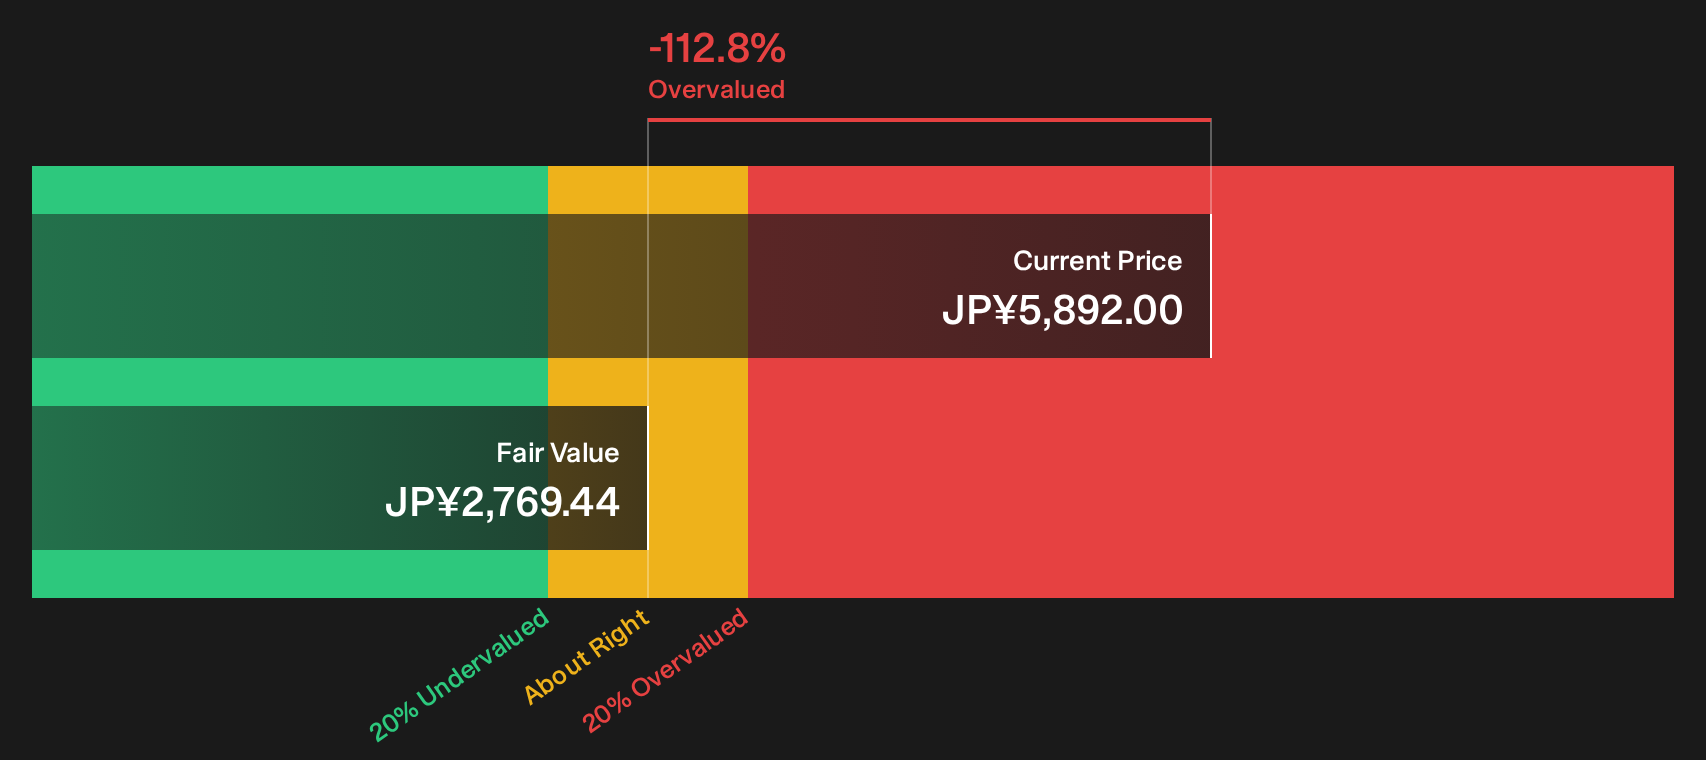
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Osaka Gas for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Osaka Gas may look demanding on traditional valuation checks, yet the full story is rarely one sided, especially when optimism shows up in the reward profile. If you want to move fast and make your own call based on the upside signals as well as the risks, take a moment to review the 2 key rewards.
Looking for more Osaka Gas investment ideas?
If Osaka Gas feels fully priced, broaden your watchlist now. Fresh opportunities often appear where valuation, quality, and resilience quietly line up for patient investors.
- Target resilience first and stress test your portfolio against shocks by scanning a curated 24 resilient stocks with low risk scores that keeps volatility in check.
- Hunt for quality at a discount by reviewing a focused 15 high quality undervalued stocks built around strong fundamentals and appealing price tags.
- Stack potential income and balance sheet strength together by tracking a list of solid balance sheet and fundamentals (22 results) that aims to limit financial surprises.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com