


Why SoftBank’s latest dividend move matters for income-focused investors
SoftBank (TSE:9434) has raised its regular second quarter dividend to ¥4.40 per share and confirmed sizeable interim payouts for its bond type class shares, putting shareholder cash returns in clear focus.
SoftBank’s share price has edged around in recent weeks, with a 1-day share price return of 0.64% and a 7-day move that slipped 1.35%, even as the stock posts an 8.33% year to date share price return and a 1-year total shareholder return of 11.24%.
Against that backdrop, today’s dividend decision and the recently announced role in a NEDO backed quantum computing materials project feed into a longer track record that includes a 3-year total shareholder return of 55.30% and a 5-year total shareholder return of 95.10%. This suggests that momentum in investor rewards has built over time rather than faded.
Scan income oriented telecoms with similar momentum in shareholder payouts by reviewing the hand picked 27 dividend fortresses that is now shaping the wider dividend story beyond SoftBank.
The richer dividend stream puts SoftBank in income investors’ sights right now. The question is whether the current ¥234.2 entry justifies jumping in, or whether patience and a better valuation case wins.
Most Popular Narrative: 14% Undervalued
SoftBank’s most followed narrative points to a fair value of ¥273.13 against the current ¥234.2 share price, which means the story investors are tracking leans toward meaningful upside if the thesis plays out as outlined using a 5.0% discount rate.
Planned rollout of homegrown large language models and commercial GPU as a service targeting Japan based enterprises is now supported by heavier AI data center investment, including SB Neo and domestic AI computing capacity. This ties expected recurring cloud usage fees more tightly to revenue growth and operating margin mix.
See why 7 investors see SoftBank as 14% undervalued.
Result: Fair Value of ¥273.13 (UNDERVALUED)
Still, the SoftBank story hinges on heavy AI and data center spending turning into cash, as well as on earnings and P/E assumptions that may not play out as consensus expects.
Find out about the key risks to this SoftBank narrative.
Another View: What SoftBank’s multiples are saying
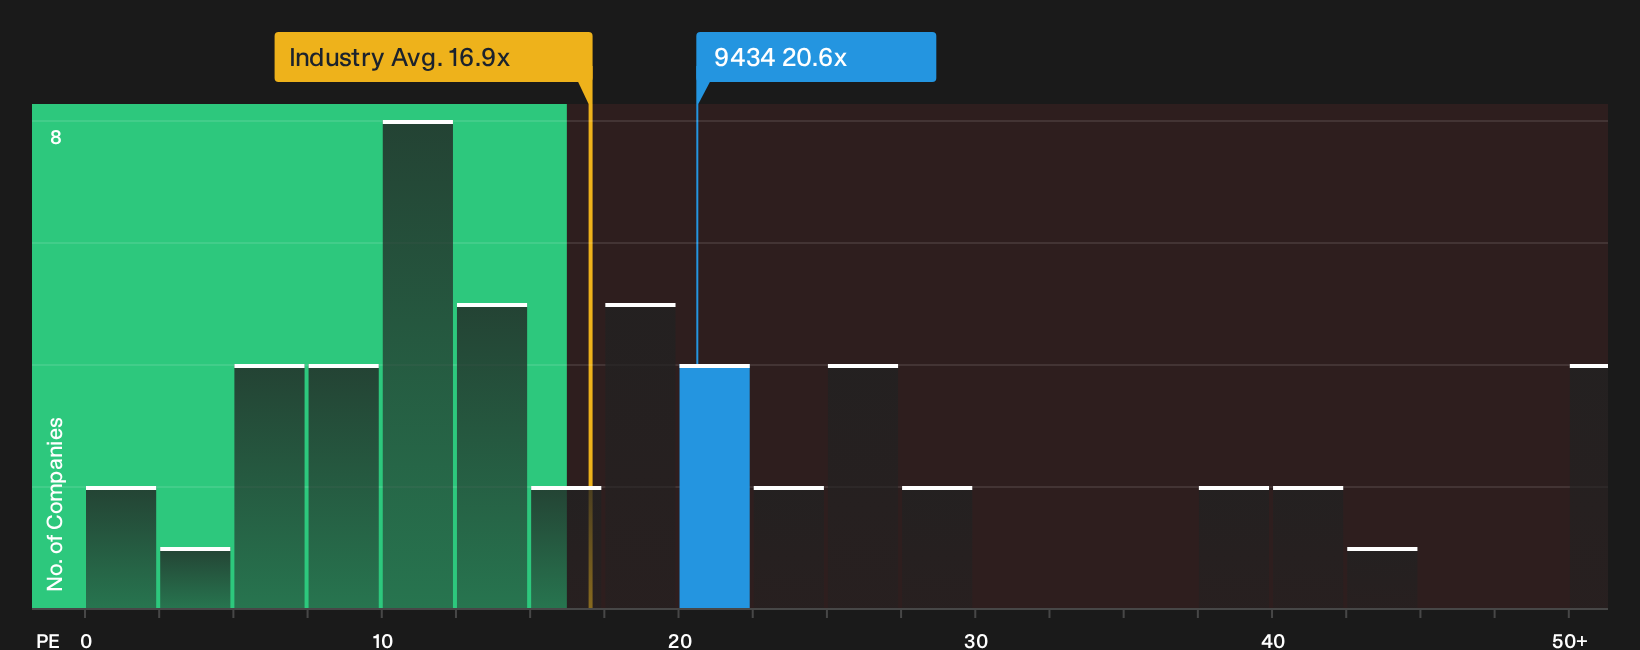
The story looks very different once pricing is framed through earnings. SoftBank trades on a P/E of 20.6x, which is higher than the Asian wireless telecom group on 16.9x and above its own fair ratio of 16.5x. Buyers today are paying up rather than getting a clear discount.
That gap can mean things go well but future returns still feel capped if sentiment cools or earnings slip below expectations. How comfortable are you paying premium pricing for a stock already scoring just 2 out of 6 on value checks?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the optimism around SoftBank matches your own read of the risk and reward mix, especially with both concerns and bright spots on the table? Take a closer look at the underlying data, stress test your assumptions, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond SoftBank?
Do not let your watchlist stop at SoftBank. Fresh ideas today can shape your returns over the next few years if you widen the opportunity set thoughtfully.
- Target resilient balance sheets and steadier fundamentals by reviewing a focused list of solid balance sheet and fundamentals (22 results) that filters for financial strength first, story second.
- Hunt for quality at a discount by scanning the 15 high quality undervalued stocks that narrows in on companies with robust fundamentals priced below estimated worth.
- Lock in cash flow potential by assessing the 27 dividend fortresses that highlights income ideas built around higher yields and durable payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com