


Intuit has seen its share price fall hard over the past year, even as the business pushes deeper into AI driven tax and accounting services. With the stock last closing at US$331.19, the key question for you now is whether that valuation is still supported by the earnings power behind TurboTax, QuickBooks, Credit Karma and Mailchimp.
- The share price has declined 49.7% over the past year. This puts the focus squarely on whether the current earnings multiple leaves enough room for a recovery or further downside.
- Fresh AI features across Credit Karma Tax, Intuit Intelligence and broader partnerships such as Aprio can reshape how investors think about the pace and quality of future profit growth, as well as the level of earnings the market is willing to pay for today.
- Your read on Intuit is one view; the desks covering it have another. See what analysts think Intuit's shares could be worth.
The issue now is whether Intuit's present share price is adequately explained by its earnings, once you line that up against the Fair Ratio benchmark.
Intuit highlights its AI-driven tax and accounting capabilities, which investors can compare with other companies pursuing a similar theme through 38 profitable AI stocks that aren't just burning cash.
Does Intuit Look Undervalued on Earnings?
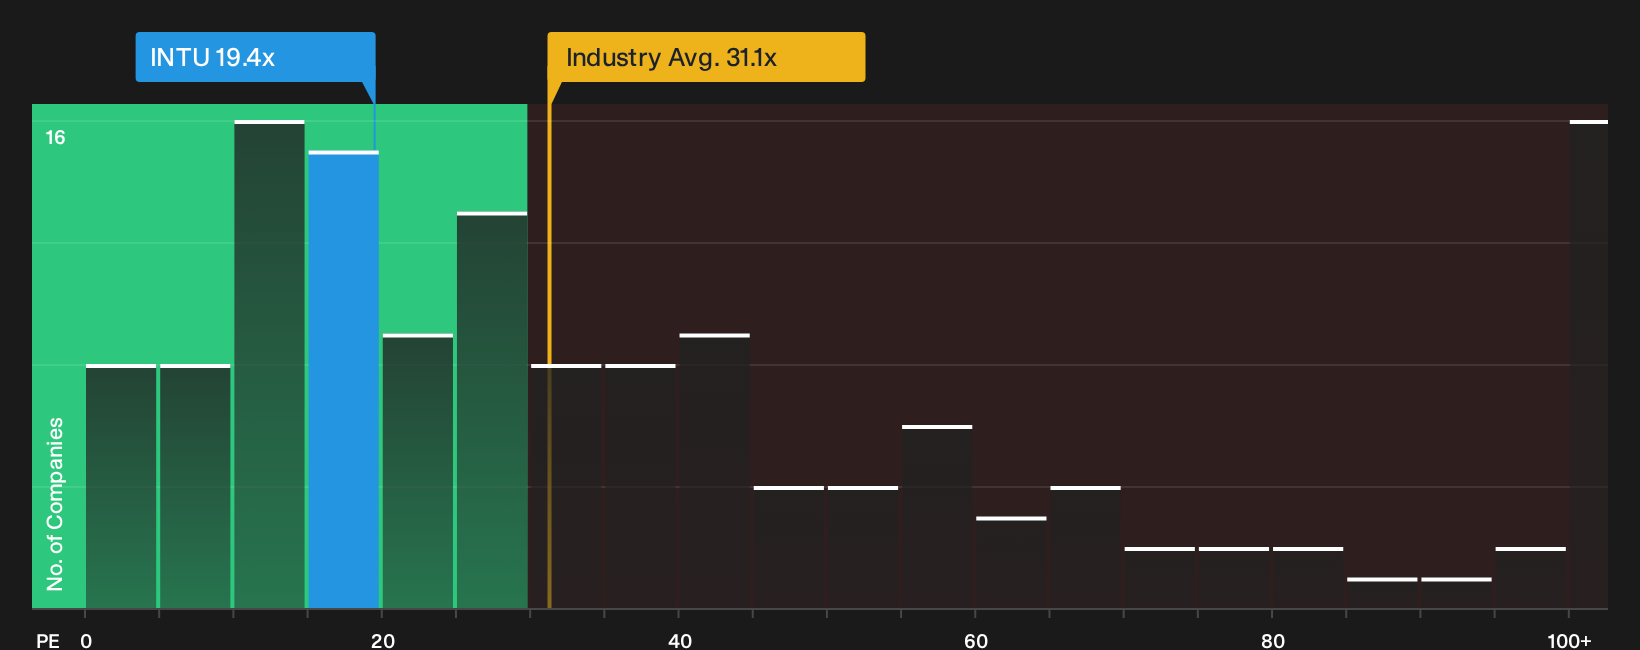
The P/E ratio suits Intuit because earnings remain a key anchor for how investors think about its tax and small business platforms. At a current P/E of 19.4x, the stock trades below the wider software industry average of 31.1x, which suggests the market is pricing Intuit’s profit stream more cautiously than a typical software peer. Compared with a peer group average of 49.9x, that gap becomes even wider.
The Fair Ratio, which reflects what investors might usually pay given Intuit’s sector, scale and risk profile, also sits above the present 19.4x figure. On this framework, the stock screens as undervalued. Because the launch of Credit Karma Tax with AI assistance helped lift sentiment but only modestly, the current multiple still points to a discount versus both the tailored Fair Ratio view and broader peer benchmarks. Explore the numbers behind Intuit's P/E valuation.
The Intuit Narrative: What Would Justify Today's Price?
Narratives on Intuit pick up where that P/E puzzle leaves off. They spell out which paths for Intuit's growth, profitability and earnings would need to play out for the current valuation to look conservative or demanding. Each one ties its number to a clear view on how revenue trends, margin direction and risk factors could evolve, so you can revisit those assumptions as new information filters through on Simply Wall St's Community page.
Community views on Intuit are now split between those who see a high quality franchise on sale and those who think expectations still run too hot.
Bull case: 41% undervalued
"The idea goes beyond chatbots answering questions, these AI agents would execute actual workflows, monitoring cash flow and reconciling accounts..."
Discover why this Narrative puts Intuit at 41% undervalued.
Bear case: 14% overvalued
"The OpenAI partnership concentrates part of Intuit's customer acquisition funnel on one external platform, any change in that partner's priorities could dampen new customer growth..."
Explore why this Narrative puts Intuit at 14% overvalued.
Intuit's share price is only one piece of the picture
The valuation work gets you part of the story, yet the projections professionals have mapped out for Intuit over the next few years offer a separate lens to weigh against today’s market view. Explore where analysts expect Intuit to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com