


- Arvest Bank reported that it has upgraded to FICO Auto Score 10 across its auto lending operations, integrating the model into existing decisioning systems with support from Fair Isaac.
- The bank’s early portfolio analysis points to sharper risk segmentation, especially for thin-file borrowers. This highlights how newer FICO Auto scores can change underwriting precision for regional lenders.
- Next, the focus shifts to how Fair Isaac’s investment narrative around newer scores and decisioning software is affected by Arvest’s move to FICO Auto Score 10.
Scan how Fair Isaac’s scoring upgrade story fits into a wider credit risk theme by reviewing a curated set of 30 resilient stocks with low risk scores that aim to prioritize resilience over headline excitement.
Fair Isaac Investment Narrative Recap
Owning Fair Isaac means buying into the idea that newer scores and decisioning tools can offset pressure in legacy mortgage scoring and keep the business anchored in high quality recurring revenue. The Arvest Bank move into FICO Auto Score 10 points to demand for more granular risk tools, although this looks incremental rather than a major shift in the story.
The near term swing factor still sits in how quickly lenders adopt newer FICO scores and FICO Platform, while the biggest risk remains regulatory and competitive pressure on mortgage related Scores combined with heavy leverage. If cash generation disappoints, that debt load can squeeze flexibility on AI and platform investment.
The Arvest Auto Score 10 upgrade is the clearest recent operational proof point tied to these catalysts. It shows Fair Isaac can work closely with a regional lender to slot a new model into existing workflows, keep the familiar 250 to 900 range and deliver sharper risk views on mid band and thin file borrowers.
That kind of embedded integration matters because it supports the broader narrative around newer FICO models and governed decisioning software. If more banks treat Score 10 and related tools as default infrastructure across portfolios, it can help counter mortgage pricing pressure, though execution on client onboarding and support needs to remain very tight.
Fair Isaac's current narrative rests on analysts expecting revenue to reach US$3.0b and earnings to reach US$1.0b by 2029, based on an assumed 8.2% yearly revenue growth rate and an earnings increase of about US$185.0m from current earnings of US$815.0m.
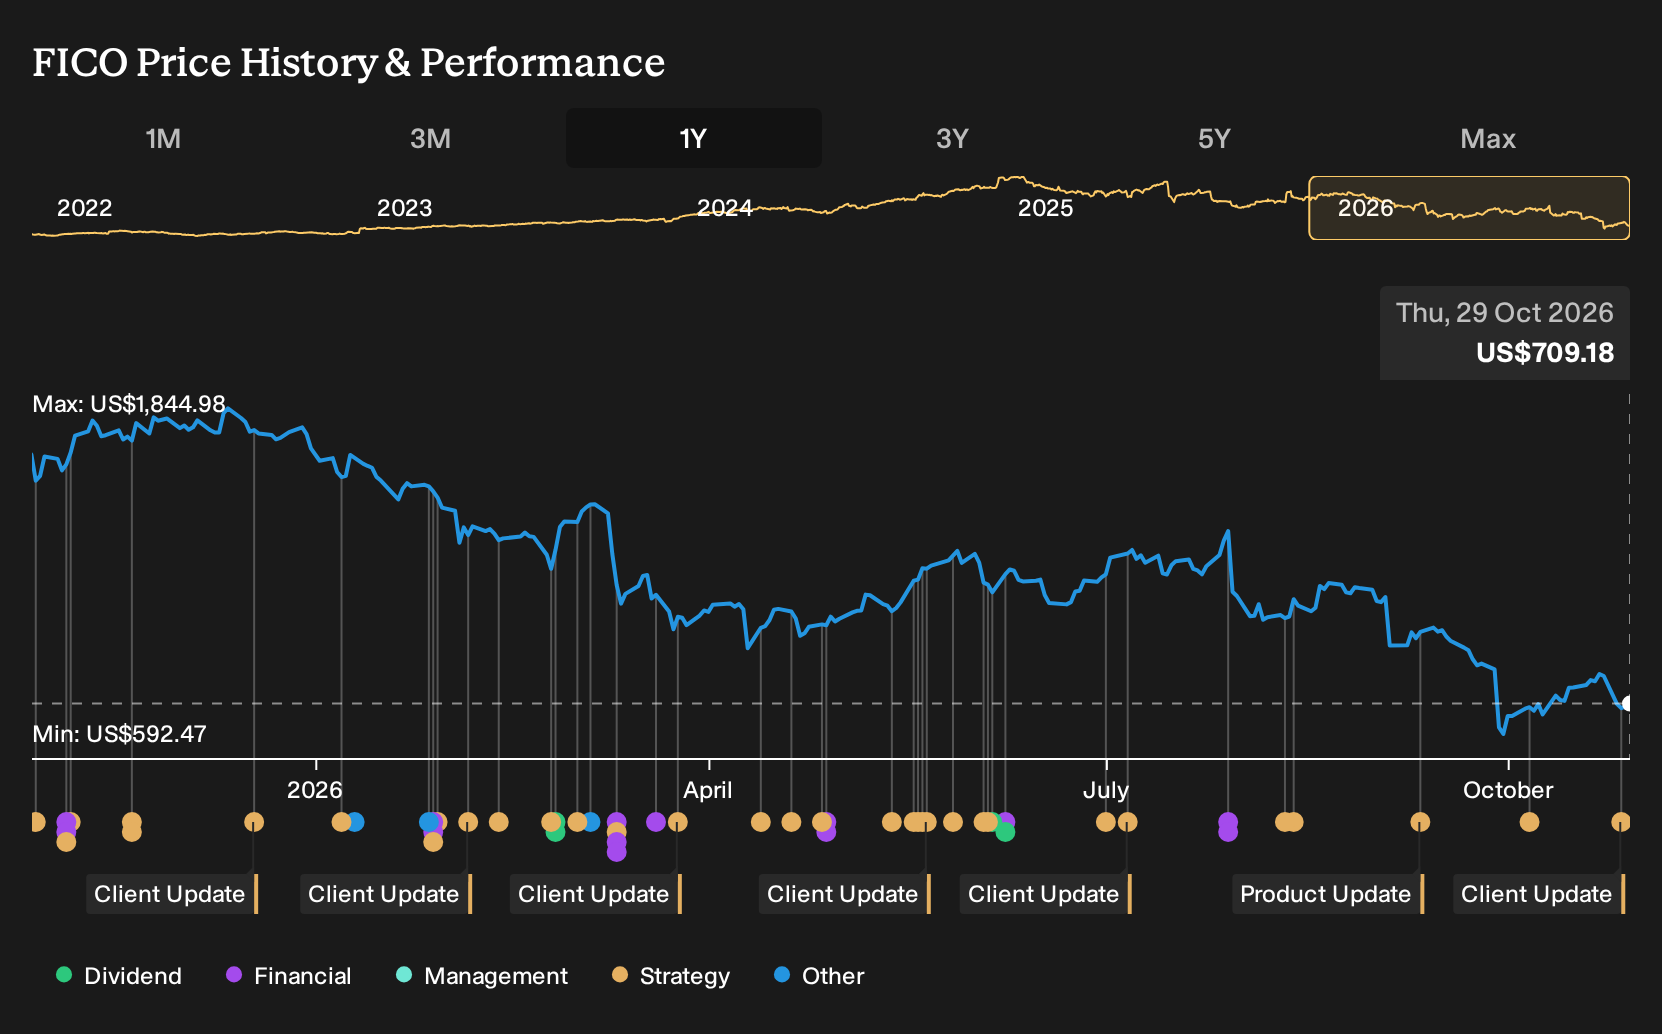
Uncover why Fair Isaac's fair value indicates a 32% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate Fair Isaac angle leans hard into the FICO Platform catalyst. The most optimistic analysts were already penciling in about US$3.5b of revenue and US$1.2b of earnings by 2029 before this Arvest news. You can read that as a far more upbeat story and decide whether this upgrade justifies revisiting those pre news assumptions.
Explore 6 other Fair Isaac fair value estimates, including one that suggests as much as 88% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Fair Isaac research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Fair Isaac. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fair Isaac's overall financial health at a glance.
Looking For More Ideas Beyond Fair Isaac?
Once you have a handle on Fair Isaac, it can help to widen the lens and compare it with other companies filtered by the traits you care about most.
- If capital preservation sits high on your list, focus on companies that already score well on resilience and balance sheet strength with a 30 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable entry point, you can zero in on businesses that look attractively priced on fundamentals through the 30 high quality undervalued stocks.
- If steady cash returns appeal to you, filter for companies that pair higher yields with solid financial footing by using the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com