


Even when a business is losing money, it's possible for shareholders to make money if they buy a good business at the right price. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. But while the successes are well known, investors should not ignore the very many unprofitable companies that simply burn through all their cash and collapse.
Given this risk, we thought we'd take a look at whether Everlast Minerals (ASX:EV8) shareholders should be worried about its cash burn. In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. First, we'll determine its cash runway by comparing its cash burn with its cash reserves.
When Might Everlast Minerals Run Out Of Money?
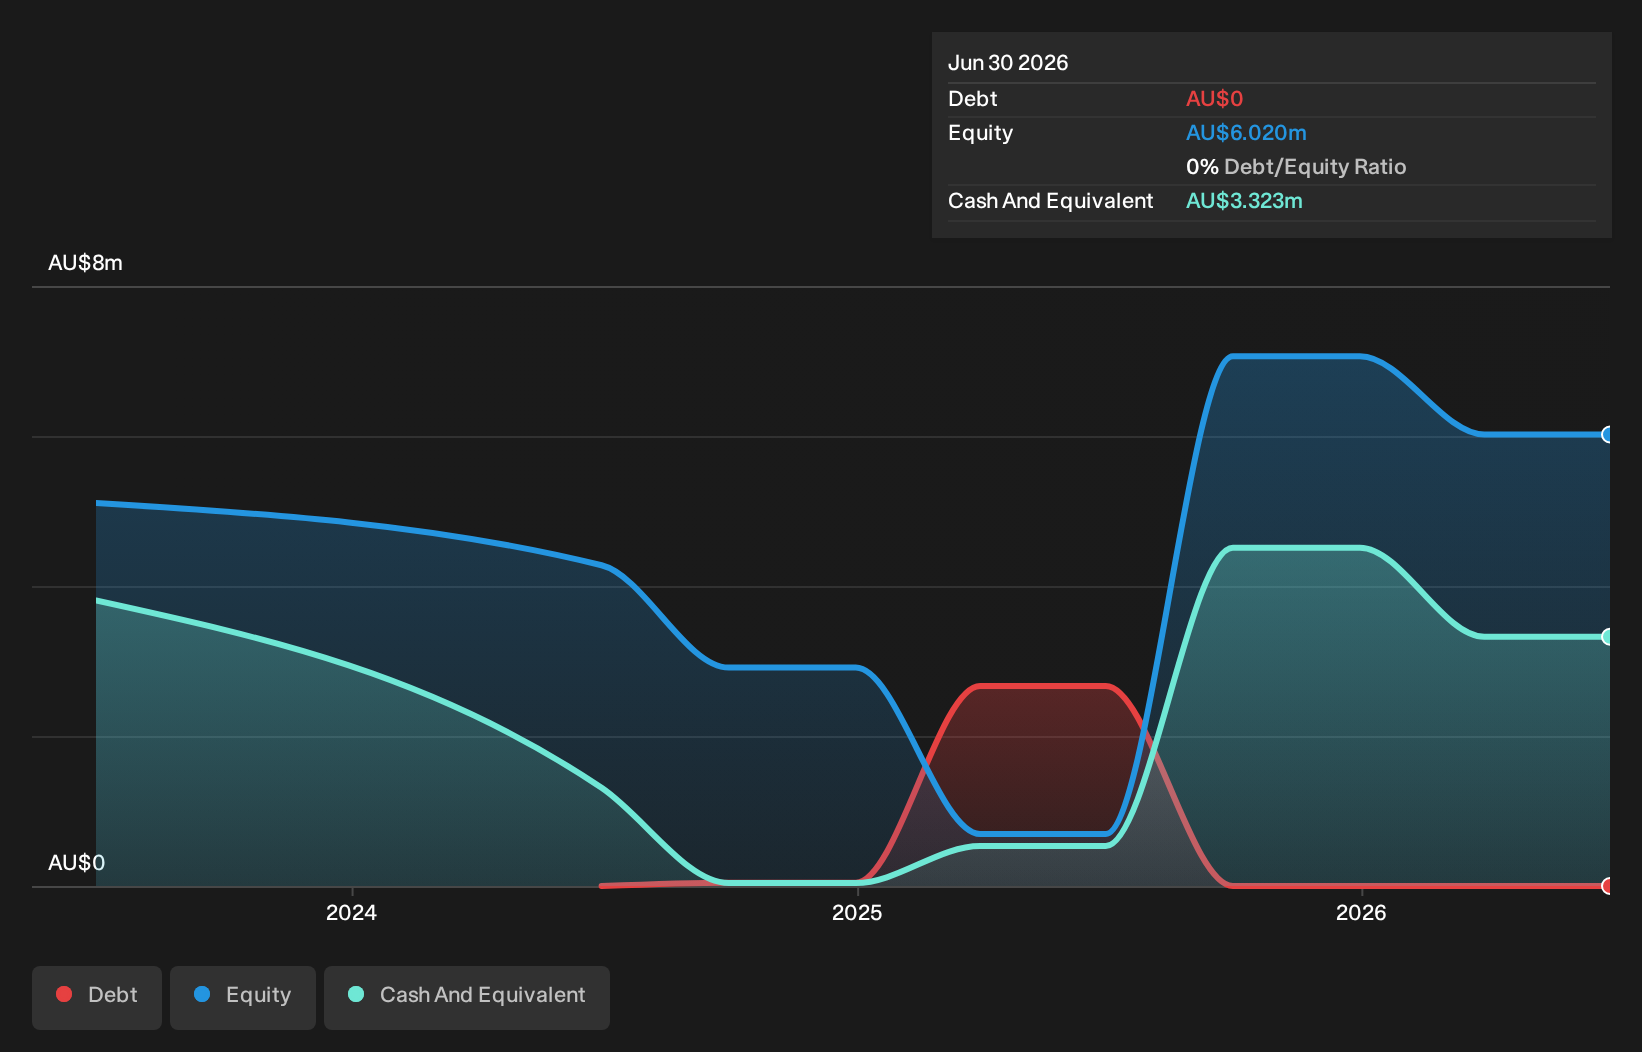
A company's cash runway is the amount of time it would take to burn through its cash reserves at its current cash burn rate. As at June 2026, Everlast Minerals had cash of AU$3.3m and no debt. In the last year, its cash burn was AU$2.7m. Therefore, from June 2026 it had roughly 15 months of cash runway. While that cash runway isn't too concerning, sensible holders would be peering into the distance, and considering what happens if the company runs out of cash. Depicted below, you can see how its cash holdings have changed over time.
See our latest analysis for Everlast Minerals
How Is Everlast Minerals' Cash Burn Changing Over Time?
Whilst it's great to see that Everlast Minerals has already begun generating revenue from operations, last year it only produced AU$35k, so we don't think it is generating significant revenue, at this point. As a result, we think it's a bit early to focus on the revenue growth, so we'll limit ourselves to looking at how the cash burn is changing over time. As it happens, the company's cash burn reduced by 11% over the last year, which suggests that management are maintaining a fairly steady rate of business development, albeit with a slight decrease in spending. Everlast Minerals makes us a little nervous due to its lack of substantial operating revenue. So we'd generally prefer stocks from this list of stocks that have analysts forecasting growth.
Can Everlast Minerals Raise More Cash Easily?
Even though it has reduced its cash burn recently, shareholders should still consider how easy it would be for Everlast Minerals to raise more cash in the future. Companies can raise capital through either debt or equity. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Everlast Minerals has a market capitalisation of AU$42m and burnt through AU$2.7m last year, which is 6.3% of the company's market value. Given that is a rather small percentage, it would probably be really easy for the company to fund another year's growth by issuing some new shares to investors, or even by taking out a loan.
So, Should We Worry About Everlast Minerals' Cash Burn?
The good news is that in our view Everlast Minerals' cash burn situation gives shareholders real reason for optimism. One the one hand we have its solid cash burn reduction, while on the other it can also boast very strong cash burn relative to its market cap. Cash burning companies are always on the riskier side of things, but after considering all of the factors discussed in this short piece, we're not too worried about its rate of cash burn. On another note, we conducted an in-depth investigation of the company, and identified 3 warning signs for Everlast Minerals (2 are a bit unpleasant!) that you should be aware of before investing here.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of interesting companies, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.