


Recent commentary on Argan (AGX) has zeroed in on a growing power and data center project backlog, while persistent margin questions in the Power and Industrial segments push investors to reassess what the stock is worth today.
Recent weakness in Argan’s share price, including a 1-day share price return of down 3.57% and a 90-day share price return of down 39.68%, contrasts sharply with a very large 3-year total shareholder return of about 7x. This suggests long-term holders are still well ahead even as the market reprices its expectations around the enlarged backlog and ongoing margin risks.
Scan a curated set of power and data infrastructure stocks that face similar backlog and margin trade offs to Argan through our 41 power grid technology and infrastructure stocks
Argan now trades at a steep discount to analyst targets after a sharp pullback, yet cash flow based estimates flag potential overvaluation. Is the market being too harsh on backlog risks, or too generous on execution?
Most Popular Narrative: 40% Undervalued
Argan’s most followed narrative pegs fair value at $570.50 using an 8.8% discount rate, which sits well above the recent $344.11 close. The gap hinges on whether the current $2.5b backlog and capital light model can support earnings and cash generation against recent margin pressure.
Electrification, AI data centers, electric vehicles and onshoring manufacturing are feeding into a multi year build out of dispatchable power generation. Argan’s current $2.5b committed backlog that is about 80% natural gas projects and 11% renewable positions future revenue to be tied to this demand.
Large combined cycle gas plants remain a niche engineering and construction market with only a handful of capable contractors. Argan’s focus on complex gas projects and stated capacity to execute 10 to 12 jobs simultaneously can support revenue scale and operating leverage as more projects are awarded.
See why 129 investors see Argan as 40% undervalued.
Result: Fair Value of $570.50 (UNDERVALUED)
Still, the bullish Argan story can crack if gross margins in newer gas projects remain subdued or if Industrial work continues to drag on earnings longer than expected.
Find out about the key risks to this Argan narrative.
Another View On Argan’s Valuation
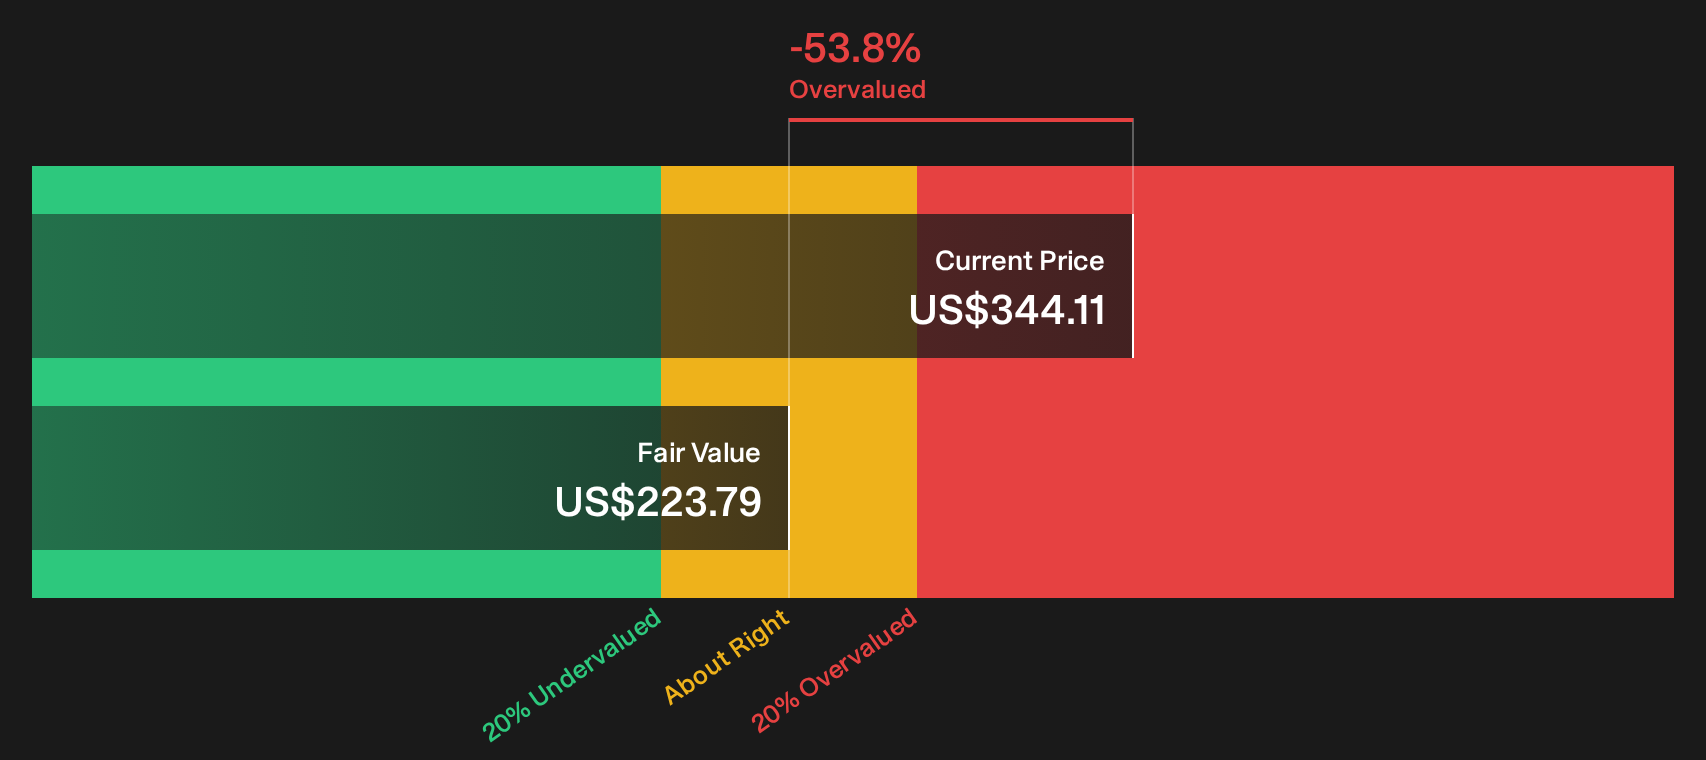
The popular narrative paints Argan as about 40% undervalued, yet the Simply Wall St DCF model tells a different story. On that cash flow view, Argan at $344.11 trades above an estimated future cash flow value of $223.79, which points to an overvalued reading instead.
This gap between an earnings based fair value of $570.50 and a DCF figure of $223.79 is wide. It puts the spotlight on one question for you: which cash flow or earnings path feels more realistic over time for Argan?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Argan for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Argan’s valuation can feel messy. Move quickly, pull up the same numbers, and pressure test both the risks and rewards for yourself through the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Argan?
If you only stop at Argan, you could miss other opportunities that fit your style even better, so put the Simply Wall St Screener to work.
- Target resilient income by reviewing 6 dividend fortresses that aim to pair higher yields with solid underlying businesses.
- Hunt for mispriced potential through the 18 high quality undiscovered gems that combine quality fundamentals with lower investor attention.
- Prioritize peace of mind by scanning 30 resilient stocks with low risk scores that score well on financial strength and volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com