


California Water Service Group came into this print as the steady regulated utility investors lean on for predictability. The stock had drifted only modestly over the past month and then ticked up 1.7% to US$48.45 after the Q3 2026 figures hit.
The headline was simple and powerful. Q3 earnings per share landed just above US$1.04 on revenue of about US$332.2m, with net income of roughly US$65.4m. For a water utility where rate cases and capital spending usually drive the story, this quarter was all about earnings strength outpacing the share price move.
Like the earnings punch from California Water Service Group but want other regulated-style plays with solid fundamentals and less price drama? Scan our curated screener of list of solid balance sheet and fundamentals stocks (25 results) for a broader set of utility like stocks that pair earnings power with balance sheet strength.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$332.17m vs. US$311.24m (up about 6.7%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$65.41m vs. US$61.23m (up about 6.8%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.05 vs. US$1.03 (up about 2.0%)
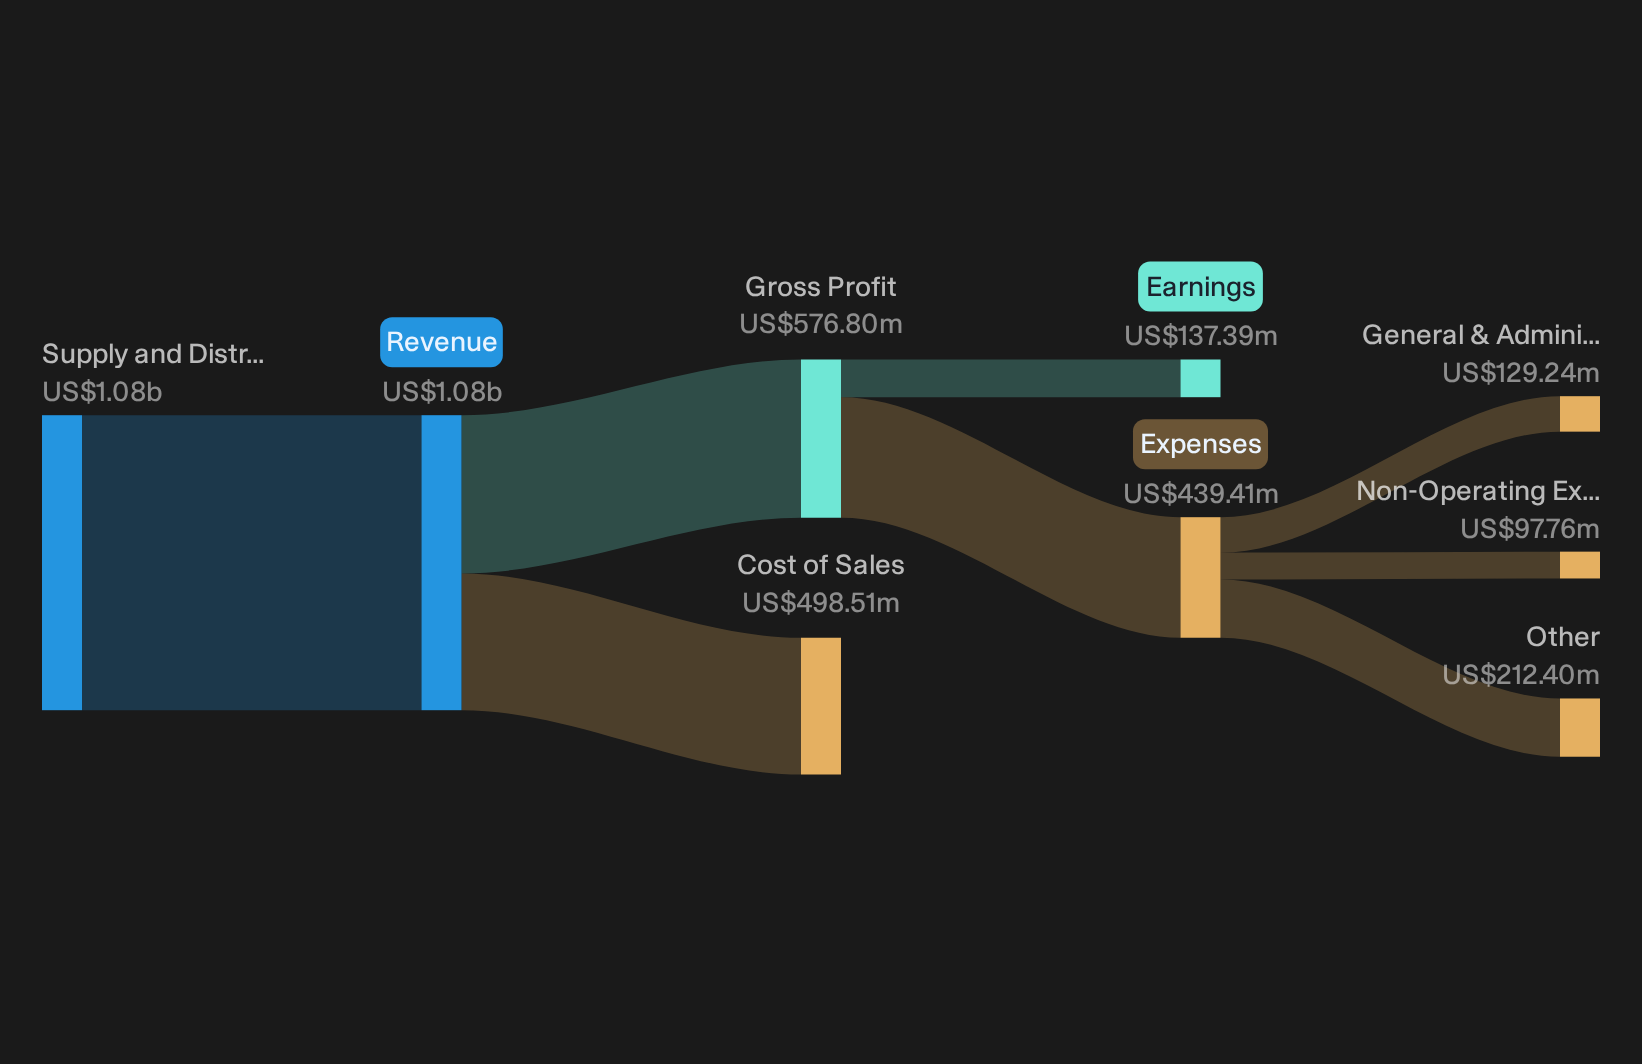
- Trailing 12 Month Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$137.39m vs. US$136.39m (up about 0.7%)
Ask Charlie what record capex means for California Water Service Group returns.
California Water Service: Capital Plan Put To The Test
California Water Service pitches capital growth and expansion as a path to higher earnings capacity.
"Accelerating capital investment in water infrastructure and modernization is now backed by a roughly 11% 10 year growth capital CAGR and management expectations for nearly 12% rate base CAGR to around US$3.5b by 2028. This can support higher regulated revenue and earnings capacity for California Water Service Group."
Q3 does line up with that script. Record capex near US$425m year to date and Q3 revenue of US$332.2m with net income of US$65.4m show the bigger asset base is already feeding regulated returns, even after higher taxes and conservation spending.
Can California Water Service Turn Expansion Into Earnings?
The push into new territories carries a separate execution bar.
"Ongoing expansion into Texas, Nevada and Oregon through the Nexus Water Group acquisition and full ownership of the BVRT venture, with change of control approvals in process for nearly 100,000 additional connections and more than 24 wastewater plants, creates a new source of customer growth that can add to future revenue and earnings."
Recent quarters still lean heavily on California and existing western operations for revenue and profit. Q3 uplift is driven by rate changes, DREMA and other approved mechanisms. The contribution from Nexus and BVRT is not yet visible, so the multi state earnings leg remains a forward promise rather than a delivered milestone.
One Narrative disagrees with today's price. → See where this Narrative says California Water Service Group should trade.
Hunt For Quiet Earnings Power
California Water Service Group just showed how a solid quarter can leave the share price only modestly changed. The real opportunity could be spotting stocks where fundamentals improve before valuations fully catch up.
- Company 1 - 31% below our estimate - builds massive AI compute clusters that serve as overflow capacity when primary cloud regions face peak demand.
- Company 2 - 37% below our estimate - uses an asset light carrier network and emerging AI tools to direct freight toward higher value heavy haul and platform loads.
- Company 3 - 48% below our estimate - moves upstream from contract assembly into co-designing complex hardware and embedding engineering teams inside long lived industrial and AI systems.
Three companies from the same screener. Open every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com