


Cavco Industries just delivered Q2 FY2027 numbers that hit the market like a jolt. The stock jumped 13.4% to US$620.69 on Friday, a sharp move for a manufactured housing producer that many investors still file under slow and steady. Behind that surge sit record quarterly revenue of US$656.4m and earnings per share of US$7.22. Together, these figures point to one dominant theme. The strongest positive trend is volume and pricing power in factory-built homes, and the gap between cautious expectations and these results is exactly what set the share price alight.
Excited by Cavco Industries delivering record revenue and earnings but want a wider field of factory-built housing and construction-linked opportunities with similar strength in pricing power and demand momentum? Check out the screener of stocks in our list of solid balance sheet and fundamentals stocks (25 results)
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): US$656.4m vs. US$556.5m (up roughly 18%)
- Net Income (Excl. Extra Items, Q2 2027 vs Q2 2026): US$55.4m vs. US$52.4m (up about 6%)
- Basic EPS (Q2 2027 vs Q2 2026): US$7.22 vs. US$6.62 (higher by roughly 9%)
- Consolidated Gross Margin (Q2 2027 vs Q2 2026): 22.5% vs. 24.2% (margin compressed by around 1.7 percentage points)
Ask Charlie what Cavco’s new data-center housing means for growth.
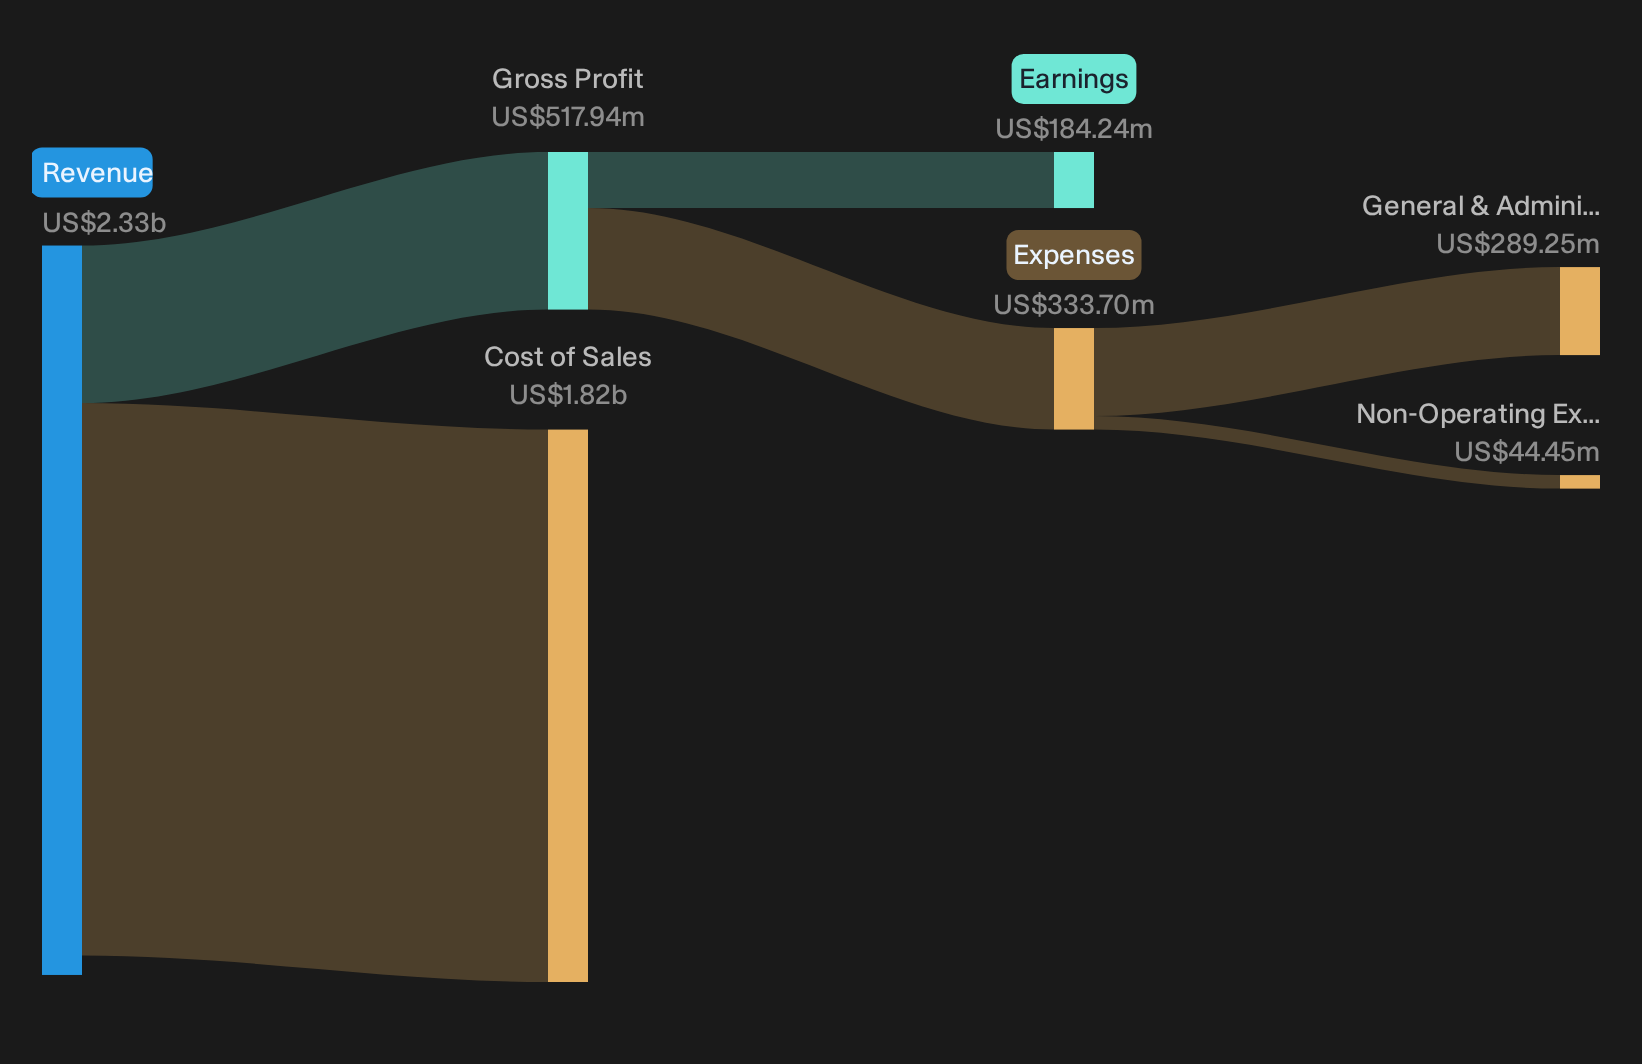
Cavco margins start to answer the bull story
Supporters argued Cavco Industries did not just need volume. They wanted order momentum and integration work to translate into cleaner profitability.
"The main thing that has to go right is Cavco Industries converting strong order momentum, capacity additions, and cost synergies into healthier margins despite ongoing tariff and input cost headwinds."
Record shipments and 18% revenue growth show the volume piece is working. Factory built margin of 21.1% and consolidated margin of 22.5% are still below last year, so the margin uplift is not there yet. A slight sequential margin gain and strong Financial Services mix are early but incomplete steps toward that goal.
Tariff and cost worries not fully laid to rest
The bear story has focused on tariffs and input inflation eroding profitability even when Cavco keeps plants busy.
"Exposure to escalating tariffs on key components such as lighting, electrical and plumbing sourced from China remains a live issue. Management is still quantifying a possible quarterly cost of goods sold impact in the low single digit millions of US dollars."
Q2 confirms that pressure. Gross margin compressed from 24.2% to 22.5% year on year while materials like steel moved higher. Management says price increases largely offset these costs and sequential margins ticked up, so the issue is contained rather than resolved. The risk remains visible in the margin line rather than hypothetical.
One Narrative disagrees with today's price. → See where this Narrative says Cavco Industries should trade.
Hunt For Pricing Power Disconnects
Cavco Industries just showed how quickly sentiment can reset when reported numbers collide with cautious expectations. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 35% below our estimate - builds the compute platform large data centre customers rely on to run AI workloads at scale and deepen integration with a proprietary software stack.
- Company 2 - 30% below our estimate - sells AI centric networking and infrastructure customers adopt as they shift workloads into recurring, higher margin cloud and consumption based services.
- Company 3 - 37% below our estimate - uses an asset light freight network and AI tools to push more heavy haul loads through vetted carriers while tightening fraud and insurance control.
That is three of the list. See the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com