


Starbucks stock slipped 1.8% to US$103.58 by the close, even as fresh Q4 2026 results landed with eye catching profit progress. The company delivered Q4 earnings per share of US$0.59 on revenue of US$9.1b, while full year earnings per share reached US$2.72 and topped management’s own guidance range.
Short term traders saw a modest pullback. Longer term holders are focusing on a business that is pushing operating margins higher and laying out forecasts that lean on earnings growth rather than heavy new store expansion.
Like the profit progress at Starbucks but want more consumer stocks that lean on earnings quality instead of constant expansion risk? Check out the list of solid balance sheet and fundamentals stocks (25 results)
Q4 2026 Earnings Summary
- Revenue (Q4 2026 vs Q4 2025): US$9.14b vs. US$9.57b (top line declined 4.5%)
- Net Income (Q4 2026 vs Q4 2025): US$677.2m vs. US$133.2m (profit increased more than 4x)
- Basic EPS (Earnings Per Share) (Q4 2026 vs Q4 2025): US$0.59 vs. US$0.12 (per share earnings rose more than 4x)
- Same Restaurant Sales Growth (Q4 2026 vs Q3 2026): Not disclosed for Q4 vs. 7.9% in Q3 (prior quarter showed solid same store momentum)
Starbucks grew earnings even as reported revenue slipped this quarter. Ask Charlie what really drove Starbucks’ big margin jump.
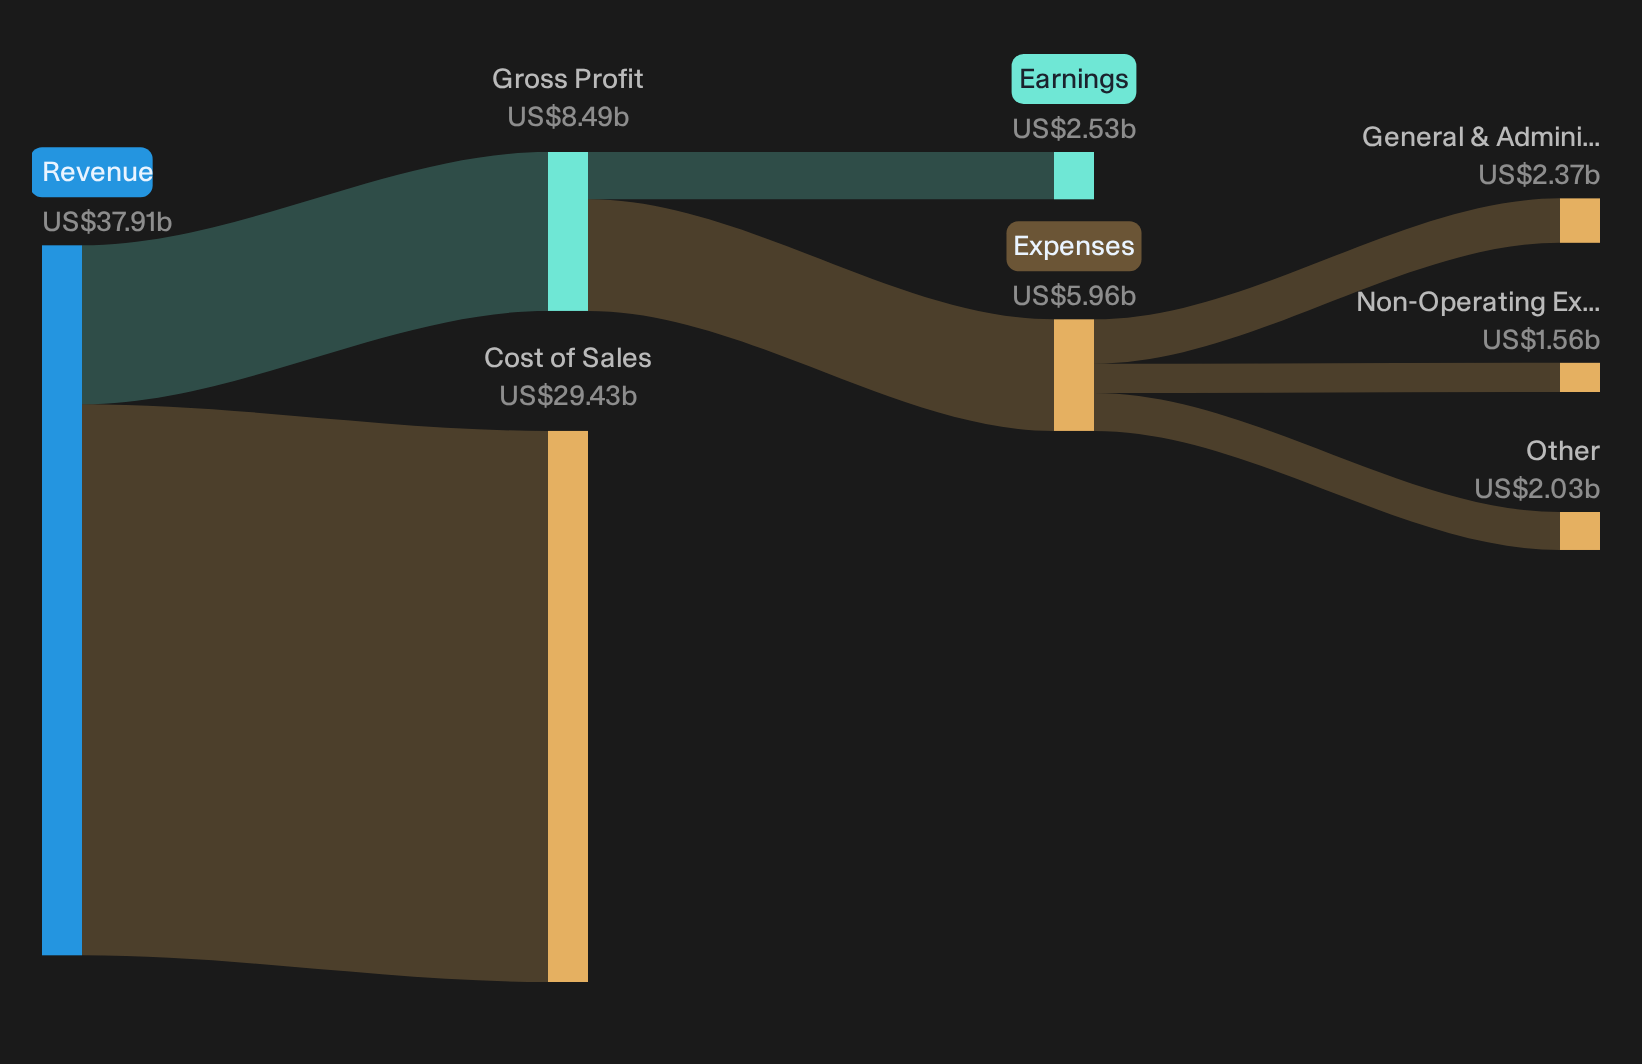
Starbucks Turnaround Claims Meet Margin Reality
Bulls argue Starbucks can translate the “Back to Starbucks” playbook into sustained earnings power rather than one off fixes.
"The main thing that has to go right is that Starbucks converts its remodel program, digital Rewards growth, and capital light international expansion into sustained comparable sales growth that more than offsets ongoing labor, legal, and brand risk pressures."
Q4 goes some distance toward that bar. Global comps rose 7.2% with U.S. at 7.7%, and operating margin expanded about 450 bps to roughly 14%. EPS of US$0.80 lifted full year earnings to US$2.72, above guidance. Early cost savings and remodels are now visible in the income statement rather than just in management slides.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Starbucks Margins Improve, But Remodel Burden Lingers
Bearish analysts focus on whether Starbucks can grow profits while spending heavily to refresh thousands of cafes and deal with legal and labor issues.
"Bearish analysts expect Starbucks to face continued pressure on store level profitability as remodel spending, regulatory issues, and labor related risks keep global operating margins under strain even when same store sales are healthy."
Q4 operating margin around 14% and a roughly 450 bps lift show clear progress; yet management still guides FY27 margin to only 13.5 to 14%. That cautious outlook, plus roughly US$1b in uplift spend, US$300m of restructuring and 247 net North America closures in Q4, suggests remodel and labor costs are still a real drag, not a closed chapter.
Hunt For Mispriced Earnings Power
Starbucks shows how earnings progress can coincide with a pullback in the share price. The real opportunity sits in finding stocks that could be undervalued before the market adjusts.
- Company 1 - 38% below our estimate - taps government backed trade in programs to draw more used devices into its refurbishment network.
- Company 2 - 46% below our estimate - broadens its solar hardware platform so storage and inverter sales deepen ties with large project developers.
- Company 3 - 31% below our estimate - embeds its chips and software into essential data plumbing that demanding computing customers treat as core infrastructure.
Three companies from the same screener. Open every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com