


OneSpan just served up the kind of quarter that stirs emotion. The stock exploded 27.2% in Friday trading to US$25.63, after investors digested Q3 2026 numbers that put profitability squarely in the spotlight.
At first glance it looks like pure euphoria. Under the surface, the business printed US$63.9 million in revenue and US$19.3 million in adjusted EBITDA with a 30.1% margin. The real story is margin power. The question now is whether that one day surge reflects a sober read of the earnings or enthusiasm racing ahead of the fundamentals.
Love OneSpan’s 30.1% EBITDA margin but unsure whether a one day 27.2% surge is the right risk payoff for your portfolio? Cross check this kind of profitability profile against our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 OneSpan Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$63.9 million vs. US$57.1 million (up about 12%).
- Net Income, Excl. Extra Items (Q3 2026 vs Q3 2025): US$7.8 million vs. US$6.5 million (higher year on year).
- Basic EPS (Q3 2026 vs Q3 2025): US$0.21 vs. US$0.17 (improved earnings per share).
- Adjusted EBITDA Margin (Q3 2026 vs Q3 2025): 30.1% vs. prior year level not disclosed in this report (indicates strong profitability in the quarter).
OneSpan says DigipassONE is key to its next growth phase. Ask Charlie what DigipassONE means for OneSpan's future growth.
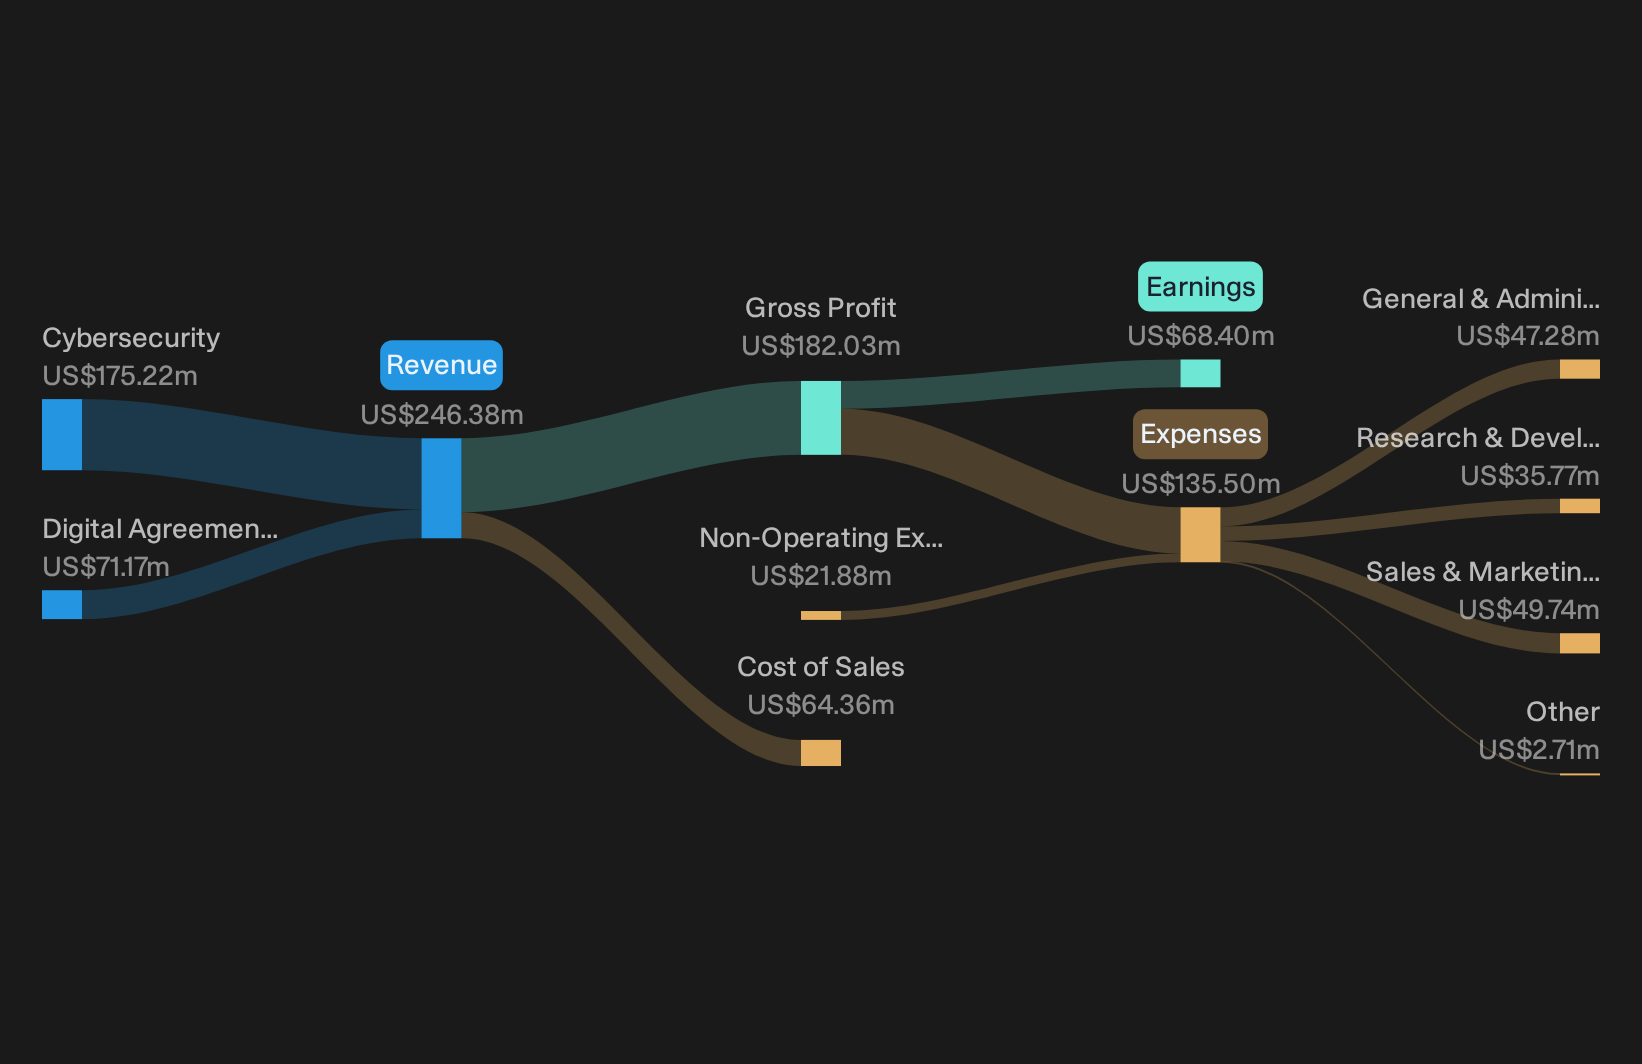
Evaluating OneSpan’s Subscription Upside Against Q3 Milestones
Optimistic investors have argued that OneSpan can turn its subscription tilt into steadily stronger recurring earnings power.
"Bullish analysts expect OneSpan to compound its shift toward higher margin subscription software and authentication services into stronger recurring earnings power over the coming years."
The latest quarter gives that idea more grounding. Subscription now accounts for 81% of revenue, ARR sits at US$195.5 million and net retention is 105%. Cybersecurity and Digital Agreements both grew double digits, while gross margin reached 76.3% and adjusted EBITDA margin hit 30.1%. Raised full year revenue and EBITDA guidance further supports the claim that the subscription mix is already translating into higher quality earnings.
One Narrative disagrees with today's price. → See where this Narrative says OneSpan should trade.
OneSpan Bear Case: Subscription Gains Still On Trial
The harsher view on OneSpan centers on whether subscription wins can really outpace churn and deal dilution. That concern is captured in the warning that
"the $3 million ARR loss from two non financial customers that did not renew points to a risk that churn in newer verticals offsets mix improvement and limits future ARR and earnings progression."
Q3 ARR of US$195.5 million, up 8.5% with 105% net retention, shows churn is not spiraling. Yet ARR growth still trails subscription revenue growth and management is leaning on guidance raises rather than breaking out churn in newer sectors, so the long term attrition risk is not fully cleared.
Hunt For Mispriced Earnings Power
OneSpan shows how sentiment can change quickly when profitability becomes clearer. The real opportunity is assessing companies that may be undervalued before stronger execution reshapes assumptions about their earnings power.
- Company 1 - 21% below our estimate - expands advanced photonics packaging capacity so more complex work fills higher value production lines.
- Company 2 - 48% below our estimate - co-designs hardware systems for industries seeking supplier input from first sketch through scaled production.
- Company 3 - 42% below our estimate - sells modular server and storage building blocks that fit directly into expanding AI and data infrastructure projects.
That is three of the list. See the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com