


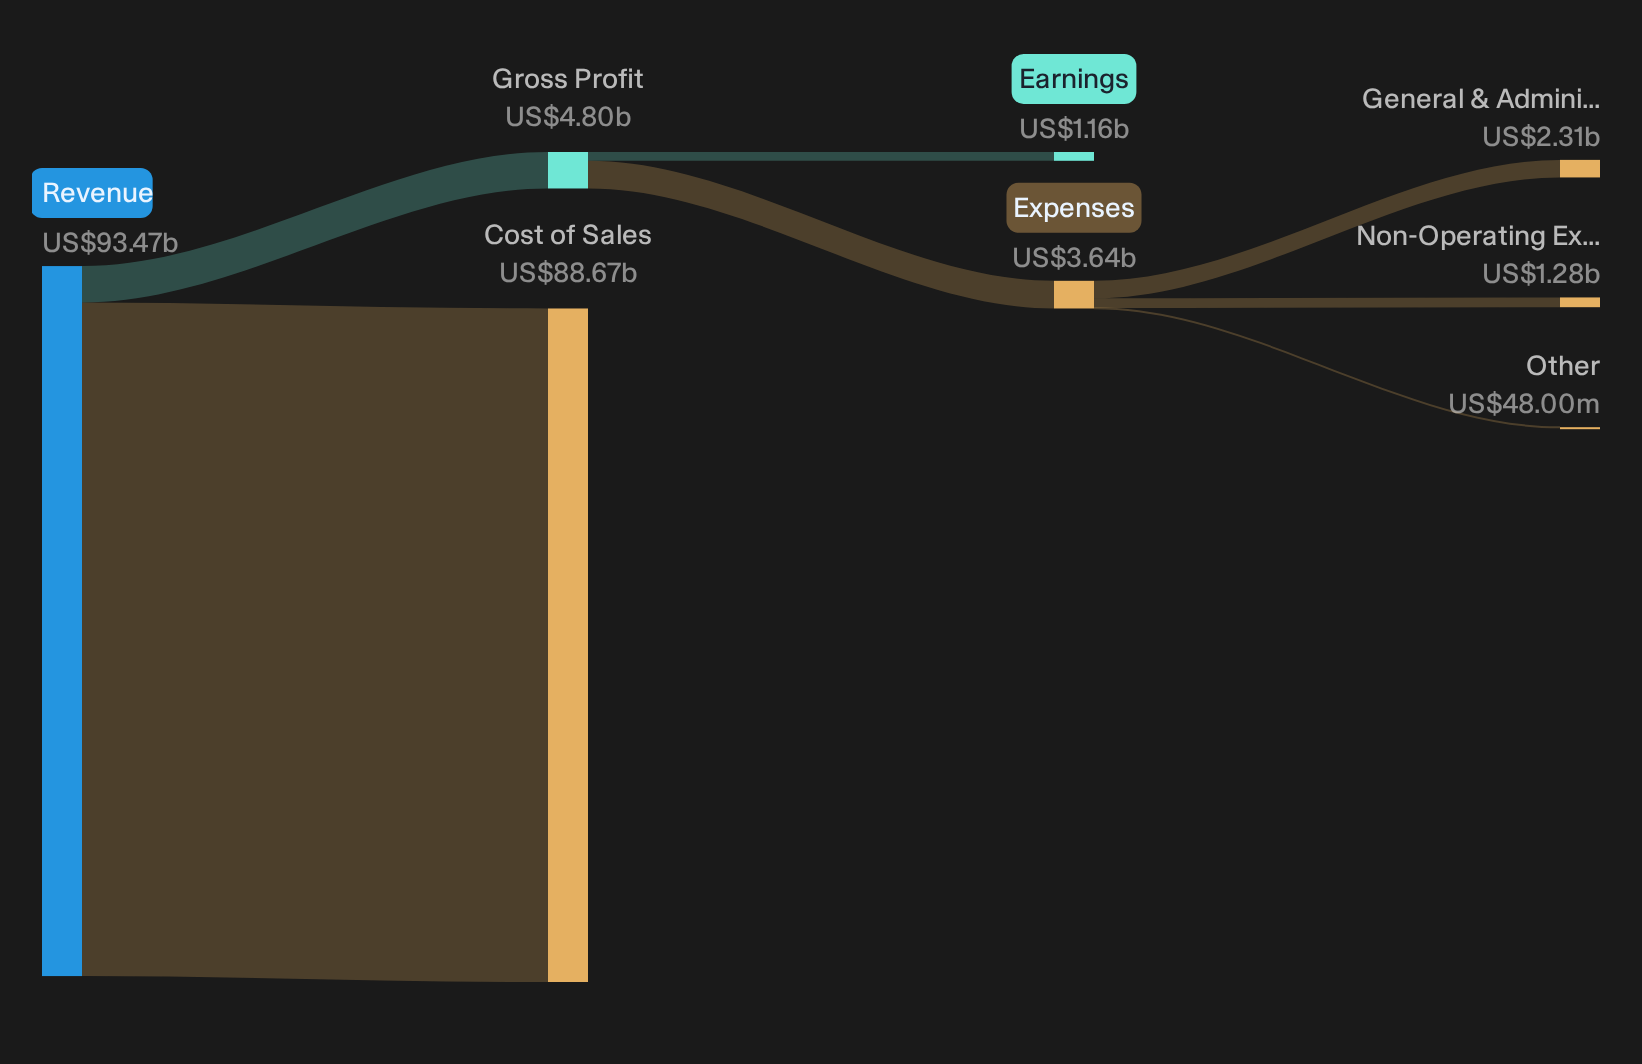
Bunge Global walked into its Q3 2026 release with a stock that had drifted for months, down roughly 9% over both the 30 day and 90 day windows. Then the company posted quarterly basic earnings per share of about US$1.64 on revenue of roughly US$23.8b and the market hardly flinched. The share price moved only about 0.6% on the day. That muted reaction sits at odds with the real story here, which is an earnings profile defined far more by a profit squeeze than by any headline revenue figure.
Love that Bunge Global is still putting up multi billion dollar revenue prints but concerned that earnings power looks squeezed and the share price has barely reacted. If you want agriculture exposed businesses with sturdier profit profiles, check out our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$23,804m vs. US$22,155m (up about 7.4%)
- Net Income (Q3 2026 vs. Q3 2025): US$318m vs. US$169m (up about 88.2%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.64 vs. US$0.86 (up about 91.3%)
- Trailing 12 Month Net Income (Q3 2026 TTM vs. Q3 2025 TTM): US$1,159m vs. US$1,326m (down about 12.6%)
Ask Charlie what Bunge Global expects from its 2027 projects.
Bunge Global: Bull Story Hinges On Synergy Delivery
The bullish pitch around Bunge Global is that the Viterra tie up steadily lifts the earnings base rather than just bulking up volume.
"Integration of Viterra into Bunge's end to end value chain is creating a broader origination, processing and logistics footprint. Management expects this to translate into durable synergies and a higher earnings base across segment EBIT and adjusted EPS."
Q3 gives that claim some backing. Adjusted EPS rose to US$2.56 while adjusted segment EBIT reached US$997m, with management now targeting more than US$200m of cost savings in 2026 and pointing to additional contributions in 2027. Reaffirmed 2026 adjusted EPS guidance of US$9.25 to US$9.75 signals that, so far, integration benefits are keeping pace with higher interest and ramp costs.
One Narrative disagrees with today's price. → See where this Narrative says Bunge Global should trade.
Bunge Global: Bear Fears On Margins Only Partially Visible
The harsher view on Bunge Global argues that heavy inventories and policy uncertainty could choke pricing power in processing and keep returns muted.
"Heavy soybean oil stocks in the U.S. and very spot oriented customer behavior could persist even after biofuel policy is clarified, which would cap pricing power in crush and refining and put pressure on segment EBIT and net margins."
Q3 shows some of that pressure in weaker soybean oil merchandising and softer refining in multiple regions, even as soybean and softseed processing EBIT improved. Reaffirmed 2026 adjusted EPS guidance and higher adjusted segment EBIT indicate that, for now, Viterra synergies and project ramp benefits are offsetting the margin drag rather than fully validating the bearish scenario.
Hunt Quiet Dislocations Before They Close
Bunge Global just showed how an earnings story can accompany a muted share price. The real opportunity is finding companies that could be undervalued before the market closes that gap.
- Company 1 - 48% below our estimate - turn a record backlog of technology heavy, modular projects into higher utilization and more complex installation work.
- Company 2 - 31% below our estimate - thread into critical digital infrastructure where data traffic is processed, connected, and secured across diverse applications.
- Company 3 - 37% below our estimate - fold recent acquisitions into a broader lending and deposit platform while directing customers toward lower cost, more efficient digital banking channels.
Three companies from the same screener. Open all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com