


- Marriott International is extending its fee focused hotel network by signing new Courtyard and Westin franchise agreements in Japan and committing to a Le Méridien resort in Rishikesh, while also appointing a new Director of Sales & Marketing for its Hyderabad properties.
- The mix of fresh franchise deals in Asia and expanded commercial leadership in India adds to Marriott International's future fee pipeline rather than tying up capital in owned real estate.
- We will now look at how Marriott International's asset light fee expansion in Japan and India could reshape its investment narrative.
Marriott International Investment Narrative Recap
For Marriott International, the core belief is that an asset light, fee driven model can keep generating high quality earnings as the room pipeline is brought into the system, even while owner economics are being rebalanced. The immediate swing factor is how quickly fee revenue tracks new signings, while regional pressure in the Middle East and volatile owned and leased income remain key watchpoints.
The Hyderabad sales and marketing appointment looks operational rather than thesis changing. It supports execution on group, corporate and MICE demand in an important Indian market but does not meaningfully alter the near term catalysts around global RevPAR, technology rollout or Bonvoy economics, nor does it reduce the risk from construction delays or one off charges.
The most relevant recent development for this story is the deepening global expansion, highlighted by franchise deals such as Courtyard by Marriott Hida Takayama and the Le Méridien Rishikesh Resort & Spa signing. These fit directly into Marriott International’s pipeline driven catalyst, where more branded keys can translate into higher fee streams as projects open.
For you as an investor, the link is execution. New hotels in Japan and India increase exposure to travel demand outside the Middle East, but they also raise delivery risks around construction timelines and owner returns. The Hyderabad leadership change sits in that same bucket. It is about whether Marriott International can keep filling the funnel and then convert pipeline, loyalty and technology into durable fee income despite regional and margin pressures.
Marriott International's current analyst narrative points to revenues of US$30.7b and earnings of US$3.9b by 2029, based on an assumed 60.7% yearly revenue growth rate and an earnings increase of about US$1.3b from US$2.6b today.
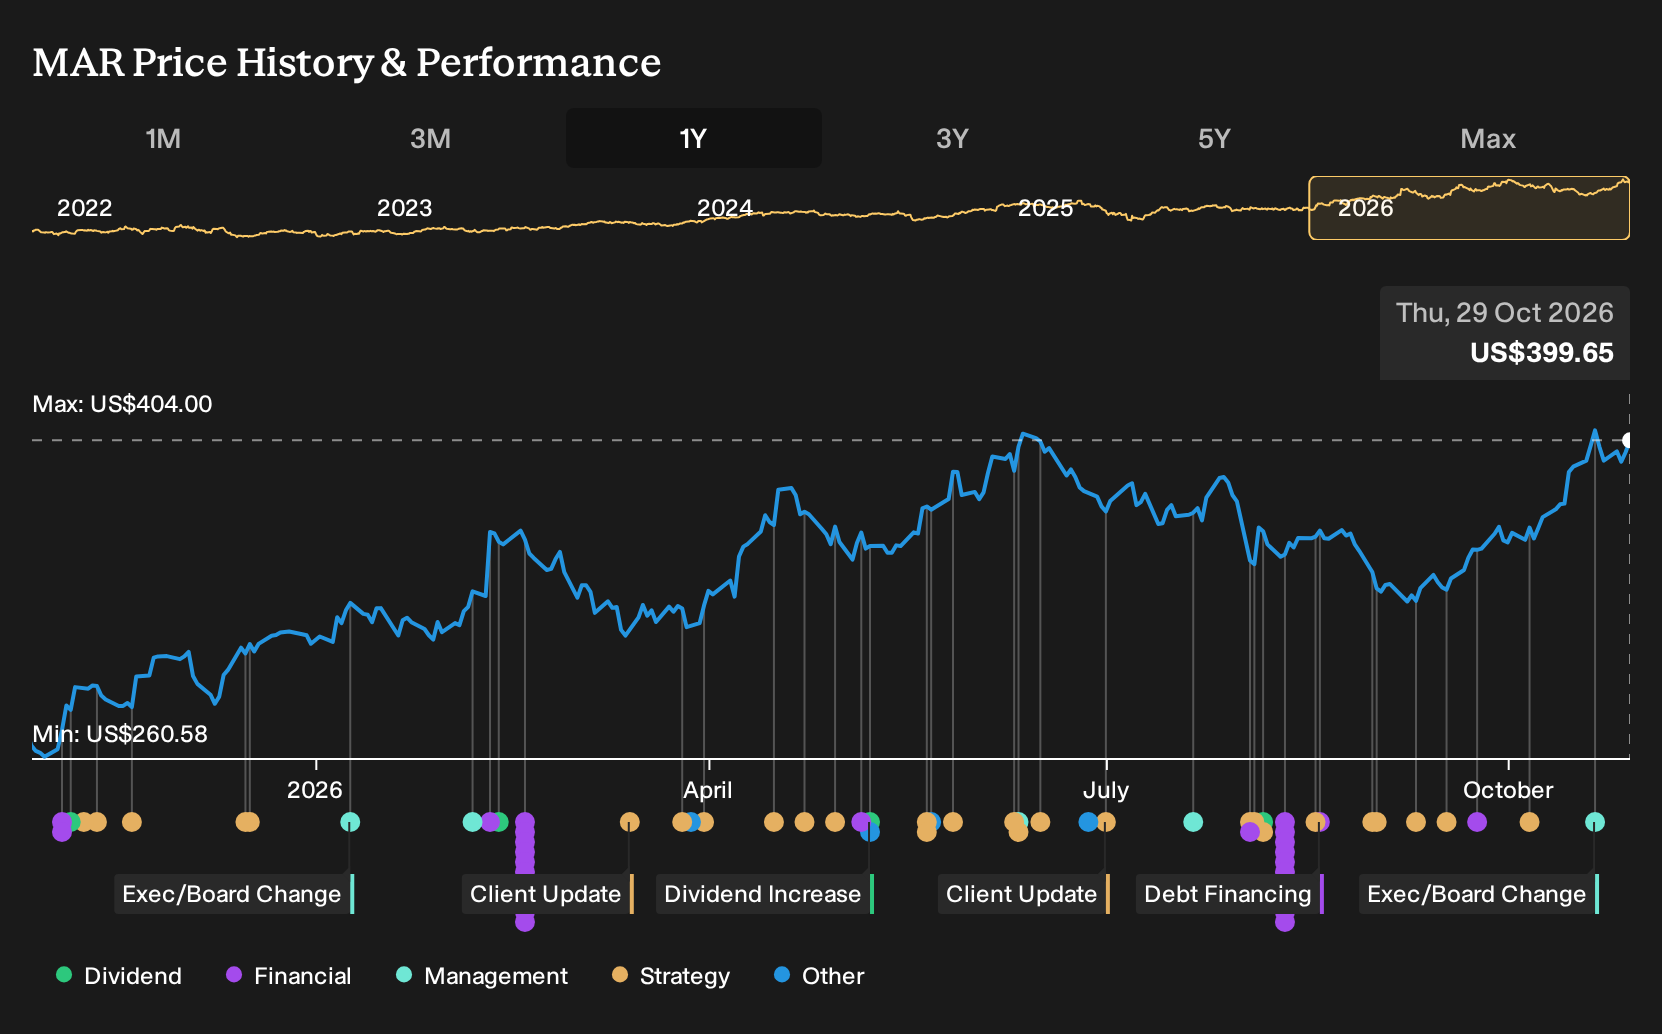
Uncover why Marriott International's fair value indicates a 5% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate angle focuses on execution risk in technology rather than Middle East exposure. Bullish analysts, who were expecting Marriott International to reach about US$39.7b in revenue and US$4.4b in earnings by 2029, see AI tools like Ask Bonvoy as key. You can compare that optimism with today’s Hyderabad leadership news and decide whether those pre news assumptions still feel realistic.
Explore 3 other Marriott International fair value estimates, including one that suggests it could be worth as much as $387.77.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Marriott International research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Marriott International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marriott International's overall financial health at a glance.
Looking For More Ideas Beyond Marriott International?
If Marriott International sits on your watchlist but you want a broader bench of opportunities, the Simply Wall St screener can help you line up other candidates that fit different risk and income profiles.
- If capital preservation is a priority, start with companies that score well on resilience and balance sheet strength through the 30 resilient stocks with low risk scores.
- For investors who like to be paid while they wait, scan for income focused opportunities through the 5 dividend fortresses.
- To widen your opportunity set beyond familiar tickers, look for under the radar businesses with solid fundamentals in the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com