


Alliant Energy came into this Q3 2026 report with a reputation as a steady Midwestern utility, not a thrill ride, yet the stock quietly climbed 1.4% to US$71.65 into the first full day after the release. The headline this time is profit power. Quarterly basic earnings per share landed at about US$1.53 on net income of US$398 million, indicating a strong recent profit trend, even as the share price reaction looked relatively restrained.
If you appreciate the earnings power of Alliant Energy but want a broader range of steady compounders for comparison, take a look at the list of solid balance sheet and fundamentals stocks (25 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$1,285 million vs. US$1,210 million (up about 6.2%)
- Net Income, Excl. Extra Items (Q3 2026 vs Q3 2025): US$398 million vs. US$281 million (up about 41.6%)
- Basic EPS (Q3 2026 vs Q3 2025): US$1.53 vs. US$1.09 (up about 40.4%)
- Net Profit Margin, Trailing 12 Months (latest vs. prior year): 20.7% vs. 19.1% (margin improved)
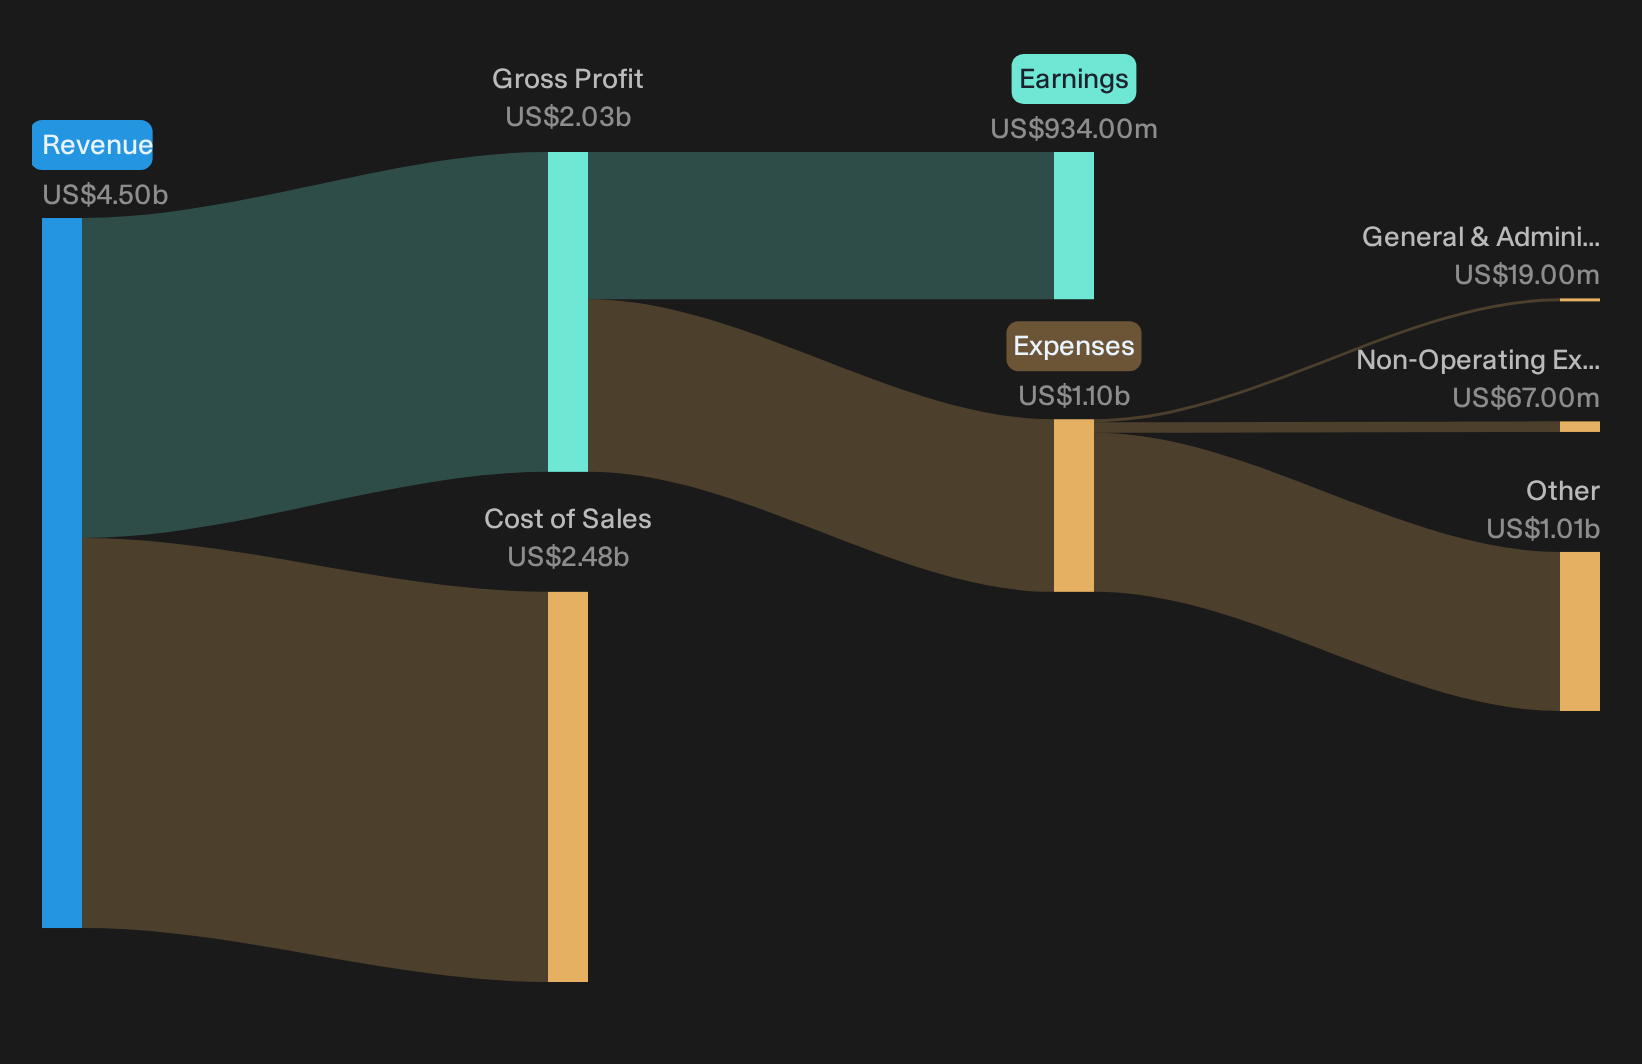
Data Center Growth Story Meets Early Reality
The bullish story around Alliant Energy rests on large hyperscale projects turning into durable load and earnings. The key claim is clear.
"The accelerating construction and onboarding of large-scale data centers under five executed electric service agreements totaling about 3.4 GW of contracted demand, plus a further 2 to 4 GW pipeline of large-load opportunities, points to a multi year step up in Alliant Energy’s electricity sales and regulated revenue base as these projects ramp through 2031."
Q3 already shows higher retail electric sales helped by early data center ramps and large C&I demand. Management narrowed 2026 EPS guidance to the upper half of the range and set 2027 guidance above 2026, which lines up with that ramp, while a 19% larger 2027 to 2030 capex plan confirms Alliant is building for that contracted load.
Cost Pressure And Concentration Risks Under The Microscope
Bears worry that the same growth plan could backfire if costs surge or big customers stall. The risk is spelled out directly.
"Operations and maintenance expenses are already running higher due to business growth, new resources, and outage timing. Further increases as Alliant Energy adds around US$13.4b of new projects could outpace the margin contribution from new load, which would pressure net margins and earnings even if revenue continues to rise."
Q3 already reflects higher O&M, depreciation and financing tied to a growing fleet and rate base. Yet trailing 12 month net margin sits at 20.7% compared with 19.1% a year earlier, and management still raised long term earnings growth expectations, so higher costs are evident but not yet eroding profitability in these results.
One Narrative disagrees with today's price. → See where this Narrative says Alliant Energy should trade.
Hunt Quiet Mispricing Opportunities
Alliant Energy just showed how a solid profit story does not always coincide with a sharp share price move. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 34% below our estimate - converts customer prepayments into higher margin optical and solar infrastructure components.
- Company 2 - 29% below our estimate - scales a digital banking platform where stronger engagement and efficiency support earnings across major consumer markets.
- Company 3 - 48% below our estimate - embeds engineering teams earlier in product design so recurring sketch to scale work replaces lower margin assembly.
That is three of the list. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com