


Southside Bancshares came into this Q3 2026 report with a quiet reputation as a conservative Texas bank and a stock that had already crept higher, up about 12% over the past month. The fresh numbers just put more weight behind that move. Earnings per share landed at about US$0.94 on net income of roughly US$28 million, and the net interest margin, a key profitability gauge for any lender, improved to just above 3%. The share price only added 1.1% today, which understates how firm the recent trend in profitability looks.
If you like that steady net interest margin but want a broader set of banks and financials with similar balance sheet discipline on your radar, check out our list of solid balance sheet and fundamentals stocks (25 results)
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$73.28 million vs. US$42.64 million (up 71.9%)
- Net Income, excl. extra items (Q3 2026 vs. Q3 2025): US$27.98 million vs. US$4.91 million (up very large, around 5.7x)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.94 vs. US$0.16 (up very large, around 4.7x)
- Net Interest Margin, or NIM (Q3 2026 vs. Q3 2025): about 3.0% vs. 2.94% (slightly higher)
Southside Bancshares’ margins rose as more loans reset higher. Ask Charlie which rate move could matter most for Southside Bancshares.
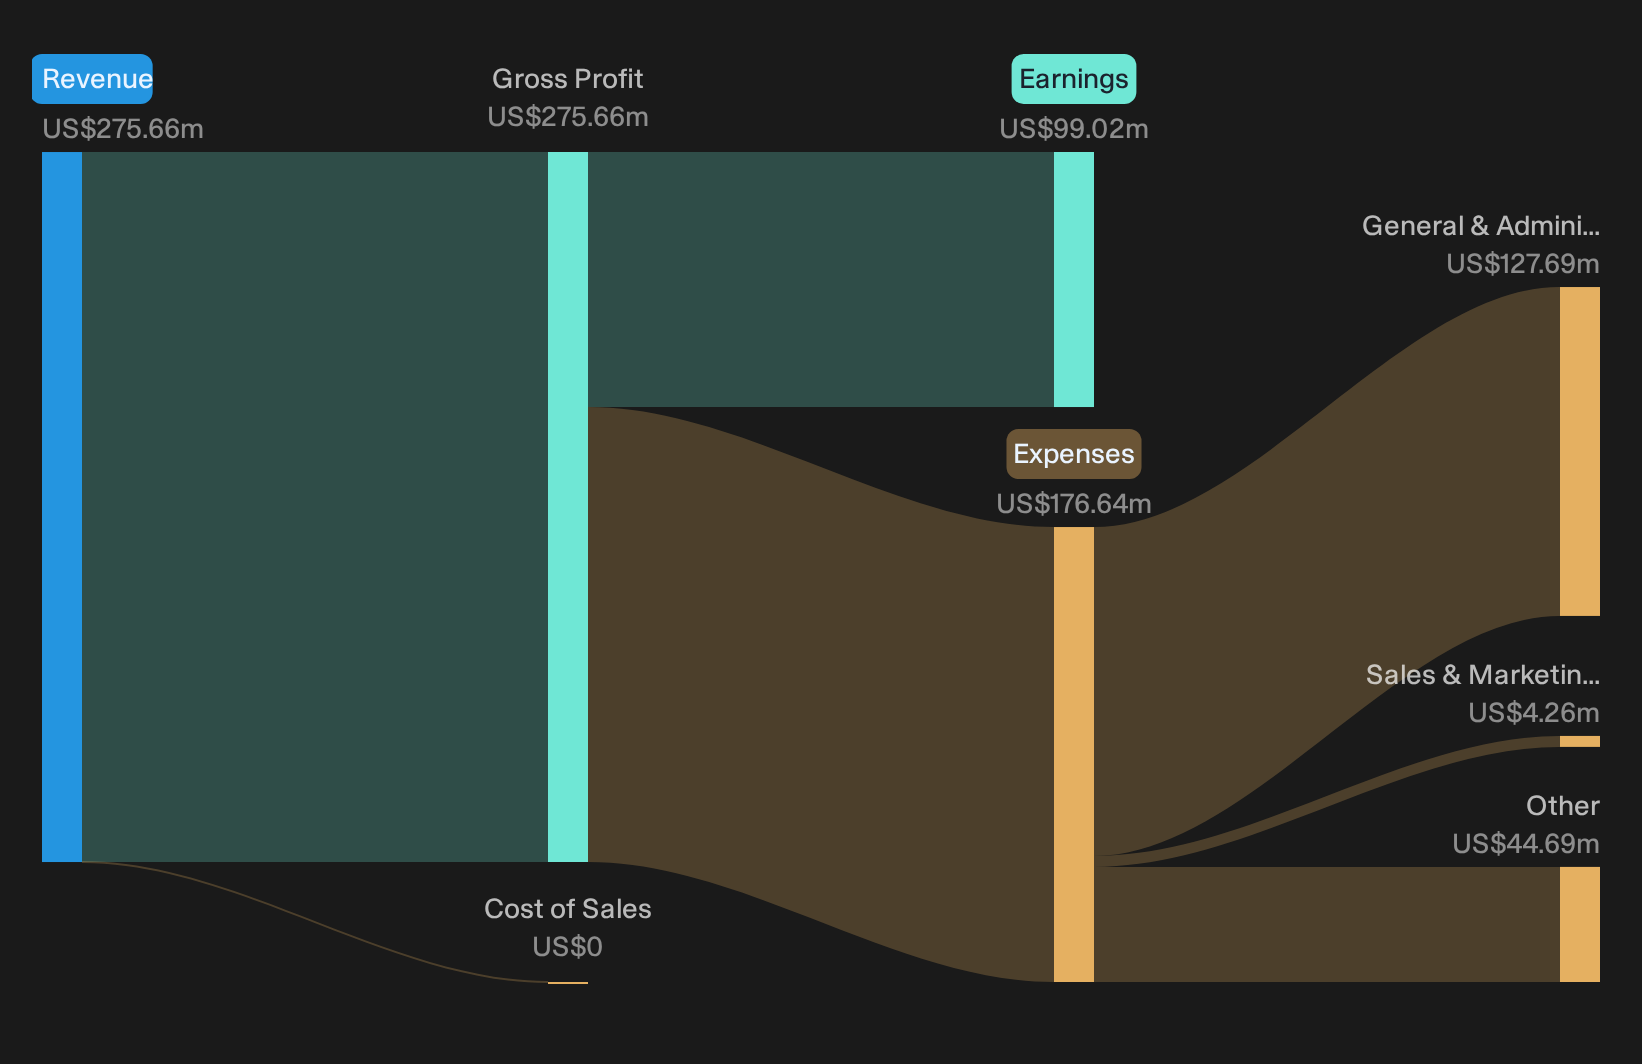
Southside Bancshares: Testing The Growth Blueprint
Optimists argue that Southside Bancshares is building a higher earning, more fee rich franchise anchored on Texas metro expansion and balance sheet tweaks.
"Conversion of loan production offices to full service branches and new branch construction in areas such as The Woodlands, Tyler, and Southlake Prosper is set to deepen Southside Bancshares’ presence in faster growing Texas metros and can support future loan growth, core deposits, and fee based revenue."
Q3 shows early proof on earnings power rather than volumes. Loans were roughly flat, yet NIM ticked above 3% and net income reached US$28.0m. Higher yielding MBS and bank sub debt helped lift net interest income even while deposit balances declined, suggesting the balance sheet changes are starting to carry more weight.
Funding Strain And Margin Risk Under The Microscope
On the flip side, the bear story says funding cost creep and choppy deposits could eat away at these margin gains.
"Rising and volatile funding costs, including wholesale balances of about US$1.4b and a spread on swap funding that has roughly tripled since year end, along with intense deposit competition and pressure to increase rates on public fund CDs, could erode the benefit of higher yielding assets and lead to weaker net interest margin and earnings than investors expect for Southside Bancshares."
This quarter does not fully confirm that concern. NIM improved to just above 3% and funding costs were described as largely flat. Yet deposits fell US$155.6m, wholesale balances moved to US$1.7b, and US$517m of CDs reprice soon, so the pressure point has shifted into the coming quarters rather than disappeared.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt Quiet Mispricing Before It Fades
Southside Bancshares just showed how a solid quarter and modest share reaction can leave questions about what is already priced in. The real opportunity could sit in stocks that look misaligned with their underlying business shifts before the gap closes.
- Company 1 - 35% below our estimate - builds high power AI racks that reshape data centre capacity planning and energy sourcing decisions.
- Company 2 - 46% below our estimate - converts a near record backlog of complex mega-projects into cash as dispute heavy legacy work tapers.
- Company 3 - 48% below our estimate - co-designs critical hardware for AI and industrial systems through a sketch-to-scale engagement model with key customers.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com