


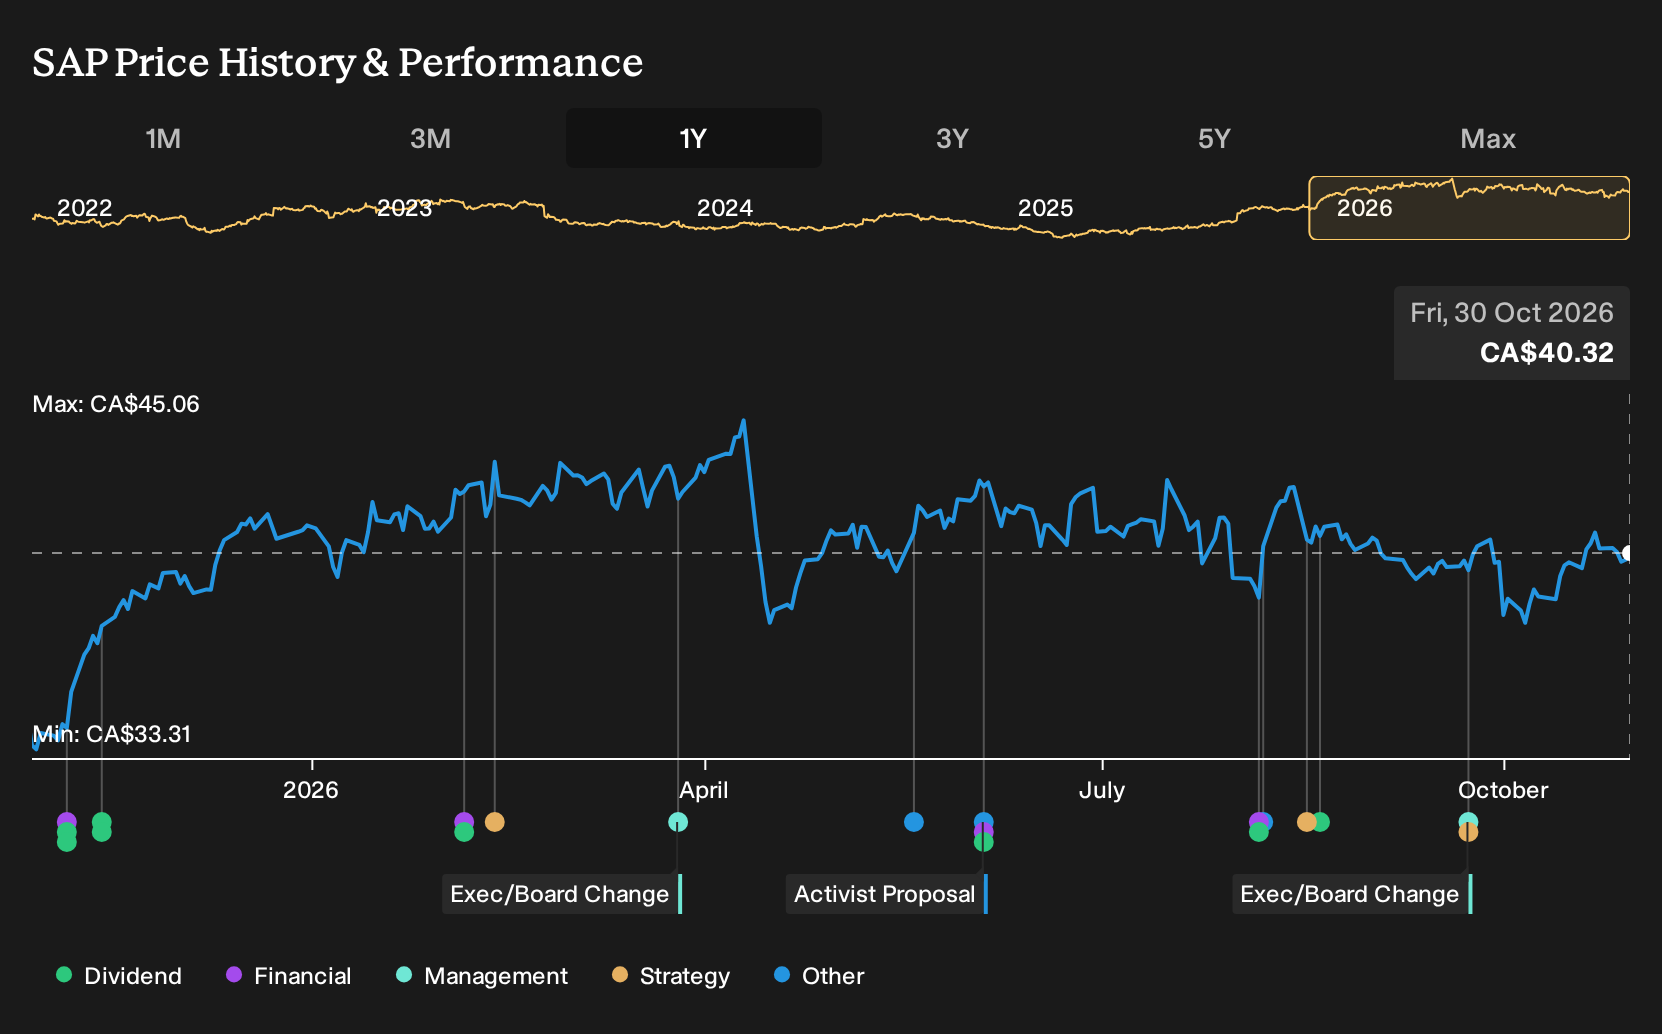
If you only skimmed Saputo headlines about plant-based competition and environmental scrutiny, a 12 month hold might have looked like a coin flip. Holding Saputo over the past year would have returned 21.4%, including dividends. That outcome lands between bullish talk of premium dairy demand and bearish warnings about pressured margins. If an investor had committed fresh capital back in October 2025, what exactly in the record justified taking that specific risk?
Saputo has already moved. See which of 3 high quality undervalued stocks still trade below our estimates.
The Two Saputo Stories Investors Had To Weigh
The shares cost CA$33.31 at the start of the period, and anyone looking at Saputo then had to choose between two very different stories.
On the optimistic side, the bullish Narrative pointed to a Fair Value of CA$38, a price those assumptions implied, built on revenue growth of 3.2% and profit margins rising toward 5.0% as premium dairy demand and global expansion helped earnings.
The bearish view argued for a Fair Value of CA$27.37, based on 2.3% revenue growth, a 4.2% margin assumption, and the risk that plant-based competition and tighter environmental rules would squeeze dairy profitability.
What The Results Changed For The Saputo Debate
The biggest shift came from Saputo selling an 80% stake in its Argentina division and agreeing to sell its UK dairy arm for about £988 million. That supported the bullish focus on a slimmer, higher returning portfolio. Measured results also leaned that way. Q1 2027 revenue moved to CA$4,421 million, profit rose to CA$183 million and net margin edged up to 4.1% from 3.6%, so the evidence supported the optimistic case without fully closing the argument.
The lesson to apply elsewhere is clear. When a thesis rests on better profitability rather than just sales, track divestments and segment exits alongside net margin in the results. That is how to test whether a promised shift to higher quality earnings is actually unfolding.
What Saputo's Recent Gain Already Prices In
With Saputo now at CA$40.32 after a 21.4% gain over the past year, the selected Narrative still places its Fair Value above that level rather than below it. That view leans on mix, efficiency and capital returns instead of assuming broad dairy demand will do the heavy lifting.
For a buyer today, the key question is whether Saputo can keep shifting more volume into higher value ingredients and sustain the higher EBITDA margins that the Narrative treats as achievable and durable.
"Higher capital expenditure in fiscal 2027 of about $515 million to $550 million aimed at high protein ingredients, cultured products, value-added beverages and network efficiency creates room for Saputo to shift more volume into products that typically carry richer unit economics, which can influence revenue growth and EBITDA margin mix."
One Narrative disagrees with today's price. → See where this Narrative says Saputo should trade
Where Saputo’s Shelf Space Leads
Saputo keeps your fridge stocked with everyday staples. Nearby, another business quietly competes for the same baskets.
Instead of milk and mozzarella, it leans on condiments, packaged meals and durable pantry fixtures that encourage repeat habits.
It still focuses on inflation, brand investment and execution, while treating steady cash generation and a maintained payout as essential priorities.
Where Saputo trims and refocuses, this peer channels more into marketing, product refreshes and debt discipline.
If shoppers keep choosing familiar labels, that quieter pantry work could end up mattering far more than it sounds.
That argument has a Narrative and a number behind it. → See the company one Narrative values 44% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com