


Trane Technologies stock just took a hit. Shares closed on Friday at about US$409.85, almost 5% lower on the day and down roughly 10% over the past month. That is a sharp reaction for an industrials heavyweight on the back of a single earnings print.
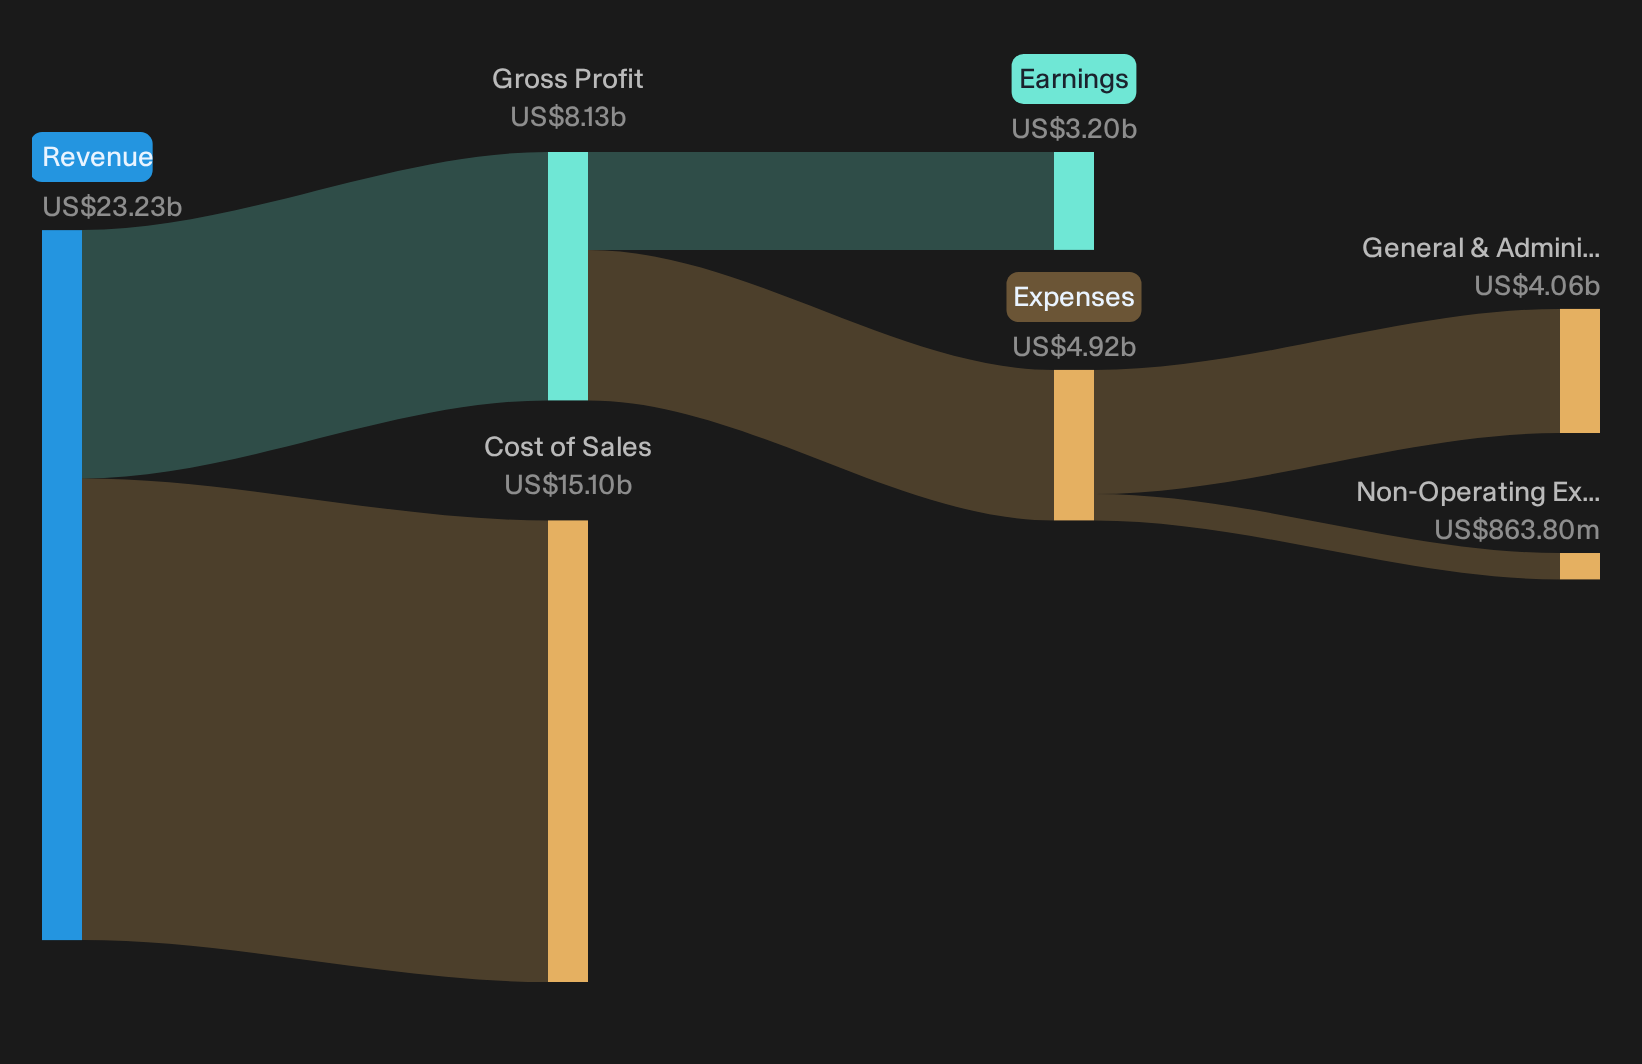
The third quarter of 2026 hardly looked like a collapse. Basic earnings per share reached about US$4.79 on revenue of roughly US$6.76b, with net income from ongoing operations near US$1.06b. The real story sits in the longer arc, where a high quality profit profile meets a premium P/E multiple and a valuation debate that stretches well beyond this week’s chart.
Love Trane Technologies’ earnings strength but uneasy about paying up for a premium P/E multiple after a sharp pullback? Consider benchmarking it against our 29 high quality undervalued stocks for alternatives that pair solid fundamentals with more conservative pricing.
Q3 2026 Trane Technologies Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$6,759.7m vs. US$5,742.5m (up about 17.7%)
- Net Income from Ongoing Operations (Q3 2026 vs. Q3 2025): US$1,060.1m vs. US$857.0m (up about 23.7%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$4.79 vs. US$3.85 (up about 24.4%)
- Trailing 12-Month Net Profit Margin (Q3 2026 vs. Prior Year): 13.8% vs. 14.0% (margin slightly lower year on year)
Earnings tell you what Trane Technologies put on the scoreboard this quarter, but cash flows show you the money that actually moves through the business and underpins any valuation work.
Look at Trane Technologies' cash flows in isolation and the stock could be a meaningful 20% undervalued.
Evaluating Trane Technologies’ Backlog And Services Story
The bullish story leans heavily on Trane Technologies turning a large backlog and services footprint into a more recurring, higher margin model.
"Continued execution on data center cooling, modular chiller plants, connected building services and electrified heating and transport needs to hold together as a single growth engine that keeps Trane’s mix shifting toward higher-value, recurring solutions."
Q3 moves this idea from slideware to evidence. Applied Solutions revenue grew more than 60%, Stellar is tracking to about US$500m run rate in 2026, services delivered roughly 10% growth in the Americas, and backlog reached US$12.5b with more than US$8b booked for 2027 and beyond.
The price and this Narrative do not agree. → Uncover what this Narrative says Trane Technologies is actually worth.
Trane Technologies: Strong Quarter, But Pricing Leverage Looks Thin
Bears worry that Trane Technologies’ services and software carry rising complexity that erodes the margin upside story.
"While connected buildings, BrainBox enabled controls and high value services are growing as a share of Trane Technologies revenue, higher compliance requirements and the need for continued digital investment could outpace the company’s ability to price for this complexity."
Q3 does not knock out that concern. Services in the Americas grew about 10%, yet management cut full year price realization to roughly 1% and trimmed expected organic operating leverage to the low 20s. Inflation and supply strain are still biting. The margin benefit from richer mix is not fully visible yet.
Hunt For Mispriced Earnings Power
Trane Technologies recently highlighted how resilient earnings can still meet valuation concerns. The real opportunity could sit in stocks where fundamentals improve before valuations fully reflect that change.
- Company 1 - 35% below our estimate - supplies accelerated computing racks when power limits constrain hyperscale data center expansion.
- Company 2 - 42% below our estimate - packages higher margin data center building block systems as buyers favor turnkey AI infrastructure orders.
- Company 3 - 20% below our estimate - grows a payments account and card ecosystem capturing more fee and interest income per active customer.
That is three of the list. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com