


Essex Property Trust came into this Q3 2026 report with a mixed story in the market. The share price has drifted lower over the last week and month, and it slipped another 0.4% today. Yet the fresh numbers tell a firmer tale. Core funds from operations, the key profit yardstick for apartment real estate investment trusts, landed at about US$265 million. Same property revenue for the quarter reached roughly US$502 million. The gap that matters now is not between quarters; it is between a soft share price and a business still generating solid recurring cash flow.
Love the solid recurring cash flow at Essex Property Trust, but uneasy about the recent share price drift. Check out our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
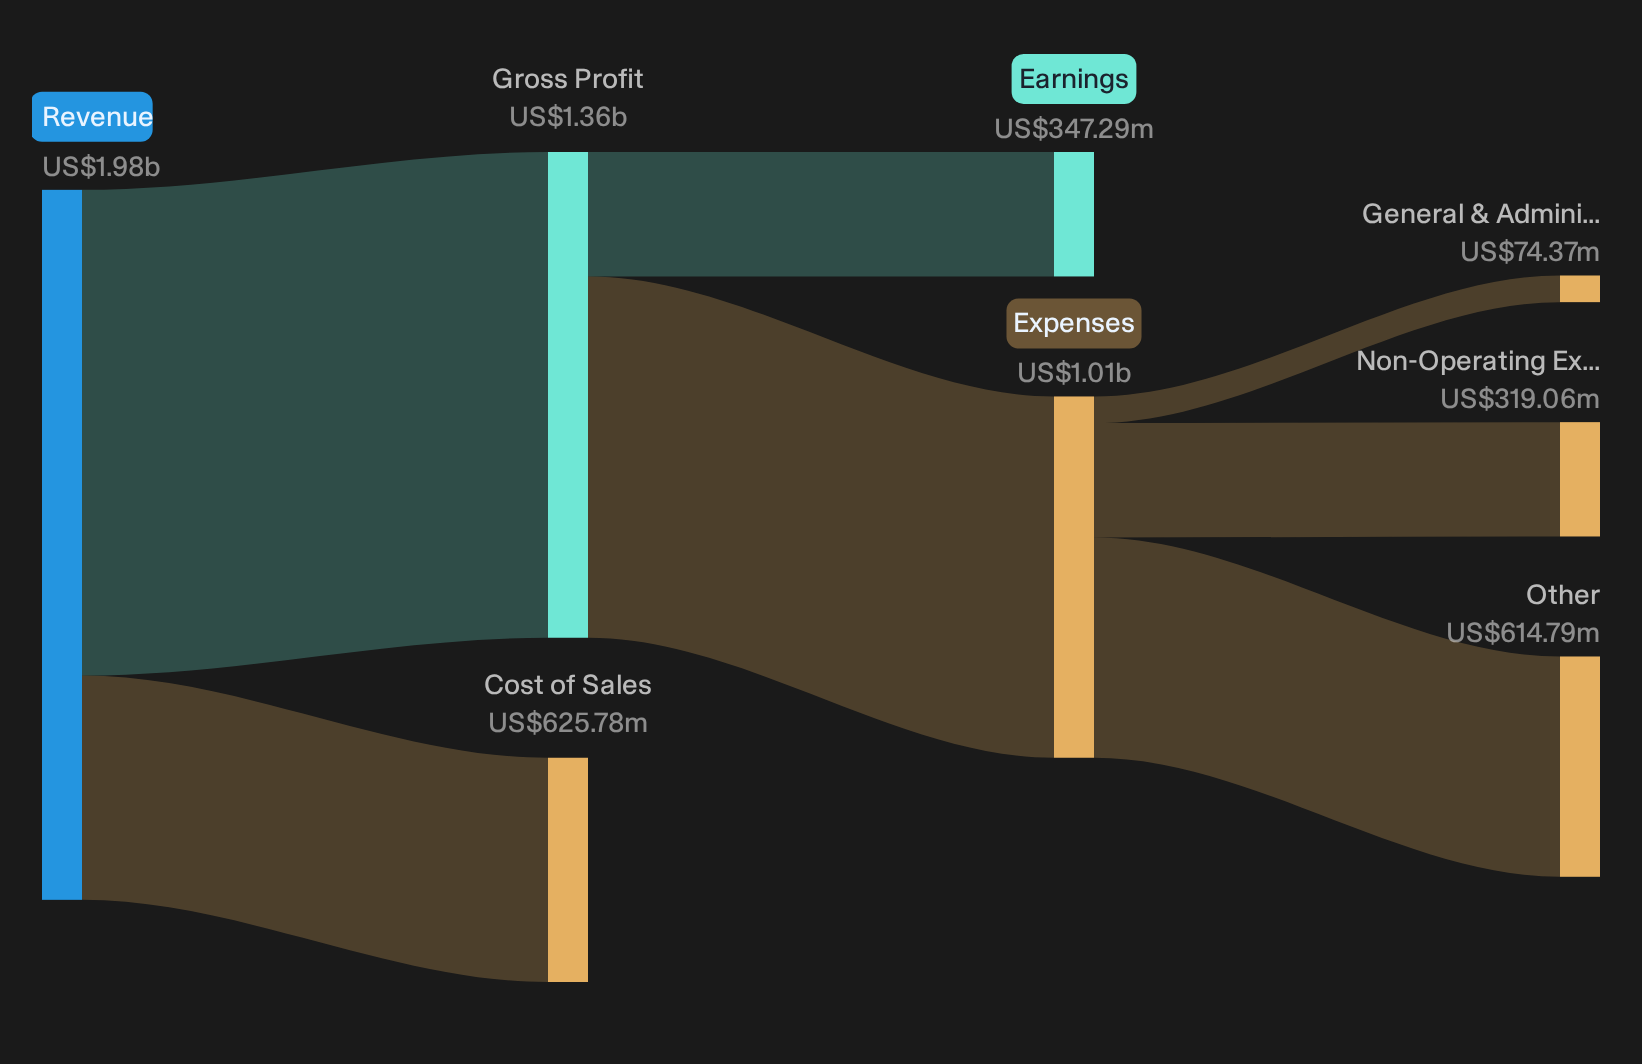
- Total Revenue (Q3 2026 vs. Q3 2025): US$501.9 million vs. US$491.1 million (modest increase)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$98.1 million vs. US$164.6 million (sharp decline)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.53 vs. US$2.56 (material drop)
- Funds From Operations (FFO) (Q3 2026 vs. Q3 2025): US$264.7 million vs. US$268.7 million (slight decline)
Earnings tell part of the story for Essex Property Trust, but investors who care about what they are actually paying for often focus on the cash flowing through the business instead of just the quarterly headline.
On Essex Property Trust's latest cash flows alone, the stock could be a dramatic 31% undervalued.
Essex bull case: Northern California and buybacks under the microscope
Supporters argue Essex Property Trust can lean on tech heavy markets and disciplined capital deployment to keep cash flows resilient.
"AI and broader technology sector expansion in Northern California, reflected in stronger job postings, company formation, office leasing and wage growth, is supporting 6.5% blended rent growth with high occupancy in that region and is positioned to influence future revenue and earnings power."
The latest quarter largely lines up with that ambition. Northern California delivered 7.3% blended rent growth and effectively no concessions, driving the raise in same property revenue and NOI guidance. Core FFO per share was US$4.00 and topped internal guidance by US$0.01, helped by this regional strength and supported by ongoing buybacks and selective acquisitions.
Essex bear case: concentration, SoCal softness and rate pressure
On the flip side, critics worry that the same geographic and rate exposures could dull that edge if local conditions stay uneven.
"Southern California is currently much softer than Northern California, with blended rent growth of 1.4% and Los Angeles still showing rent delinquencies of about 1.5% alongside extended 4 to 5 month eviction timelines, which could keep regional net operating income and portfolio wide net margins under pressure if this gap does not close."
Q3 did not fully erase that concern. Southern California blended rent growth was about 0.9% and still trails Northern California and Seattle. Net income excluding extra items fell from US$164.6m to US$98.1m and basic EPS declined, while FFO was slightly lower year on year. Higher hedged interest costs in joint ventures also point to rate pressure starting to show up in earnings quality.
One Narrative disagrees with today's price. → See where this Narrative says Essex Property Trust should trade.
Hunt For Mispriced Cash Generators
Essex Property Trust illustrates how share prices and operating cash flows can separate over long periods. The real opportunity is finding stocks that could be undervalued before the market adjusts them.
- Company 1 - 27% below our estimate - convert rising demand for grid diagnostics and aerospace testing equipment into higher margin recurring projects as integrations mature.
- Company 2 - 29% below our estimate - compound value as customers adopt a low cost mobile platform for everyday banking, cards and credit.
- Company 3 - 38% below our estimate - extend a previously niche drink into mainstream shelves while scaling private label contracts that meet coconut water demand.
That is three of the list. See every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com