


Saia stock barely budged after Q3 2026 earnings, ticking up about 0.5% to US$344.66. On the surface that muted move suggests a routine quarter. The headline is sharper than that. The less than 1% trailing net margin compression to 8% now collides with a rich 32.4x P/E and a discounted cash flow estimate that sits far below the current share price.
Short term traders may see a steady chart. Longer term holders have a tougher question. The business is expected to grow earnings faster than revenue while carrying a valuation and margin profile that now pull in opposite directions.
If you like Saia's earnings growth profile but are uneasy with an 8% net margin paired with a 32.4x P/E and a rich DCF gap, check out our 29 high quality undervalued stocks to find businesses with stronger valuation support to benchmark against Saia.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$982.454 million vs. US$839.644 million (up roughly 17%)
- Net Income (Q3 2026 vs Q3 2025): US$91.445 million vs. US$86.316 million (up about 6%)
- Basic EPS (Q3 2026 vs Q3 2025): US$3.41 vs. US$3.23 (up around 6%)
- Trailing Net Profit Margin (Last 12 Months vs Prior Year): 8% vs. 8.8% (margin compressed by 0.8 percentage points)
Prefer clean, visual charts instead of a dense wall of earnings tables and footnotes? See Saia's full valuation picture presented in a single visual dashboard through our company report for Saia.
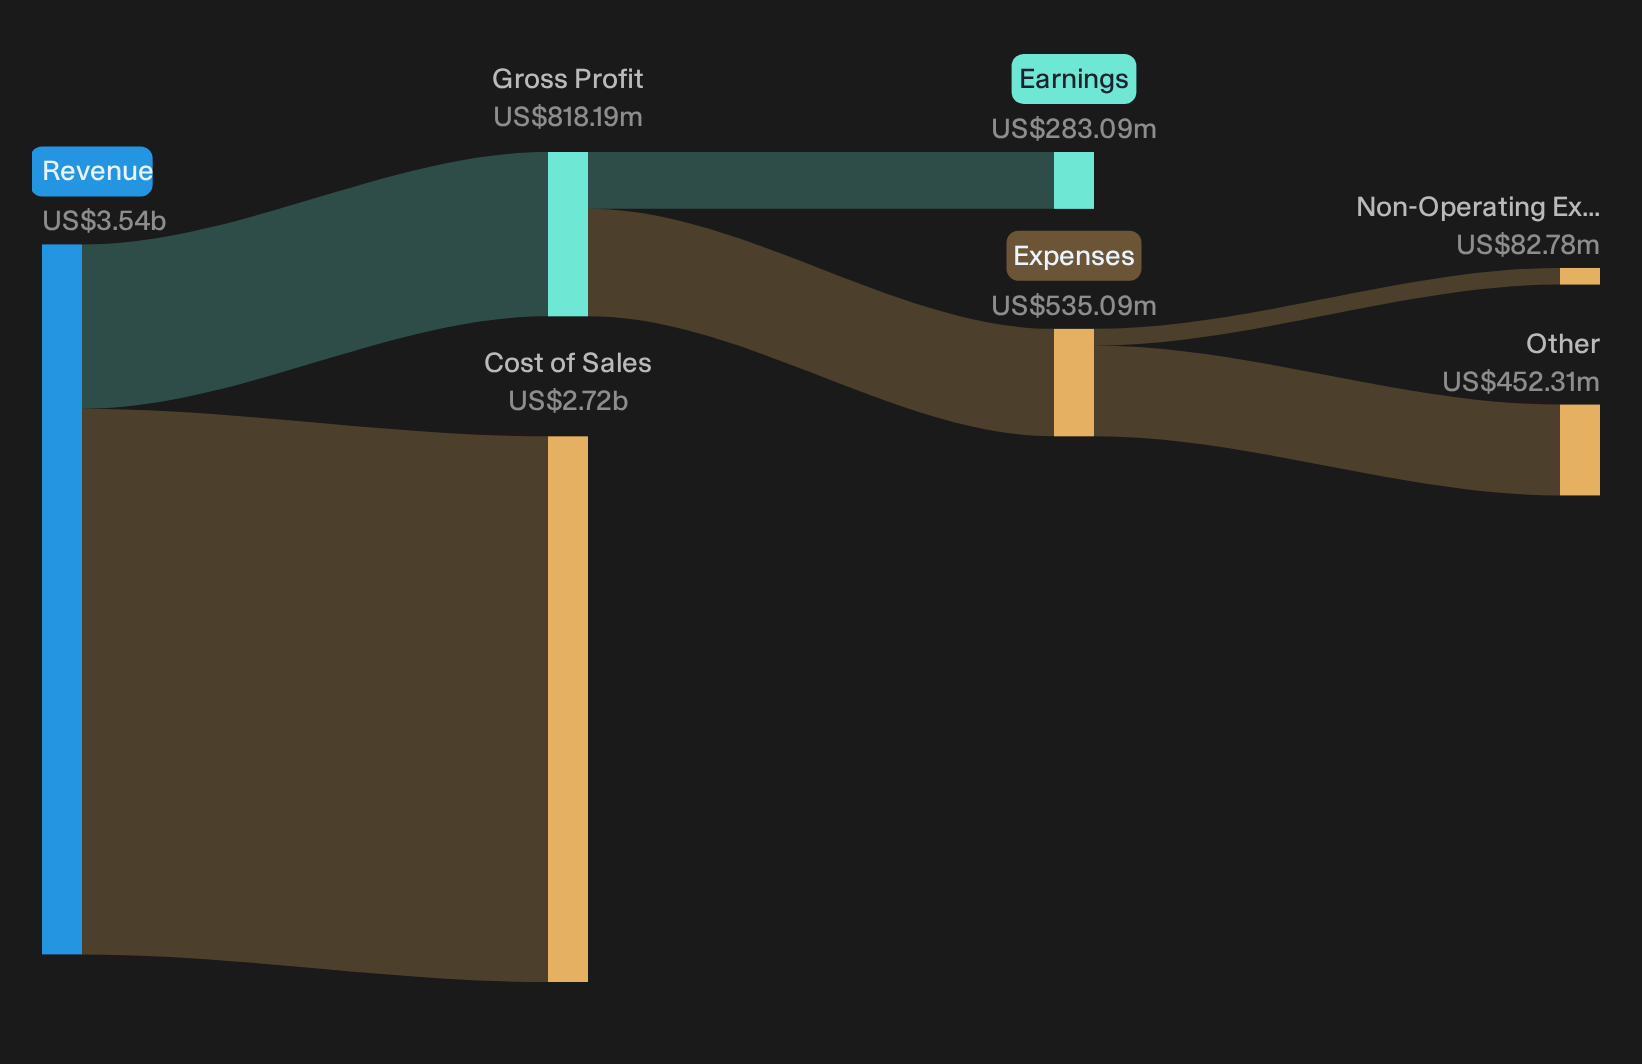
Saia’s Pricing Thesis Meets Real Volume Milestones
Bulls argue Saia can turn better service and tech into pricing that outpaces rising costs. That idea now has real checkpoints in the latest quarter.
"The main thing that has to go right is that Saia continues to use service quality, safety gains and technology upgrades like Saia REV to support yield that stays ahead of rising wages, fuel, claims and purchased transportation costs."
Q3 backs parts of that claim. Revenue rose 17% to US$982.5m with firm pricing, as a 7.1% general rate increase and 10.8% contract renewals held through strong tonnage. Operating ratio stayed at 87.6% while the terminal count expanded to 45 new sites, suggesting early leverage from the enlarged network and Saia REV transit time changes rather than pure cost drag.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Saia Cost Fears Meet A Still Tight Margin
Bears worry Saia’s higher fuel, wages, insurance, and outsourced miles harden into a ceiling on profitability when demand eventually cools.
"While the expanded terminal footprint is now generating profitable ramping sites and management points to scale benefits, the decision to lower the full year 2026 margin outlook to the bottom of the prior improvement range signals that start up costs and underabsorbed overhead from rapid build out may persist longer than expected and could limit operating leverage and return on more than US$2b of recent capex."
Q3 shows that concern is not resolved. Operating ratio held at 87.6% despite record revenue and 45 new terminals, and trailing net margin slipped to 8%. That combination points to real volume and pricing momentum, but also to limited incremental efficiency so far.
Hunt For Mispriced Earnings Power
Saia just showed how a healthy earnings story can appear beside a stretched valuation. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 21% below our estimate - expand advanced optical manufacturing to handle higher value packaging for AI and telecom demand.
- Company 2 - 41% below our estimate - grow rental mat fleets that support long duration utility and critical infrastructure construction and maintenance.
- Company 3 - 29% below our estimate - scale a low cost digital banking platform that adds customers and lifts revenue per active account.
Three companies from the same screener. Open all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com