


Ameriprise Financial came into this Q3 2026 report with its stock drifting, down about 10% over the past three months and another 1.3% today to roughly US$491. For a company often viewed as a high return, advice led wealth and asset manager, that muted reaction sits awkwardly against what the quarter actually delivered.
The fresh numbers show adjusted operating earnings power front and center. Adjusted operating net revenues reached about US$5.1b and adjusted operating earnings per share hit roughly US$12.47, while return on equity ex unlocking ran above 56%. That combination is the real headline and sets up a very different conversation than a routine 1 day pullback suggests.
Love Ameriprise Financial's earnings power and 56% adjusted ROE but want a broader set of rock solid balance sheets to compare it against? Scan through the list of solid balance sheet and fundamentals stocks (25 results)
Q3 2026 Earnings Summary
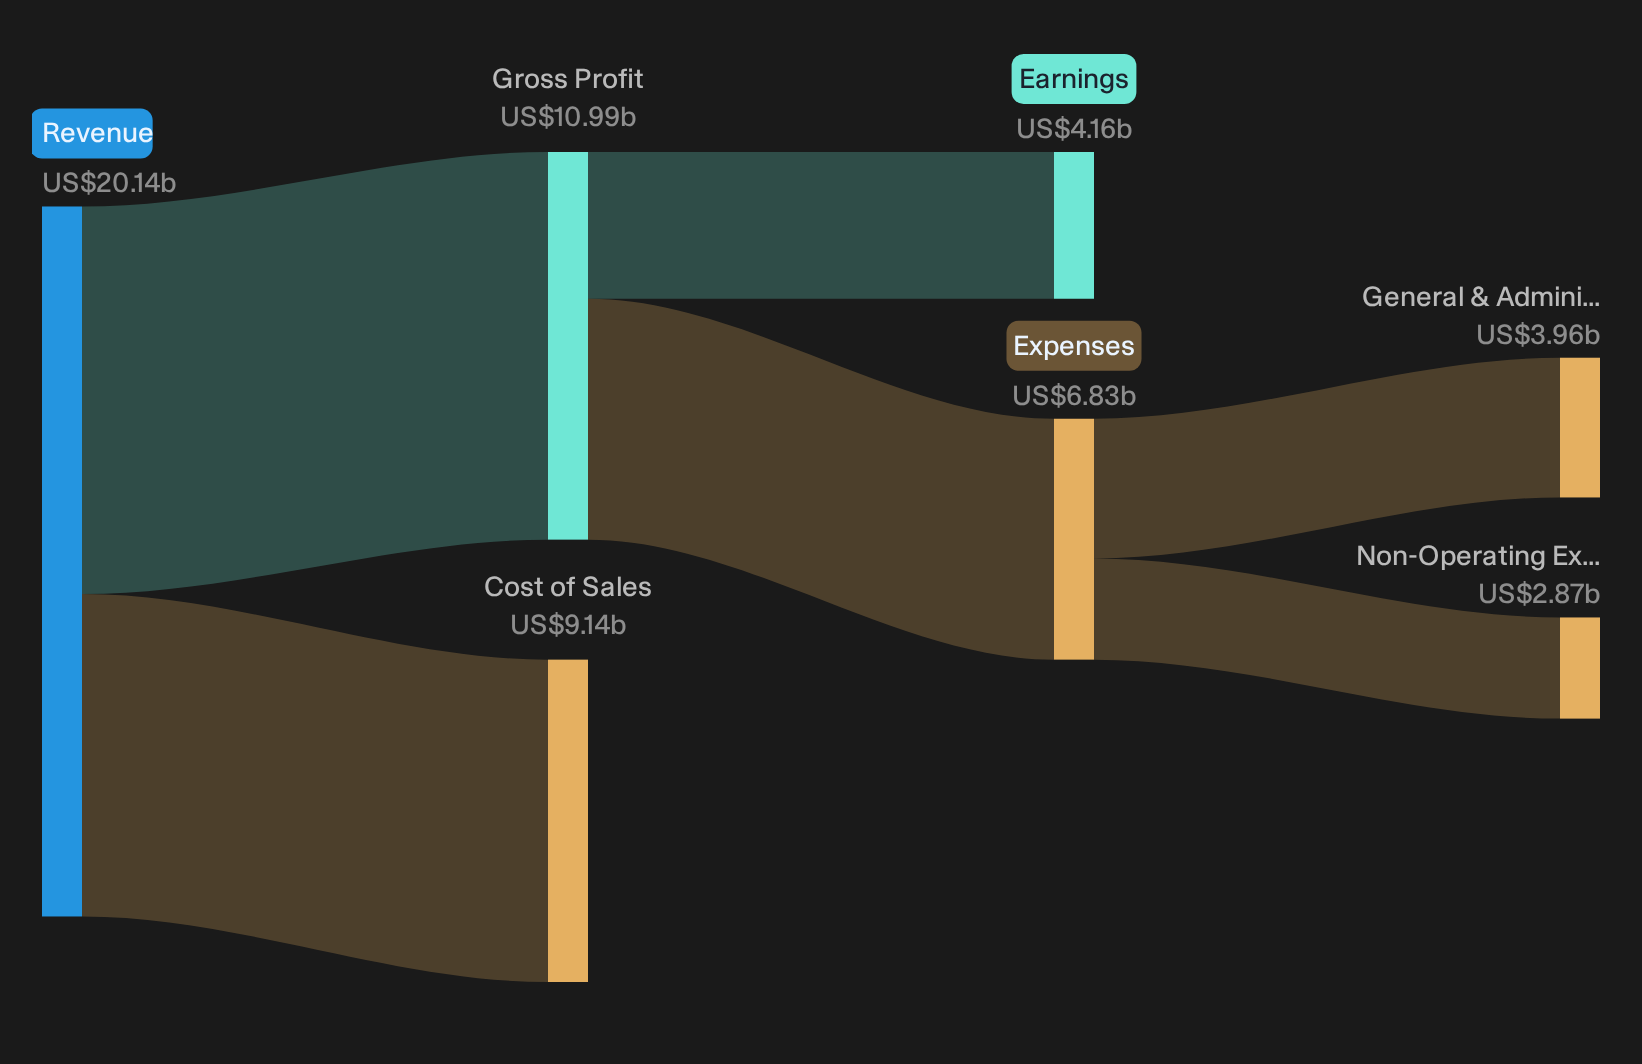
- Revenue (Q3 2026 vs Q3 2025): US$5,191m vs. US$4,893m (up about 6.1%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$1,126m vs. US$912m (up about 23.5%)
- Basic EPS (Q3 2026 vs Q3 2025): US$12.47 vs. US$9.47 (up about 31.7%)
- Assets Under Management and Administration, AUMA (Q3 2026 vs Q3 2025): US$1.8b vs. US$1.325b (very large percentage increase, driven by higher client assets and flows across Ameriprise Financial platforms)
Ameriprise just posted a 56% adjusted ROE this quarter. Ask Charlie what makes Ameriprise’s 56% ROE look durable.
Ameriprise bullish story: productivity promises meet hard numbers
The optimistic view hangs on AI tools turning Ameriprise into a higher output advice machine, not just a bigger one.
"Ameriprise Financial’s embedded AI tools across eMeeting, meeting summaries and Copilot Premium are expected to keep lifting adviser productivity beyond the roughly 30 weekly hours of potential time savings already identified, which could support higher revenue per adviser and operating margins in Advice & Wealth Management."
Q3 results lean in that direction. Revenue per advisor reached about US$1.2m, up 13%, and client satisfaction stayed high at 4.9 out of 5. Advice & Wealth margins held around 29%. Those are the kind of productivity and quality markers this thesis demands.
Ameriprise bear case: advisor and asset leaks under the microscope
The cautious camp worries that advisor churn and lost mandates quietly chip away at Ameriprise even while earnings look strong.
"Ameriprise Financial is already seeing pressure on Advice & Wealth Management net client flows from an extremely aggressive recruiting and retention environment. Further adviser turnover, such as the departure of an advisory team with about US$8.1b of client assets, could weigh on revenue growth and compress earnings if higher transition support or retention costs are required."
This quarter, AUMA reached roughly US$1.8t, up 8%, with Advice & Wealth assets at about US$1.2t and wrap balances at US$729b. Ameriprise added 79 experienced advisers plus Huntington’s 260 advisers and US$28b of assets. Aggressive recruiting and institutional deals are offsetting attrition for now, though retention incentives still threaten future margins.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt For Mispriced Earnings Power
Ameriprise Financial just showed how reported progress can coincide with a muted share price. The real opportunity is in stocks that could be undervalued before the market reassesses them.
- Company 1 - 34% below our estimate - turns optical and solar supply agreements and customer prepayments into a larger, higher margin manufacturing program.
- Company 2 - 19% below our estimate - builds a teahouse network where overseas locations and membership programs steadily lift franchise economics and transaction volumes.
- Company 3 - 21% below our estimate - adds manufacturing capacity for high value photonics packaging as hyperscaler and telecom workloads depend more on custom optical components.
That is three of the list. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com