


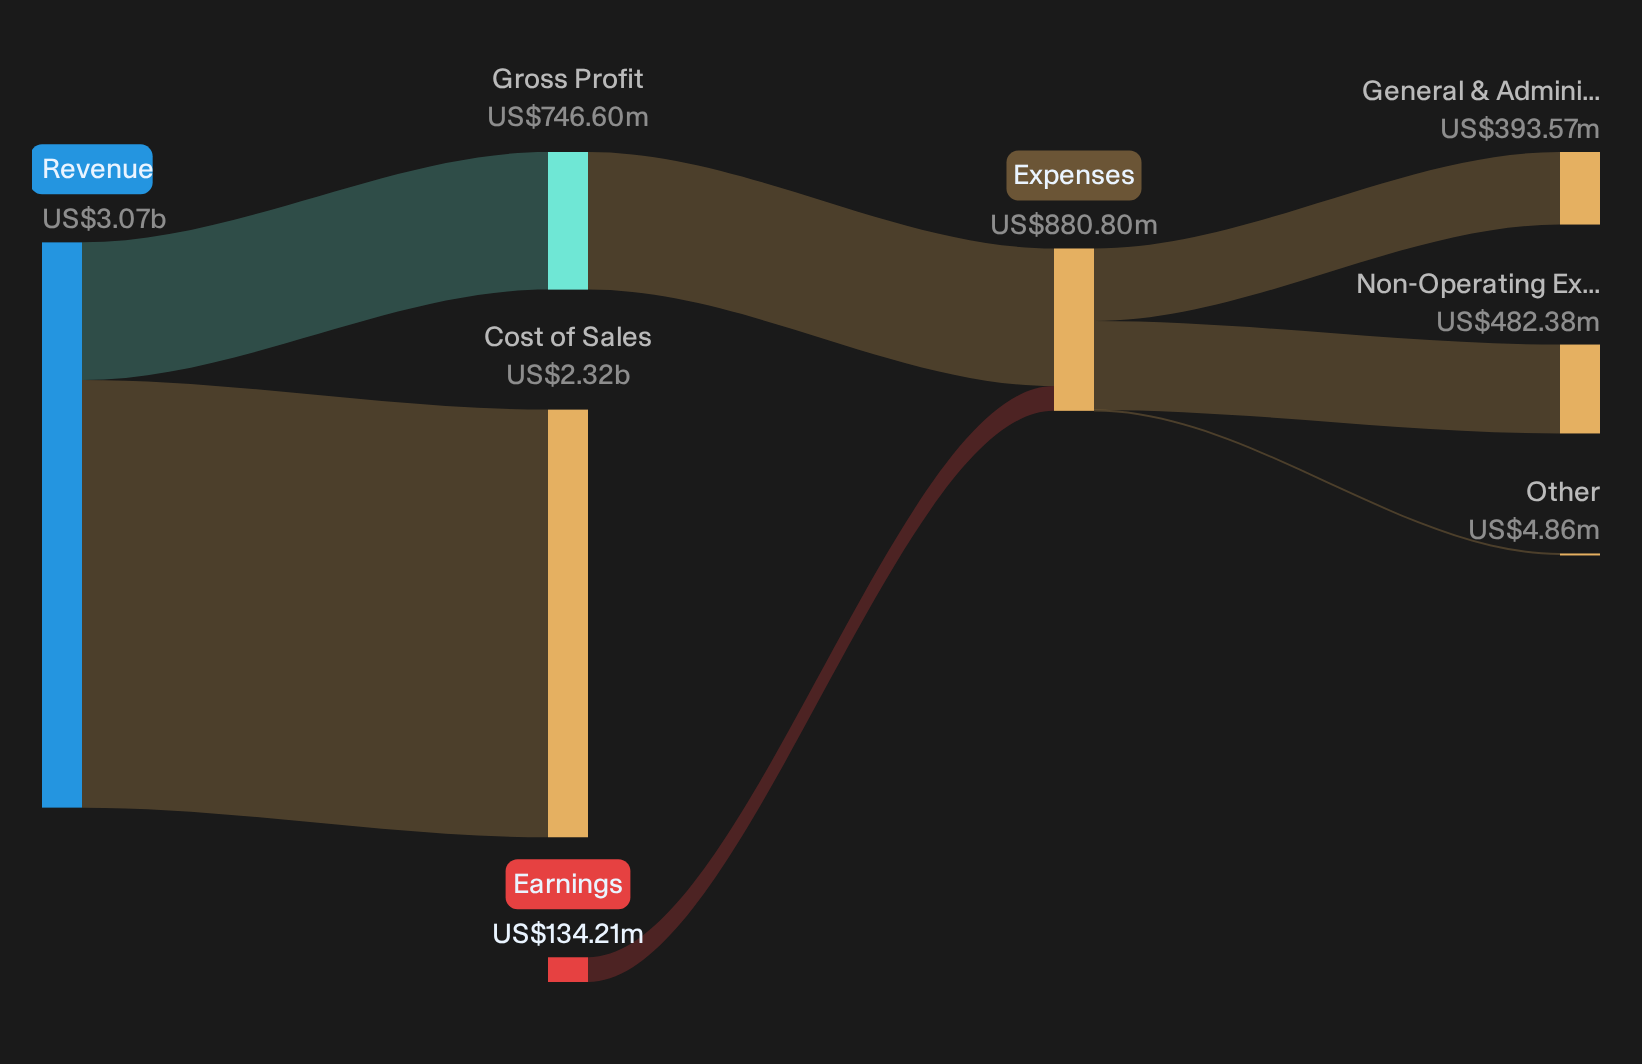
Bright Horizons Family Solutions came into this Q3 2026 report as a long term childcare compounder story, yet the reaction was brutal. The stock dropped about 18% today, wiping away weeks of quiet rebuilding in a single session. That selloff clashes with the headline print. Revenue reached US$841.5m and adjusted earnings per share landed at US$1.80, supported by a strong quarter in Back Up Care.
The reality check came from profitability quality. Bright Horizons booked a reported net loss of US$230.7m in Q3, driven by a large non cash impairment tied to its international Full Service unit. For investors, the gap between healthy underlying demand and a heavy write down is what now frames the debate.
Love the steady underlying demand story at Bright Horizons Family Solutions but uneasy about a heavy impairment hitting reported profit? Consider screening for childcare and education peers with cleaner balance sheets and steadier earnings profiles using our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$841.5m vs. US$802.8m (up about 5%)
- Net Income/Loss (Q3 2026 vs. Q3 2025): loss of US$230.7m vs. profit of US$78.6m (swung to a sizable loss driven by impairment)
- Basic EPS (Q3 2026 vs. Q3 2025): loss of US$4.76 per share vs. earnings of US$1.38 per share (moved sharply into the red)
- Back-Up Care Adjusted Operating Margin (Q3 2026 vs. Full-Year 2026 Outlook): about 35% in Q3 compared with a full-year expectation of 28% to 30% (seasonally strong quarter relative to the projected annual range)
Tired of slogging through earnings tables and impairment footnotes to make sense of Bright Horizons Family Solutions? Get the full story in one visual dashboard, with a clear view of its valuation picture through the company report for Bright Horizons Family Solutions..
Bright Horizons Bull Case: Back-Up Care Delivers, Portfolio Lags
The optimistic view hangs on Bright Horizons Family Solutions deepening employer relationships across services and letting Back Up Care carry more of the earnings load.
"Bullish analysts expect Bright Horizons Family Solutions to continue scaling employer relationships across full-service childcare, Back-Up Care, and education services, while using closures and mix shifts to focus on higher quality centers."
Back Up Care is doing its part, with Q3 revenue up 13% and segment margins around 35% in a seasonally strong period, and full year growth still pegged near 13%. That is tangible progress toward the multi service thesis. Full Service tells a different story. Revenue grew only 1.3%, adjusted margin was 3.7%, and center closures plus Australia weakness show the portfolio upgrade is still very much in progress and not yet a completed milestone.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Bright Horizons Bear View: Affordability And Execution Bite
Bearish research argued that Bright Horizons could see solid interest from parents yet struggle to turn that into healthy, profitable growth if affordability and execution slipped.
"Even where demand for care is described as strong, they flag affordability and availability as twin constraints that could weigh on utilization and revenue growth for Bright Horizons."
This quarter supports that concern. Full Service revenue moved only slightly, enrollment in mature centers softened, the U.K. regulator notice hit new family starts, and Australia required a large impairment. Management also cut full-year guidance. Back Up Care is strong, but it is not fully offsetting these missed milestones yet.
Use This Selloff To Hunt Dislocations
Bright Horizons Family Solutions just showed how an impairment charge can overshadow an otherwise solid operating performance. The real opportunity could be identifying stocks that appear mispriced before sentiment adjusts to new information.
- Company 1 - 31% below our estimate - partners with leading AI providers to shift intensive training workloads onto expanding high performance cloud clusters.
- Company 2 - 20% below our estimate - grows payment accounts and white label partnerships that route more transactions through its low cost cross border network.
- Company 3 - 38% below our estimate - expands device trade in programs supported by subsidies that channel higher quality used phones into its refurbishment pipeline.
That is three of the list. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com