


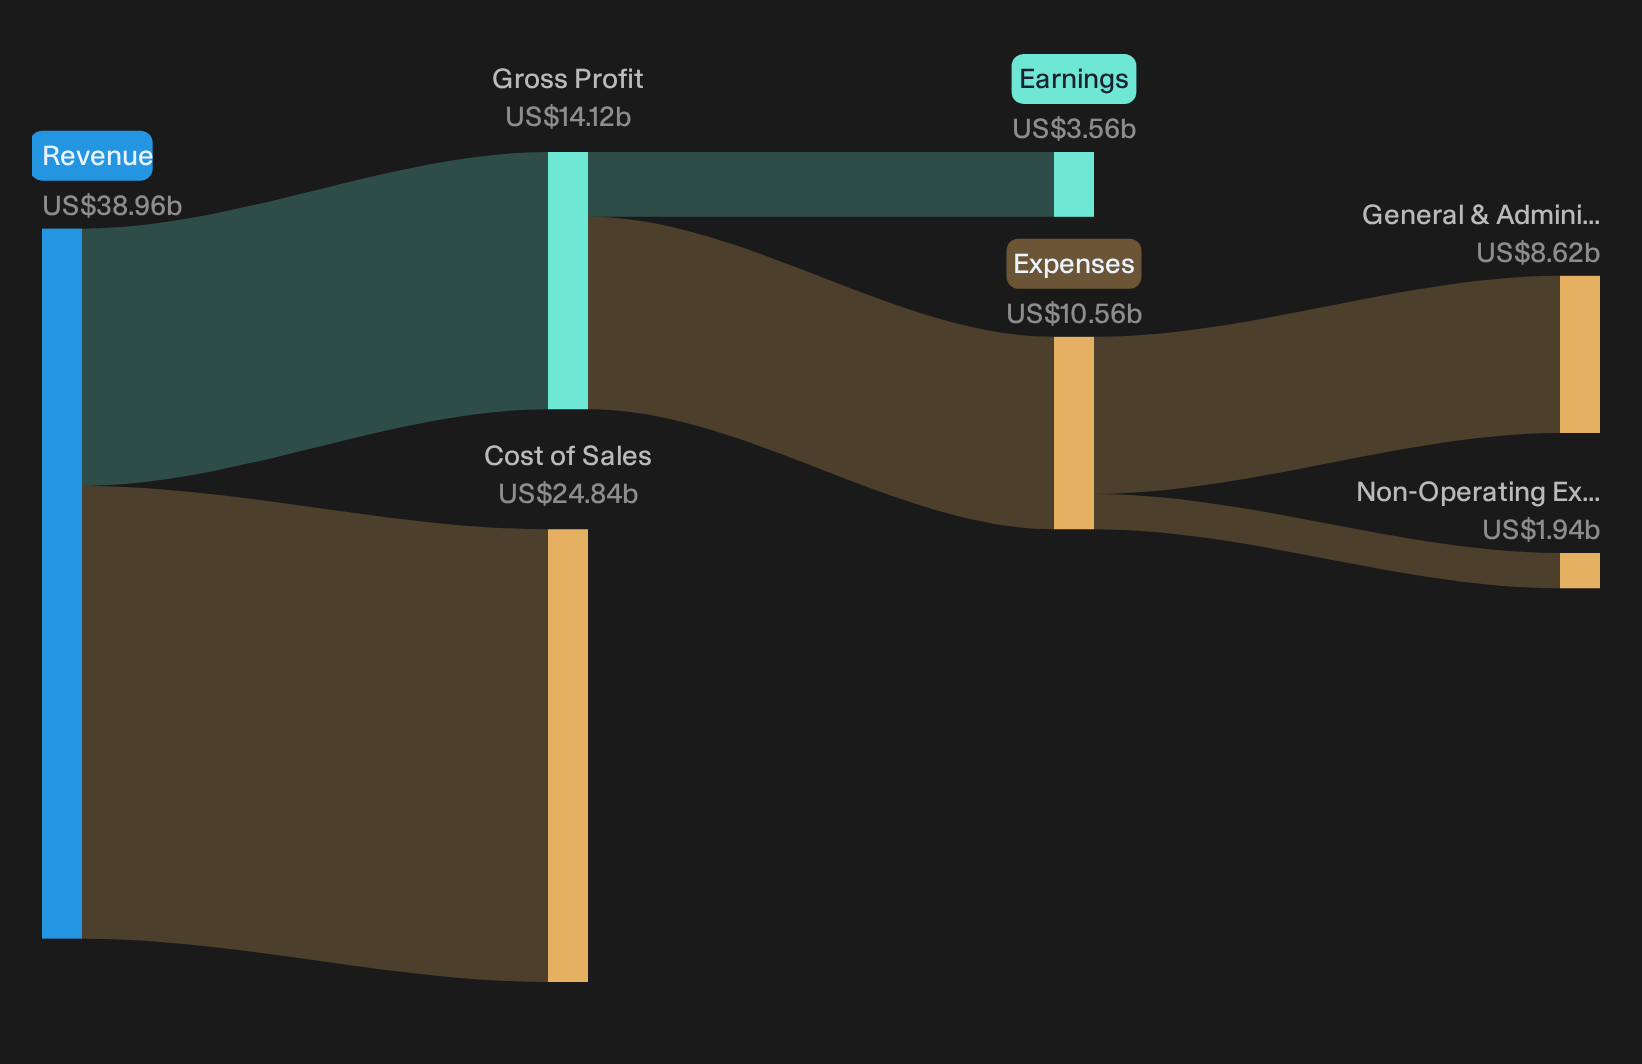
CRH came into this earnings day with a construction heavyweight reputation and a stock that has barely moved, up just 0.2% to about $90.81, despite a solid multi‑month run. The headline from Q3 2026 is simple: Revenue reached about $11.4b and profitability held its ground, yet the share price barely flinched.
For a materials giant often sold on its long game, that tiny one day reaction sits awkwardly against the real story in these numbers. The key tension is margin and profit pressure, with earnings per share at $1.87 and net income of $1.25b now under far closer scrutiny.
Love CRH's scale and stable Q3 headline numbers but worried about profit pressure at the earnings line? Benchmark it against our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$11.396b vs. US$11.069b (up about 3%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$1.245b vs. US$1.496b (down about 17%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.87 vs. US$2.23 (down about 16%)
- Adjusted EBITDA Margin (Q3 2026 vs. Q3 2025): roughly 24% vs. roughly 24% (broadly flat, with higher energy and haulage costs weighing on profitability)
Earnings are one thing, but investors who care about what CRH is really generating over time tend to focus on cash flows. If you look at CRH's cash flows alone, the stock could be a notable 21% undervalued.
CRH bull case: infrastructure anchor vs earnings drag
The bullish pitch says CRH’s future rests on long funded infrastructure and reindustrialization projects, not short term housing swings.
"Analysts expect CRH to keep growing around federally and state-funded infrastructure and reindustrialization projects, with recent results and guidance indicating the business is increasingly anchored in these long-duration demand pools."
Q3 revenue of US$11.4b and roughly flat adjusted EBITDA margin near 24% back that view. Americas Materials volumes in aggregates rose while International Solutions margins improved by 110 bps. Guidance for 2026 EBITDA of US$7.8 to 8.0b and management’s focus on transport, grid and data centers show the long pipeline is translating into current backlog and stable profitability.
CRH bear case: acquisition risk meets margin pressure
The bear story says the acquisition machine must convert into real cash, not just bigger footprints and higher leverage.
"The main thing that has to go right is that CRH continues to execute its aggregates-led acquisition and integration program, including Arcosa and Axius Water, so that expected scale benefits and margin improvements show up in cash generation over time."
Q3 tells a mixed story. Arcosa is now closed and Nordic aggregates deals advance the plan, yet group net income excluding extra items fell about 17% and basic EPS declined roughly 16% year on year. Higher energy and haulage costs squeezed profitability and consensus earnings were missed, so the integration narrative now has more to prove before investors will credit full synergy targets.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt Quiet Disconnects In Plain Sight
CRH just showed how steady numbers can still leave the share price barely moving. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 38% below our estimate - use power systems demand and new engine capacity to expand long-duration data center supply arrangements.
- Company 2 - 46% below our estimate - scale storage and inverter offerings so higher margin equipment supports a backlog of delayed energy projects.
- Company 3 - 27% below our estimate - convert grid modernization and aerospace testing needs into higher value diagnostic systems after a major acquisition.
That is three of the list. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com