


Schneider National just posted Q3 2026 results and the first read from the market was muted. The stock slipped about 1% over the last session, after already falling over the past month and quarter, even as the company reported solid profit improvement in a still tough freight cycle.
The headline is margin repair. Adjusted income from operations reached US$63.8 million on roughly US$1.35 billion of enterprise revenue, with adjusted earnings per share at US$0.29. For a trucking and intermodal carrier that has been navigating a slow recovery, this kind of operating ratio progress appears more significant than the small one-day price dip.
Like the operational progress at Schneider National but wary of a freight cycle that still feels sluggish? Look at the list of solid balance sheet and fundamentals stocks (25 results) to compare SNDR against peers that pair disciplined operations with sturdier fundamentals.
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs Q3 2025): US$1,585.3 million vs. US$1,452.4 million (up about 9%)
- Net Income, Excluding Extra Items (Q3 2026 vs Q3 2025): US$49.5 million vs. US$19.4 million (up about 155%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.28 vs. US$0.11 (up about 154%)
- Adjusted Operating Ratio, Enterprise level (Q3 2026 vs Q3 2025): 95.3% vs. roughly 97.0% (improved by about 170 basis points)
Tired of scrolling through walls of earnings tables and freight metrics to figure out what really changed at Schneider National this quarter? Get the full visual picture of the business, along with a clear view of its valuation in our company report for Schneider National.
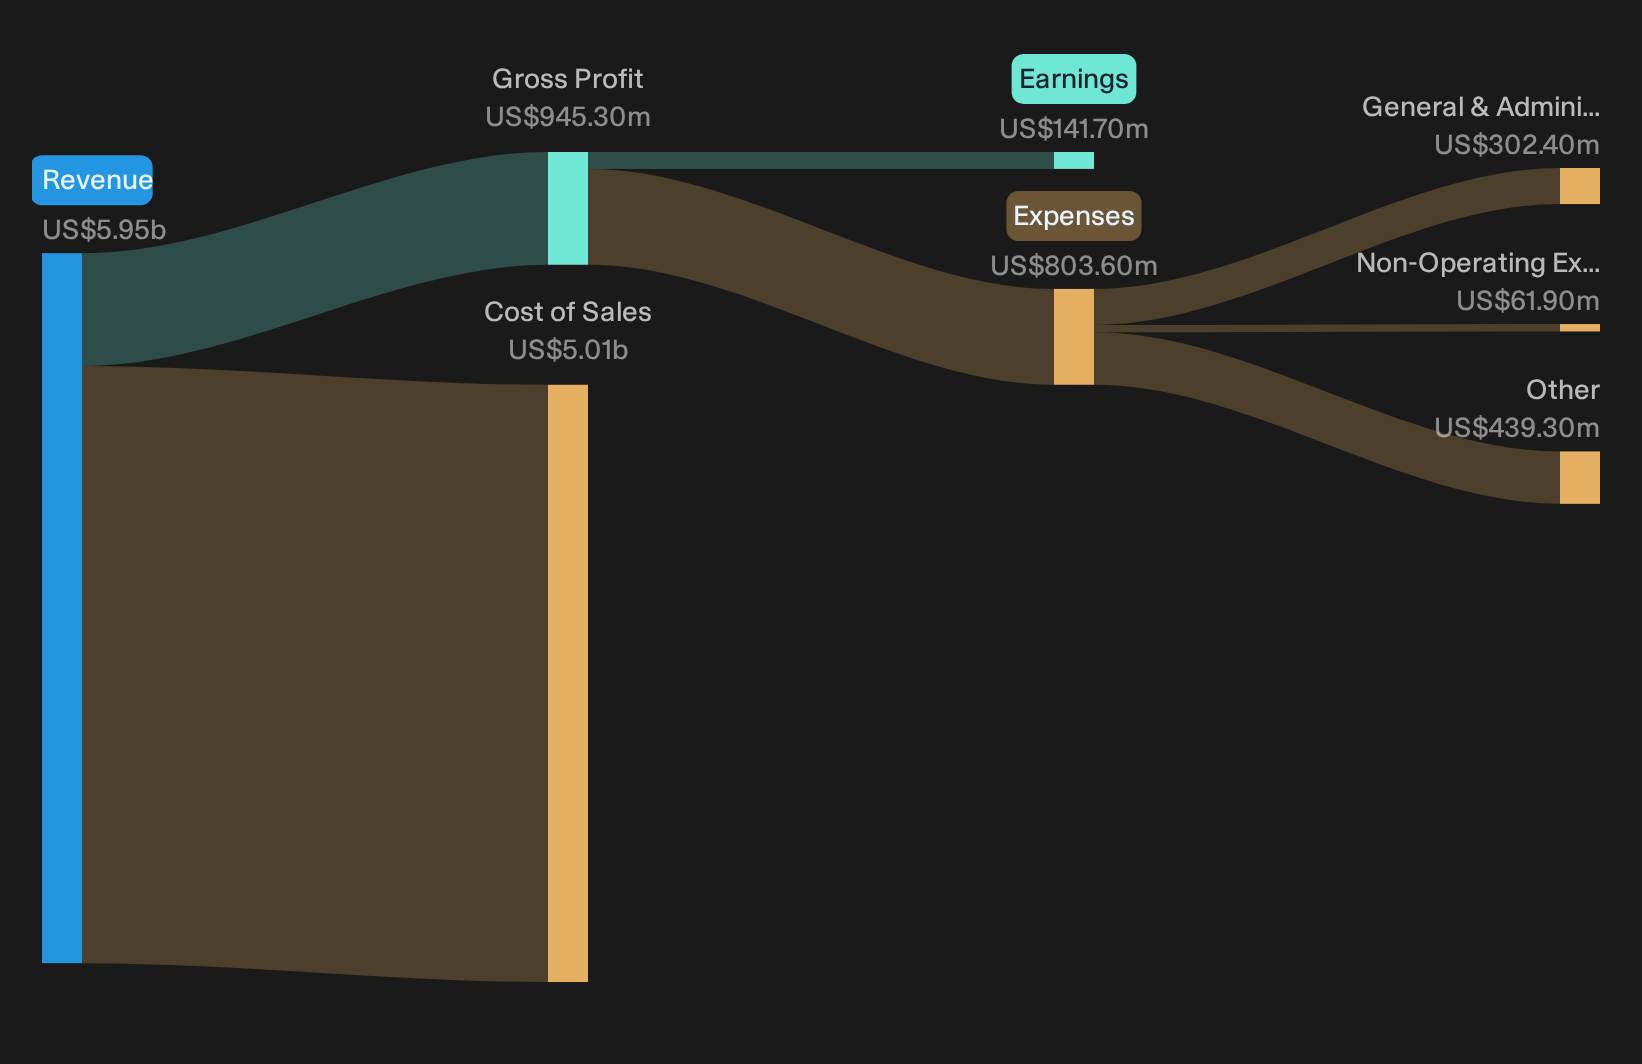
Schneider National’s Cost Playbook Meets The Scoreboard
The bullish story argues that Schneider National’s upside comes from execution, not just tighter capacity.
"The main factor that would need to work out is that Schneider National continues to execute on its Dedicated and Intermodal mix shift and multi-year $40 million cost-savings initiatives while keeping truckload capacity disciplined as supply exits the market."
Q3 results give real proof points. Enterprise adjusted income from operations rose faster than revenue, operating ratio improved 170 basis points, and Truckload lifted revenue per truck per week and network revenue per truck while tractor counts fell. Intermodal posted higher revenue per order and a stronger operating ratio. That combination signals the cost and mix thesis is hitting early milestones.
The price and this Narrative do not agree. → Uncover what this Narrative says Schneider National is actually worth.
Schneider National: Stress Testing Execution Fears
Bearish investors worry Schneider National cannot keep pace with larger tech heavy rivals that pour more money into automation and autonomy.
"Bearish analysts expect Schneider National to struggle to keep up with larger carriers that are using AI, automation and autonomous pilots to reshape truckload and brokerage economics, which could pressure its traditional trucking and logistics business if execution slips."
Q3 does not show that squeeze yet. Adjusted income from operations grew much faster than revenue, and the Truckload operating ratio moved into the low 90s while tractor counts declined. Logistics earnings were affected by a one time claim, not a clear technology gap. The share price drift over 7, 30 and 90 days instead reflects a higher bar for proving these gains are durable.
Hunt For Quiet Freight Opportunities
Schneider National just showed how execution can matter more than a single day’s share move. The real opportunity could sit in companies that look mispriced before expectations catch up.
- Company 1 - 38% below our estimate - expand a new manufacturing and supply chain buildout while shifting more volume into higher margin film and installation channels across regions.
- Company 2 - 31% below our estimate - anchor critical digital infrastructure components that handle processing, connectivity, and security whenever large customers upgrade data intensive systems.
- Company 3 - 37% below our estimate - lean into heavier freight and AI powered carrier vetting to tilt its agent model toward higher productivity and tighter risk control.
That is three of the list. See every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com