


The Q3 2026 scorecard is in and Mohawk Industries just sparked a sentiment whiplash. After closing at about US$130, the stock jumped 7.3% to US$139.41 as traders rushed to price in the headline beat on earnings power.
Net sales landed at US$2.8b with basic earnings per share of US$2.73, and the market instantly treated that as a clean read on flooring demand and pricing strength. The real story is how that one day surge squares with a business still grinding through soft volumes and tight consumer budgets.
Love the earnings pop but worried Mohawk Industries is still wrestling with soft volumes and cautious consumers? Scan the list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs Q3 2025): US$2,786 million vs. US$2,757.9 million (up about 1%)
- Net Income (Excl. Extra Items) (Q3 2026 vs Q3 2025): US$163.1 million vs. US$108.8 million (up about 50%)
- Basic EPS (Q3 2026 vs Q3 2025): US$2.73 vs. US$1.75 (up about 56%)
- Adjusted EBITDA Margin (Q3 2026): US$353 million on US$2,786 million net sales, around 12.7% (management figure)
Earnings tell you what Mohawk Industries booked on paper, but the cash coming through the door is what valuation driven investors usually care about most.
Look through Mohawk Industries' cash flows instead of just the Q3 2026 headline and the stock could be a clear 17% undervalued.
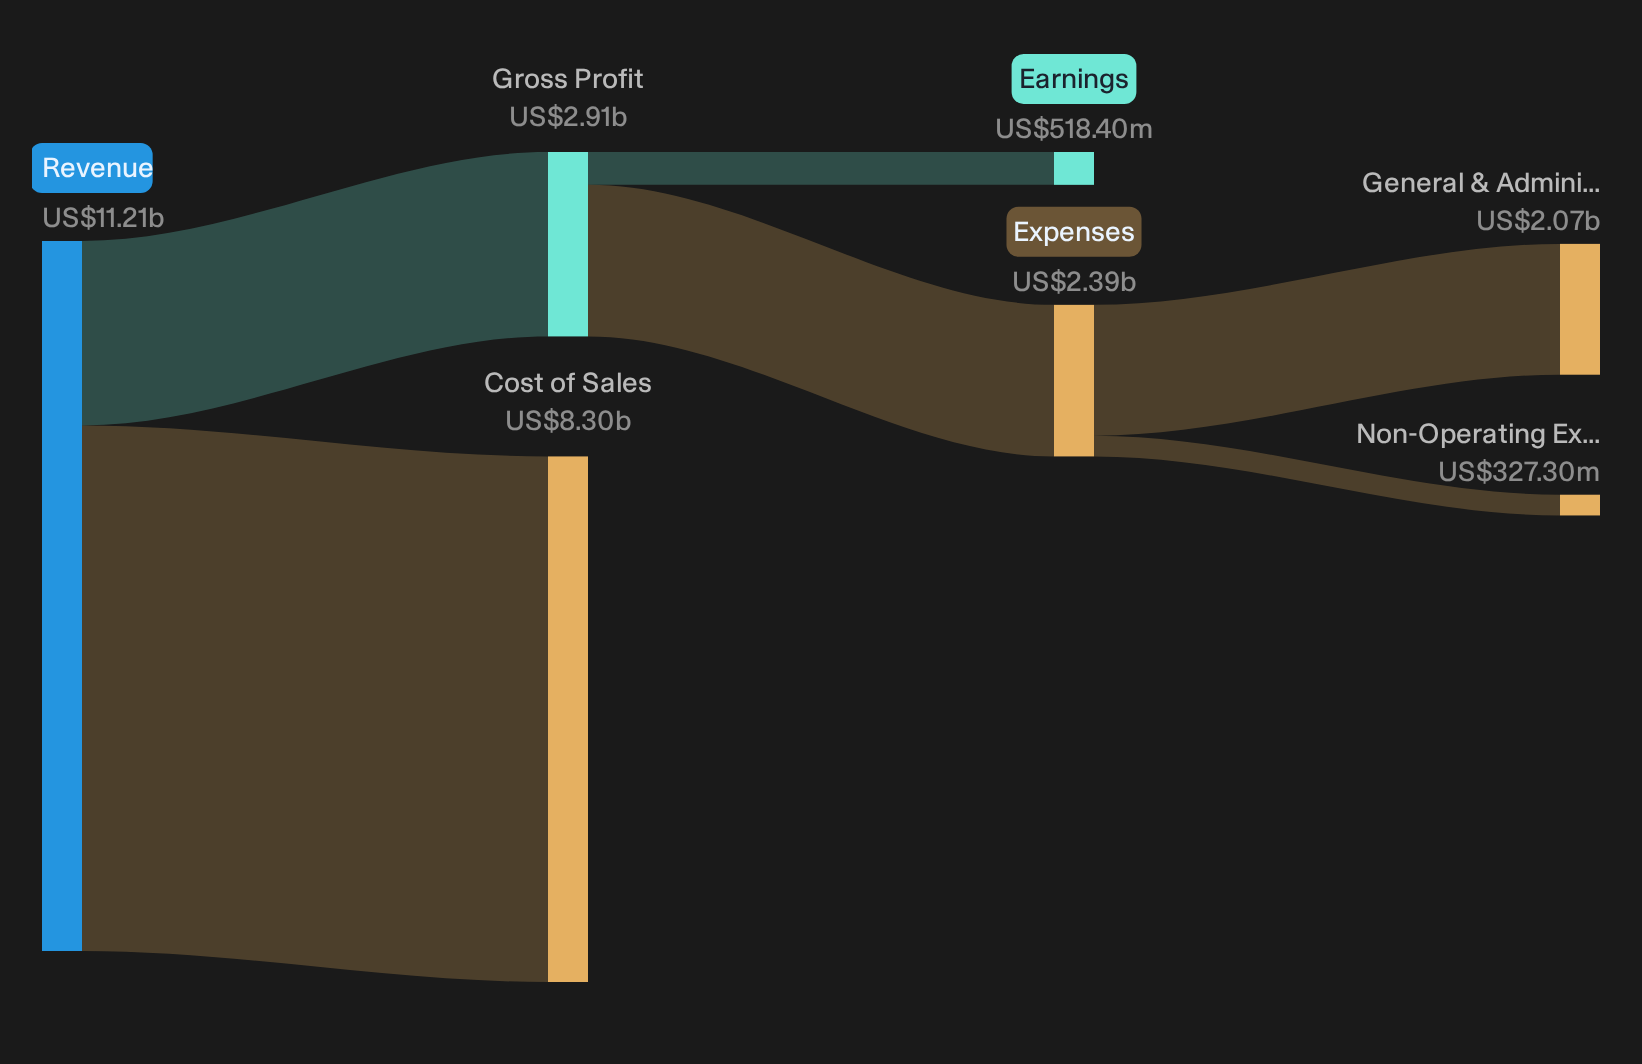
Evaluating Mohawk’s Mix Shift Milestones
Bulls argue Mohawk Industries can reshape earnings quality by leaning into premium categories rather than waiting for housing to recover.
"Expansion of higher value ceramic offerings, including premium collections, larger porcelain slabs and advanced printing capabilities, is shifting mix toward products with richer design and pricing power, which can support revenue and operating margins."
Q3 results show that thesis partly on track. Global Ceramic volumes declined 1%, yet price and mix added 2% and, together with productivity, largely offset higher energy and fuel costs. Across the group, price and mix contributed 4% against a 4% volume decline, which indicates Mohawk is monetising higher value offerings even while end demand stays soft.
One Narrative disagrees with today's price. → See where this Narrative says Mohawk Industries should trade.
Mohawk bear case: demand drag still biting
For the cautious view on Mohawk Industries, the key worry is that weak housing and remodel trends choke off volume and keep earnings reliant on temporary supports.
"While lower mortgage rates, record consumer savings in Europe and higher home equity are expected to encourage more remodeling and existing home sales over time, the global flooring industry has been weak for several years and any slower than expected repair and remodel recovery would cap volume growth and earnings expansion."
Q3 validates that concern. Volumes declined 4% overall, with Flooring Rest of World down about 10%. Price and mix, plus tariff refunds and productivity, did the heavy lifting. Earnings expanded, but the volume milestone the bears focus on was missed again.
Hunt For Mispriced Strength
Mohawk Industries shows how fast sentiment can change when earnings meet expectations. The real opportunity is finding stocks that could be undervalued before valuations change.
- Company 1 - 46% below our estimate - expands merchant payment volumes across new channels and automates higher margin local pay-in and pay-out flows.
- Company 2 - 29% below our estimate - scales a low cost digital banking platform as customers deepen engagement and a key new market reaches breakeven.
- Company 3 - 27% below our estimate - supplies testing gear and components needed when utilities upgrade grids and defense and aerospace programs refresh critical systems.
That is three of the list. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com