


Integer Holdings came into this Q3 2026 earnings print priced for quality rather than drama. The stock barely flinched after the release, edging just 0.06% higher to US$126.59, which suggests traders saw nothing shocking in the headline numbers. The real story sits in profit pressure. Net income from continuing operations for the trailing twelve months is US$103.7m against a quarterly run rate that now points lower, and basic earnings per share of US$0.44 this quarter underlines that squeeze.
Love Integer Holdings' quality tilt but concerned about that thinner earnings line this quarter? Benchmark it against a list of solid balance sheet and fundamentals stocks (25 results) to see businesses that pair resilient profit profiles with stronger financial cushions.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$449.7m vs. US$467.7m (down 3.9%)
- Net Income from Continuing Operations (Q3 2026 vs. Q3 2025): US$15.0m vs. US$39.7m (down 62.3%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.44 vs. US$1.13 (down 61.1%)
- Trailing 12-Month Net Margin (Q3 2026 vs. prior year): 5.7% vs. 4.8% (higher margin level on this measure)
Earnings are one thing, and Integer Holdings' Q3 report focuses squarely on that accounting line, but valuation focused investors usually care more about how much hard cash the business can generate over time.
When you line up Integer Holdings' recent cash flows against its current share price, the stock could be a striking 34% undervalued.
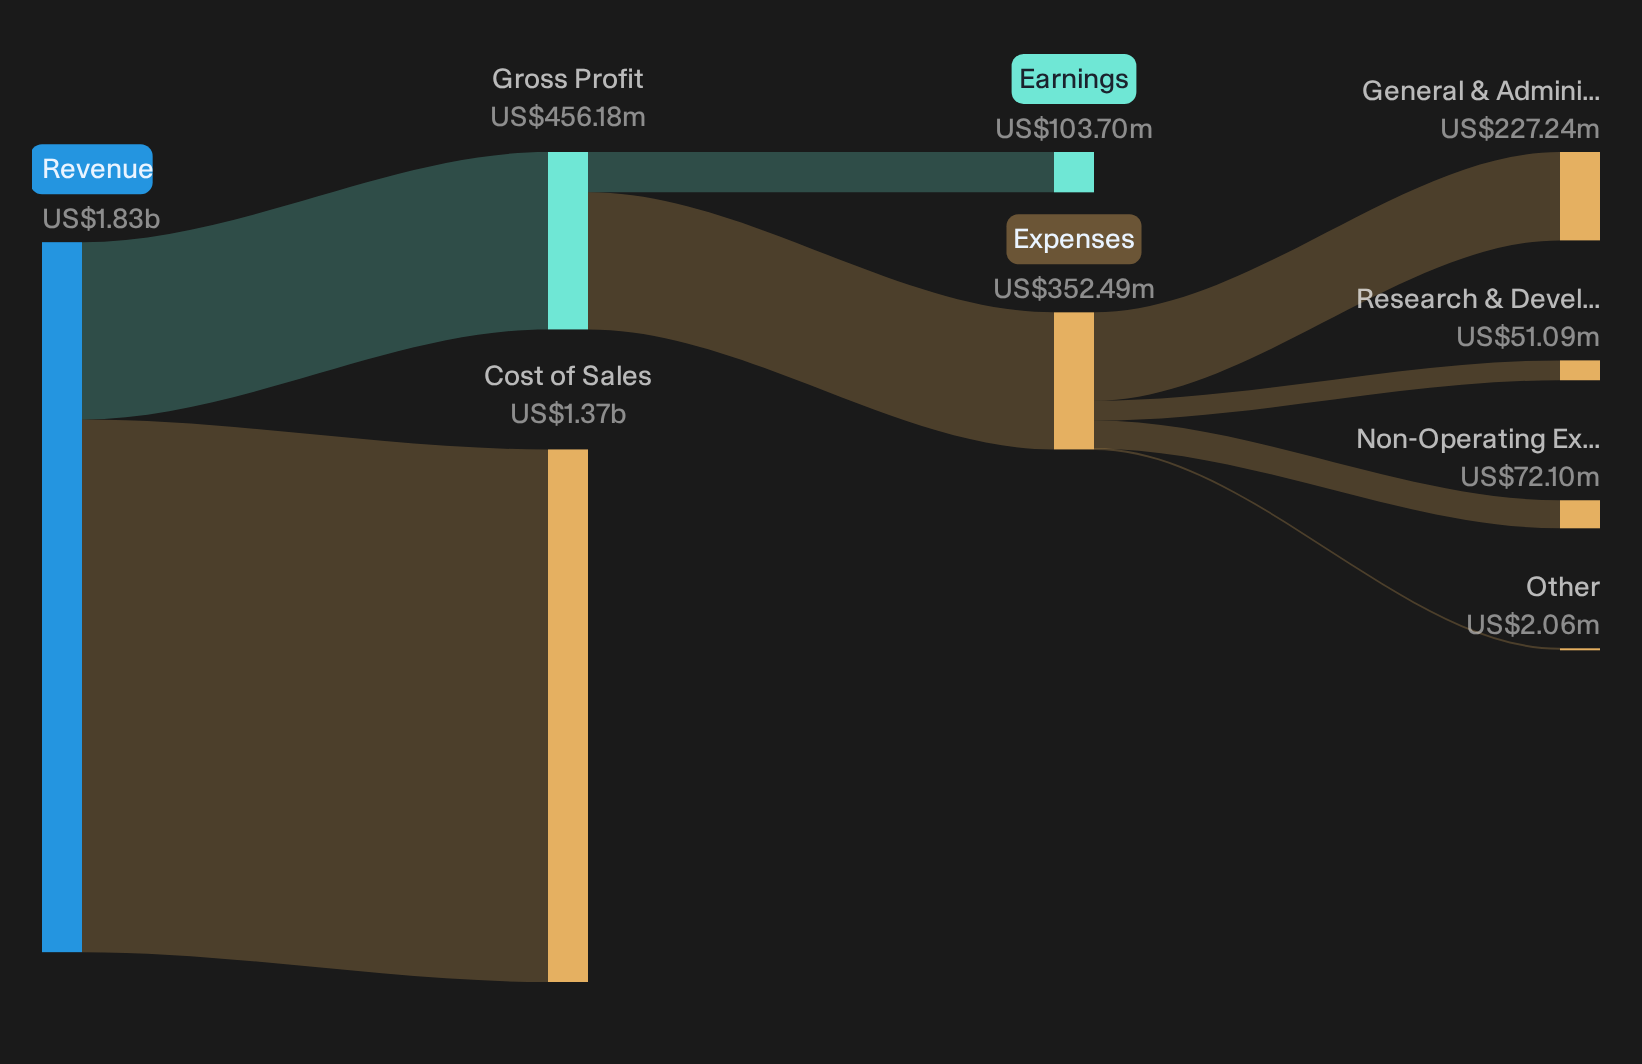
Integer’s Growth Story Meets Slower Quarter
For the bullish outsourcing and pipeline story at Integer Holdings, the question is how well current execution lines up with that ambition.
"The much larger product development pipeline, with sales over 300% above 2017 levels and roughly 80% of projects tied to electrophysiology, neurovascular, structural heart and neuromodulation, provides a queue of potential design wins that can convert into launched programs and incremental revenue."
Q3 did not show that conversion feeding through strongly. Revenue fell 3.9% year on year and net income from continuing operations declined 62.3%. A higher trailing 12 month net margin of 5.7% versus 4.8% hints at longer arc efficiency, but the quarter itself looks like a missed milestone for the growth pipeline thesis.
Bear Case On Execution Risk Gains Support
The more cautious view focuses on whether Integer Holdings can offset guidance cuts and product underperformance with cost work and system improvements.
"The earlier concern that margin expansion depends on operational improvements and acquisitions remains in place. The subsequent guidance cuts for 2026, along with the need to lean on the Integer Production System and fixed cost leverage, show that if efficiency gains do not offset softer volumes or higher costs, gross margin and operating margin may fall short of the levels implied by the current earnings narrative."
Q3 results lean toward this worry. Softer sales and a 61.1% drop in basic EPS to US$0.44 indicate that current efficiency levers are not yet offsetting volume and mix pressure, keeping the margin recovery milestone unmet for now.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt Quiet Disconnects In Quality
Integer Holdings reports a relatively muted share price reaction that may still reflect changes in confidence around execution. The real opportunity may sit in seeking stocks that could be undervalued before expectations adjust.
- Company 1 - 41% below our estimate - build temporary access platforms that support long duration infrastructure work despite volatile construction schedules.
- Company 2 - 30% below our estimate - sell AI focused networking and data infrastructure as enterprises transition workloads into cloud based, recurring consumption models.
- Company 3 - 48% below our estimate - move from lower margin assembly toward co designing critical hardware that can secure manufacturing roles in customers' AI and automation programs.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com