


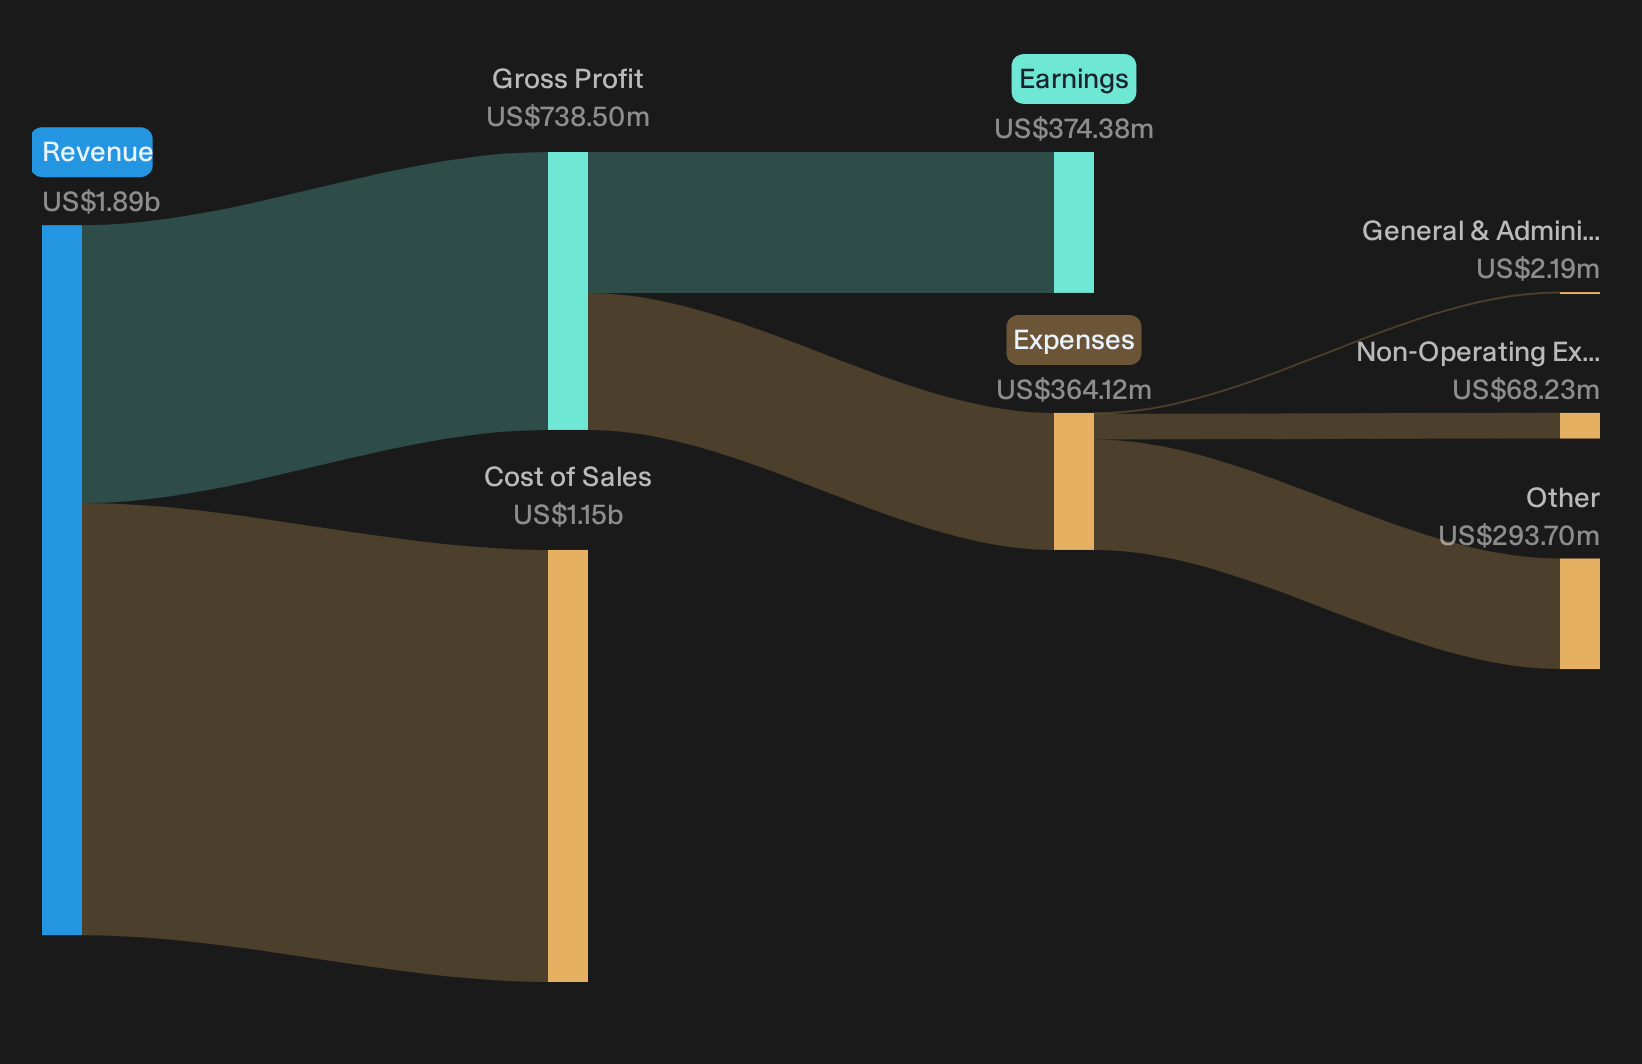
IDACORP stock came into today already on a solid run, with the shares up roughly 11% over the past month, then added another 1.2% to close at US$145.38 after the Q3 2026 report landed. The headline was clear. Quarterly earnings per share reached about US$2.78 on revenue of roughly US$608 million, helped by strong industrial demand and customer growth across its regulated utility footprint.
That kind of steady, regulated earnings power can look comforting in a single quarter. The real question for you now sits in the multi-year picture, where premium valuation and balance sheet coverage risks share the stage with this profit strength.
Love IDACORP’s regulated earnings stability but concerned about paying up when valuation and debt coverage questions linger? Consider a tighter filter with our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue, Q3 2026 vs. Q3 2025: US$608.0 million vs. US$524.4 million (up about 16%)
- Net Income, Q3 2026 vs. Q3 2025: US$160.2 million vs. US$124.4 million (up about 29%)
- Basic EPS, Q3 2026 vs. Q3 2025: US$2.78 vs. US$2.30 (up about 21%)
- Trailing 12-Month Net Margin, Q3 2026 vs. Q3 2025: 19.8% vs. 17.6% (margin higher year over year)
IDACORP just raised earnings guidance on surging industrial demand. Ask Charlie what IDACORP’s 8.9% load growth really means.
IDACORP load story meets early execution tests
The growth pitch hinges on big users actually showing up and using power.
"Robust customer and population growth in IDACORP's service area, including a 2.3% increase in customer count in both 2025 and the first half of 2026 and growing industrial loads, together with ramping contracts from large users such as Micron and Meta, is expected to keep adding to electric sales and retail revenues."
Q3 volume and mix back that up. Customer count rose 2.2% year over year, while industrial revenue climbed about 27% with large contracts adding roughly US$12 million of operating income in the quarter and about US$20 million year to date. Weather normalised sales increased 2.9% and industrial or special contracts advanced 5.8%, reinforcing raised EPS guidance.
IDACORP capex and regulatory risk still live issues
The concern is that a huge build program and heavy funding needs could outgrow what regulators and customers will tolerate.
"IDACORP continues to plan very large annual capital expenditure of around US$1.3b to US$1.5b in 2026 and about US$7b from 2026 to 2030 to support an expected increase in rate base from about US$5.3b in 2025 to around US$11b in 2030. This is being funded with a sizeable mix of new debt and an estimated US$2b of equity, so any point where regulators slow cost recovery, disallow projects or customer affordability concerns cap rate increases could leave more assets earning less than anticipated and weigh on return on equity and earnings."
Current results ease but do not remove that issue. Capex is tracking toward the high end of US$1.3b to US$1.5b, several major gas and transmission projects have certificates or permits in hand, and equity is roughly 51% after forward issuance, which matches the targeted 50/50 capital mix. Idaho allowed growth and large contract revenues to support raised 2026 EPS guidance without a 2026 general rate case, with a June 2027 filing only described as likely rather than launched.
The price and this Narrative do not agree. → Uncover what this Narrative says IDACORP is actually worth.
Hunt Quiet Disconnects Before They Close
IDACORP just showed how a single quarter can change how long term investors view the business. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 31% below our estimate - builds and integrates custom chips and software for large cloud customers handling massive data.
- Company 2 - 48% below our estimate - shifts from basic assembly to co-designing complex hardware with clients through a sketch-to-scale model.
- Company 3 - 38% below our estimate - expands manufacturing capacity to support higher margin protective films and installation services for multiple sales channels.
Those are three of them. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com