


Mastercard came into this Q3 2026 print riding strong momentum, with the stock up double digits over the past month and edging another 0.4% higher to about US$638 today. The move looks modest compared with what the numbers just delivered. Net revenue reached US$9.8b and basic earnings per share came in at US$5.29, both reinforcing a powerful profit trend.
The market reaction so far suggests a shrug. The financial story points to something sturdier, as Mastercard continues to convert payment volumes into high margin earnings power that long term holders have been betting on.
Love Mastercard's high margin earnings machine but want more options with similar strength in the financials? Scan the list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$9,807m vs. US$8,602m (up 14.0%)
- Net Income (Excl. Extra Items) (Q3 2026 vs Q3 2025): US$4,628m vs. US$3,927m (up 17.9%)
- Basic EPS (Q3 2026 vs Q3 2025): US$5.29 vs. US$4.35 (up 21.7%)
- Net Profit Margin, trailing 12 months (latest year vs prior year): 46.7% vs. 45.3% (higher margin level; earnings up 19% year on year)
Mastercard is betting big on agentic commerce with OpenAI. Ask Charlie what Mastercard’s OpenAI deal could mean for earnings.
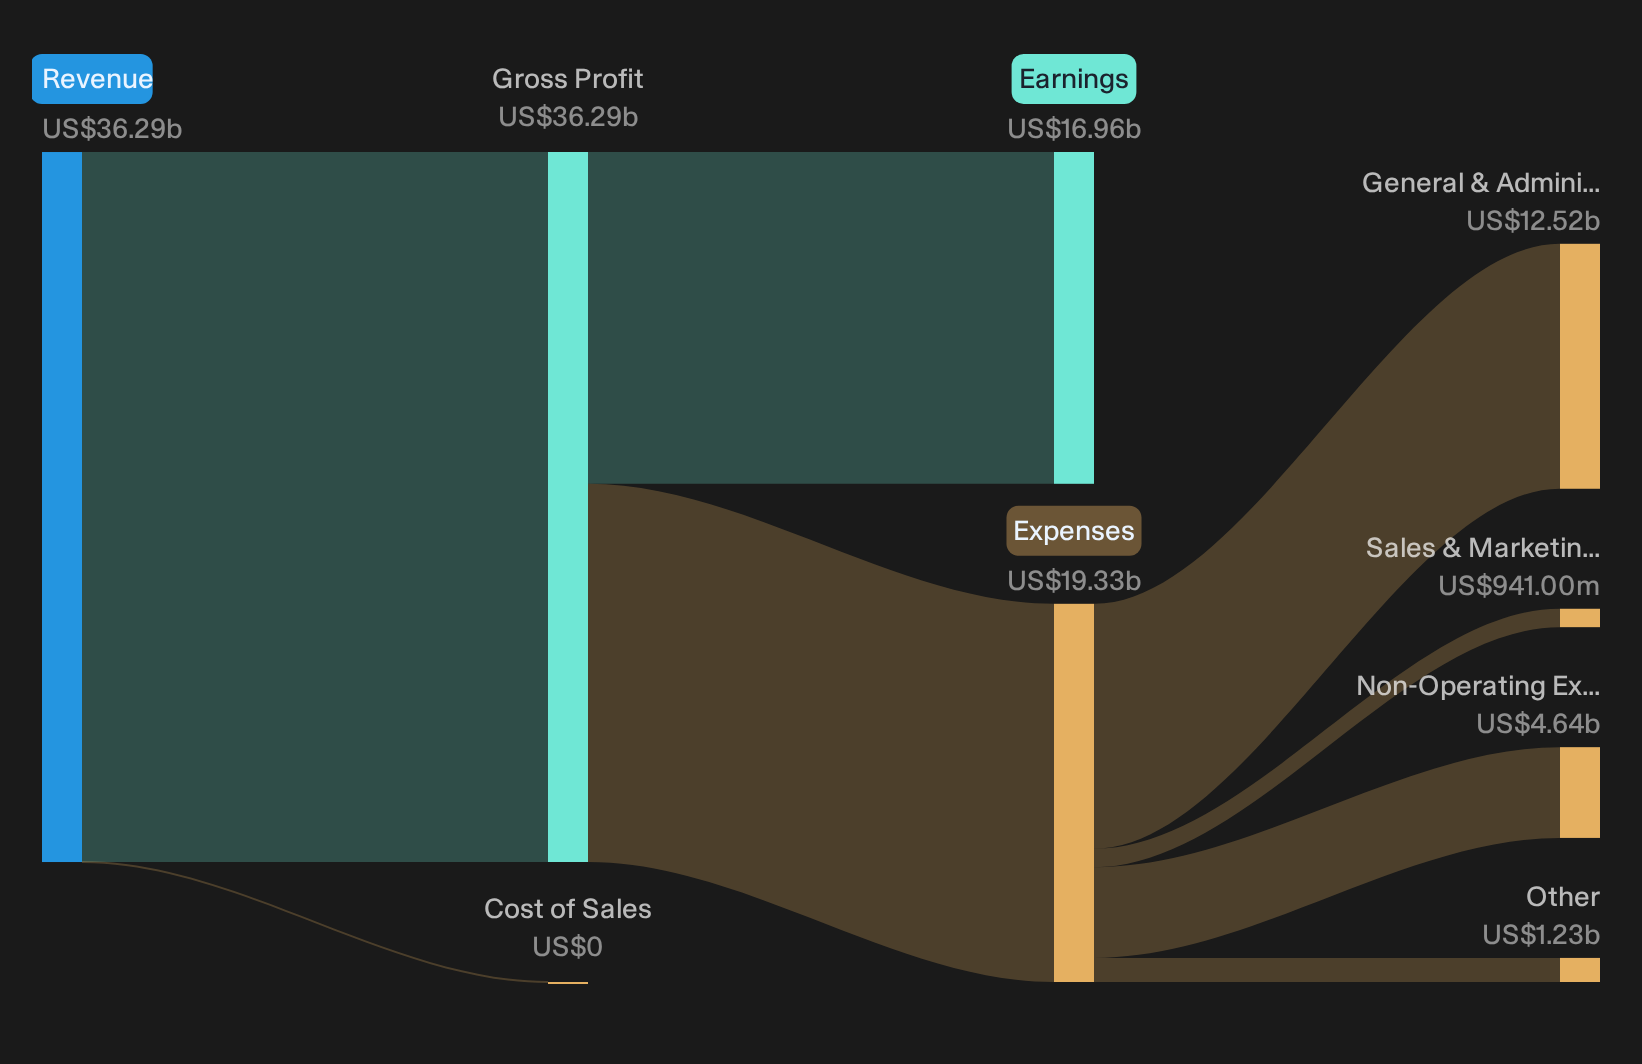
Mastercard’s Asset-Light Rail Model Under the Microscope
"It never lends money and never holds credit risk on its books, it just takes a small cut every time a transaction crosses its network. That's the whole business model, and it's a remarkably good one: high margins, low capital intensity, and growth tied to the slow global shift away from cash."
Q3 results support this toll‑booth description. Mastercard converted a 14% rise in net revenue into 18% higher net income and 22% higher basic EPS, while the trailing 12‑month net profit margin edged up to 46.7%. That widening margin, even as operating expenses increased at a double‑digit clip, points to the fee‑based, low capital burden model still working as advertised.
Testing Fears Of Disruption To Mastercard’s Moat
"Mastercard isn't standing still while stablecoins reshape payments. It is building settlement infrastructure and tools for 'agentic commerce' around them instead of fighting the trend. Whether that becomes a meaningful new revenue stream or just defends the existing one, it argues for the moat holding rather than eroding, and gives the company a second growth story to lean on if card volumes ever slow."
The concern is that new rails and AI agents erode Mastercard’s role. Q3 data does not yet show that pressure winning out. Cross‑border volume rose 11%, value‑added services grew 19%, and management highlighted early traction in agentic commerce and stablecoin infrastructure through the Global Money Platform and Arc. Regulatory and A2A competition remain live risks, but transaction and services trends this quarter lean toward moat defence rather than slippage.
One Narrative disagrees with today's price. → See where this Narrative says Mastercard should trade.
Hunt Quiet Fundamental Shifts
Mastercard just showed how a clean earnings story can pair with a muted share move. The real opportunity sits in stocks that could be undervalued before the market adjusts.
- Company 1 - 37% below our estimate - use new acquisitions and lower cost deposits to reshape a niche lender into a broader, more efficient commercial and retail franchise.
- Company 2 - 34% below our estimate - expand production that feeds long term optical networking and solar contracts tied to digital infrastructure and energy transition spending commitments.
- Company 3 - 38% below our estimate - ramp high horsepower engine capacity and power projects to meet rising data center demand while containing losses in newer electrified offerings.
That is three of the list. See every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com