


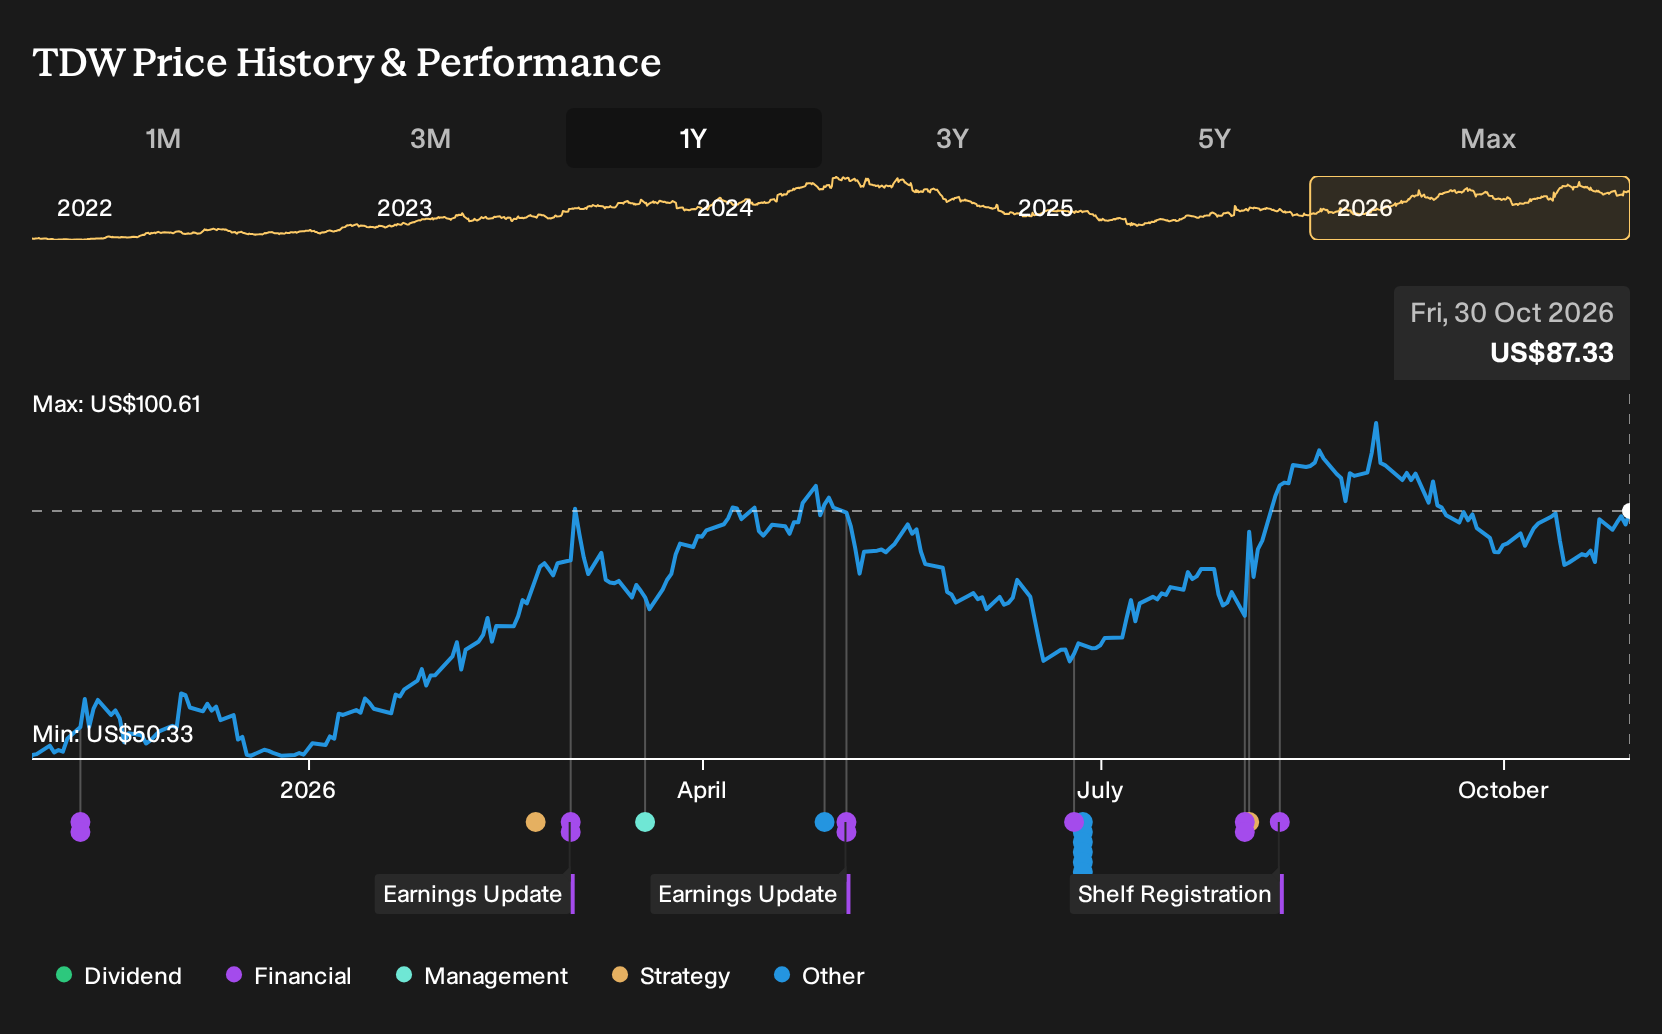
If Tidewater sat on your watchlist instead of in your account, the move will feel expensive in hindsight. For Tidewater shareholders, the return over the past year was 72.6%, including dividends. That outcome now raises an uncomfortable question. Back on 30 October 2025, when analysts were arguing over vessel scarcity, offshore demand and whether mergers would really lift utilization, what signals in the business model could have helped you judge that consolidation-driven expansion was worth backing?
If the move has made Tidewater harder to judge, start where the gap is still open and scan 29 high quality undervalued stocks.
The Argument Tidewater Investors Were Really Weighing
The shares cost US$50.44 at the start of the period, and Tidewater investors were effectively choosing between two grounded stories about what that price already assumed.
On the optimistic side, the bull narrative argued that tight vessel supply and solid offshore activity supported a Fair Value of US$61.67, the price implied by forecasts that revenue would grow 3.6% a year and profit margins would reach 20.2%.
The bearish view pointed to a Fair Value of US$33.85. In this case, decarbonization and regulatory costs were seen as serious threats to Tidewater, even though vessel scarcity might keep day rates and utilization from collapsing.
What The Results Changed For Tidewater’s Story
The Wilson Sons Ultratug deal gave Tidewater exactly the consolidation move the bullish case depended on, adding 22 vessels and a bigger Brazilian presence. The measured results told a tougher story. Revenue in Q2 2026 was US$342.3 million versus US$341.4 million a year earlier, while net income dropped to US$21.7 million and net margin fell to 6.3% from 21.4%. Overall, the evidence cut both ways.
The whole debate turned on whether tighter fleets would translate into stronger profitability rather than just a larger platform. For any other contractor built on acquisitions, you would track net margin and post deal cost lines against earlier forecasts, rather than just celebrate top line progress or fleet size.
What Tidewater’s Run Now Asks You To Believe
Tidewater now trades at US$87.33, and the selected Narrative’s Fair Value sits below that level. The core worry is not demand. It is whether extra operating and drydock costs eat up the benefit of tight fleets and the Wilson Sons Ultratug acquisition.
For today’s price to add up, a buyer needs confidence that Tidewater can keep converting strong contracted activity into consistent free cash flow after higher conflict related and maintenance spending.
"While Tidewater benefits from tight offshore support vessel supply and stronger day rates, the forecast that a continuation of Middle East conflict conditions could add about US$10 million to US$11 million in quarterly operating costs, with only roughly half contractually billable, points to a scenario where incremental revenue is largely absorbed by unrecouped expenses and compresses net margins."
One Narrative disagrees with today's price. → See where this Narrative says Tidewater should trade
Looking Beyond Tidewater’s Deck
Tidewater lives on offshore activity, and that story depends heavily on energy demand. You could stop there, or you could ask where the fuel itself comes from.
One large producer is pouring money into liquefied natural gas and deepwater fields. That effort targets long term gas supply and higher margin barrels.
It is also stripping out costs and selling weaker assets. Management is trying to focus the portfolio on projects that throw off steadier cash.
If those efforts reshape earnings quality, the ripple will reach every offshore contractor. Tidewater’s vessels may be one layer in a much larger decision.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 18% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com