


Fed officials are again talking about lifting rates, and that puts a spotlight on a corner of the market that lives and dies by small moves in yields. Cash-linked financials can feel dull in calm times, then suddenly matter a lot when policy makers hint at extra hikes. This article walks through three stocks from our screener that appear particularly exposed to the latest Fed commentary, and explains why that exposure may be relevant for your portfolio decisions.
The three stocks discussed next are just a sample, and the full screen surfaced 28 more U.S. rate-sensitive financials and cash-linked product providers with equally compelling business stories that are not covered here. To identify and analyze the highest-conviction ideas for your own watchlist, head straight into the U.S. Rate-Sensitive Financials and Cash-Linked Product Providers screener.
MVB Financial (MVBF)
MVB Financial blends a traditional community bank with national fintech and cash-focused services, so its net interest income and deposit mix sit directly in the crosshairs of a higher-for-longer rate story that matters for this screener.
MVB Financial runs MVB Bank, serving households and businesses with deposits, loans and fintech-driven cash services, and has a market cap of about $387 million.
"Expansion of payments, banking as a service and digital gaming relationships with large partners such as Fiserv, Worldpay, Intuit Credit Karma, FanDuel, DraftKings and BetMGM positions MVB to capture more transaction volume and fee based revenue as these ecosystems keep growing."
How those fee streams behave if one key pressure on funding costs and credit quality moves in the wrong direction will be crucial.
If that pressure point matters to your thesis, read the full narrative for MVB Financial to see how rate moves could accelerate or stall the cash-linked story at MVB Financial.

Prosperity Bancshares (PB)
Prosperity Bancshares is built around everyday cash management for Texas and Oklahoma households and businesses, with a broad mix of deposits and short term lending products that tie directly into this screener’s focus on rate sensitive balance sheets.
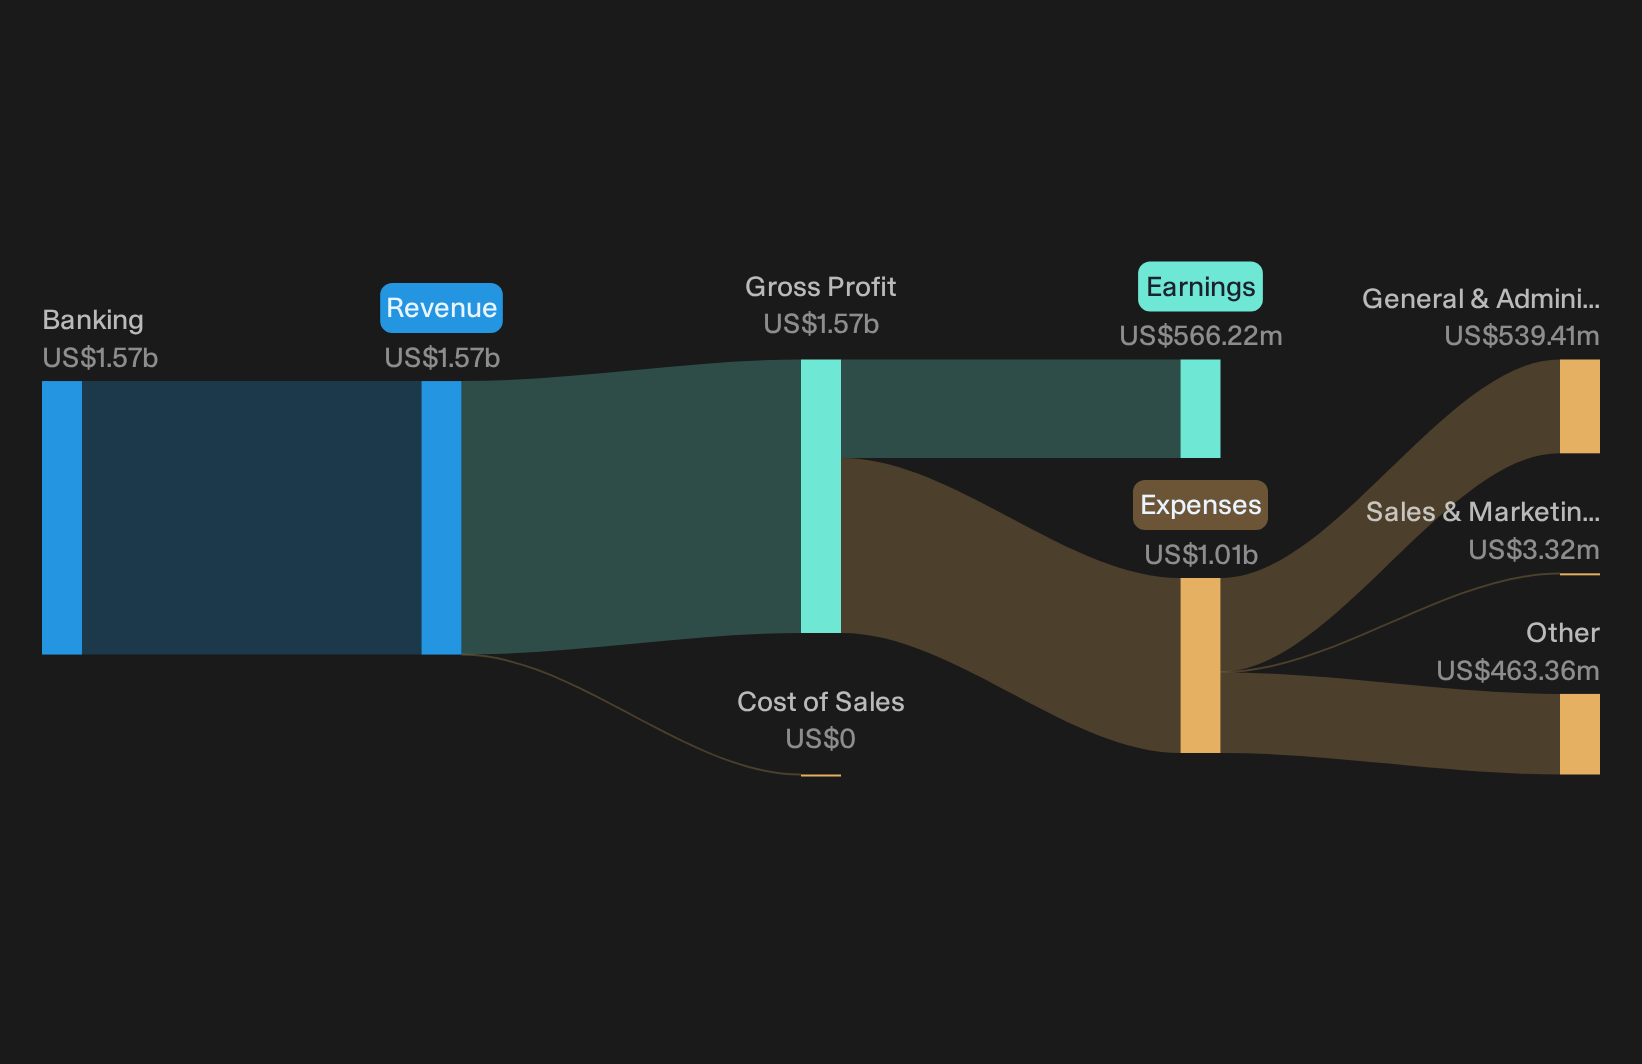
Prosperity Bancshares generates about US$1.6b of banking revenue in the United States and carries a roughly US$8.7b market value, putting it in the larger regional bank camp that many rate focused investors look at first.
Prosperity Bancshares leans heavily on this rate story because its loan book and funding mix are structured to benefit when short term yields stay higher for longer. That is where the latest Fed commentary really bites.
"Completion of the American Bank, Texas Partners and Stellar transactions positions Prosperity Bancshares to consolidate a larger Texas and Oklahoma footprint, with management pointing to about US$100 to US$110 million of annual pretax cost savings that would directly support a lower efficiency ratio and higher net earnings power once integration is complete."
The real swing factor now is how one unseen pressure on future margins and cost savings resolves over the next few years.
That pressure could reshape the whole earnings story, so read the full narrative for Prosperity Bancshares to see whether Prosperity Bancshares is quietly building upside or masking future strain.
WaFd (WAFD)
WaFd leans directly into the screener’s rate and cash theme, running a traditional lending and deposit model where money market and savings balances help translate Fed moves into net interest income.
WaFd, Inc. is a Seattle based regional bank focused on lending and deposit services, generating about $776 million from thrift and savings activities in the United States, and carrying a roughly $2.2b market cap.
Fed officials are talking about keeping policy tighter for longer, and WaFd is the kind of regional lender where that stance can reshape the math on loans, deposits and fee based cash services more quickly than many investors expect.
"The Build 2030 shift toward true commercial banking and small business relationships, including reorganized business, corporate and commercial real estate banking teams, positions WaFd to grow higher yielding C&I and CRE loans, supporting faster revenue and earnings growth."
What happens to that plan if one quiet pressure on funding costs and credit quality moves in an unexpected direction will be crucial for WaFd investors.
If that quiet pressure is on your radar, read the full narrative for WaFd to see whether WaFd’s Build 2030 pivot is accelerating strengths or masking future strain.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout stories, early momentum and under the radar opportunities can shift quickly once attention increases. Scan these curated lists now if you want to explore earlier-stage opportunities.
- Look for resilient balance sheets by running your filters through the list of solid balance sheet and fundamentals (25 results) while it may still be less widely followed.
- Track current earnings power instead of hype by focusing on 39 profitable AI stocks that aren't just burning cash before these cash generative AI companies become more broadly noticed.
- Review potential income streams that can continue paying even when sentiment weakens by exploring the 5 dividend fortresses while yields and prices remain available at current levels.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com