


Why VinFast Auto’s latest earnings and U.S. offers matter
VinFast Auto (NasdaqGS:VFS) has drawn fresh attention after its Q2 2026 results showed higher revenue and a sharply smaller net loss, alongside aggressive U.S. lease deals and 0% APR offers on its MY27 VF 8 and VF 9 SUVs.
Recent trading shows VinFast Auto caught between improving sentiment and a long memory of volatility. The 7 day share price return of 6.51% and 90 day gain of 5.14% contrast with a year to date decline of 3.25%, while the 3 year total shareholder return is down 44.95%. Overall, momentum looks tentative rather than firmly established despite the latest earnings and U.S. offers.
Scan how VinFast Auto compares with other EV and auto players that screen strongly on cash flows and balance sheet strength through our curated list of solid balance sheet and fundamentals (25 results).
VinFast Auto’s shares have crept higher while analyst targets sit well above the current US$3.27 price. Is the fair value closer to today’s quote or to that richer range of estimates?
Most Popular Narrative: 46% Undervalued
VinFast Auto’s most followed valuation story puts fair value around $6.07, well above the recent $3.27 close, so the gap between price and expectations remains wide.
The main thing that has to go right is VinFast Auto successfully executing its shift to an asset light model and GSM ecosystem partnership so that higher vehicle volumes, lower capital intensity and targeted cost reductions can move margins closer to break even in Vietnam by 2027.
The current valuation implies VinFast Auto is priced as if execution on global expansion, ecosystem driven volumes and the transition toward improved underlying margins will not be fully reflected in the share price.
See why 10 investors see VinFast Auto as 46% undervalued.
Result: Fair Value of $6.07 (UNDERVALUED)
Still, the story can crack if VinFast Auto’s heavy cash burn keeps funding risk high, or if GSM related sales mask weaker underlying consumer demand.
Find out about the key risks to this VinFast Auto narrative.
Another view on VinFast Auto’s valuation
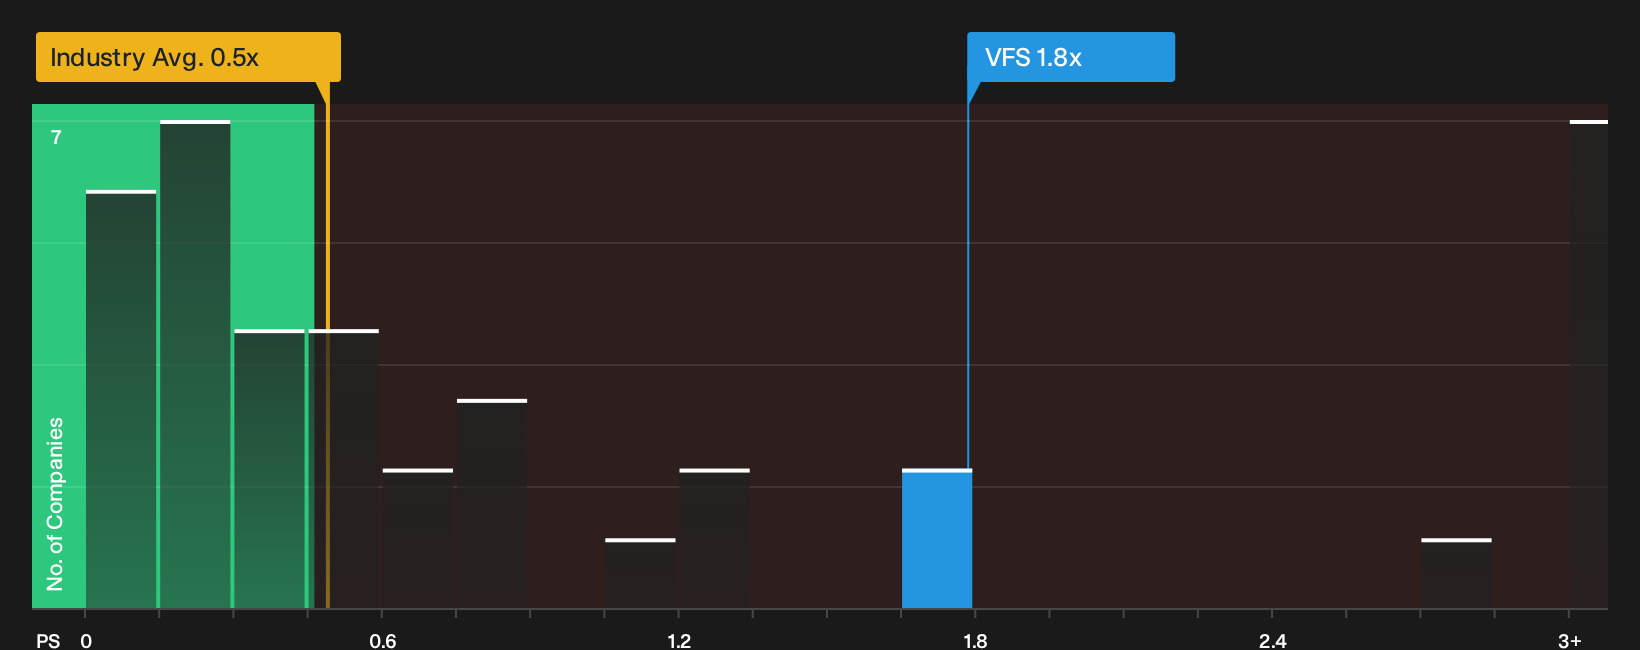
The analyst narrative points to fair value of $6.07, yet on simple pricing VinFast Auto looks expensive. The P/S ratio of 1.8x is higher than the US Auto sector at 0.5x, and far above a fair ratio estimate of 0.1x, which signals meaningful valuation risk if sentiment cools.
For investors who want to see how this pricing stacks up against the underlying numbers in more detail, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on VinFast Auto’s pricing and risks can pull you in opposite directions, so move quickly to inspect the data and weigh 1 key reward and 3 important warning signs
Looking for more VinFast Auto sized investment ideas?
If VinFast Auto has you thinking more carefully about price versus potential, do not stop here. The wider market still holds plenty of opportunities.
- Target resilient income by scanning companies we classify as dividend fortresses through the 5 dividend fortresses.
- Hunt for quality at a discount by filtering for 29 high quality undervalued stocks before enthusiasm crowds into the same trades.
- Strengthen your watchlist with companies that pair cash generation and balance sheet resilience using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com