


SK hynix has been one of the strongest performers in global semiconductors in recent years, and the stock’s rapid climb now raises a simple question for you as an investor: Are today’s earnings strong enough to support the current share price, or has enthusiasm moved faster than the company’s profit power?
- Over the past 5 years the share price has risen about 1,298%, which puts a lot of weight on whether SK hynix’s current and future earnings can stand behind that move.
- Recent headlines around record revenue, very high operating margins and long-term AI memory supply agreements suggest profit expectations and cash generation timing may have shifted meaningfully for this business.
- The analysts covering SK hynix have run their own numbers. See what analysts think SK hynix's shares could be worth.
The issue now is whether SK hynix’s current market value is justified by the earnings that investors are effectively paying for today.
If you want to stress test this same earnings question beyond SK hynix, apply the same analysis across 54 AI infrastructure stocks.
Does SK hynix Look Undervalued on Earnings?
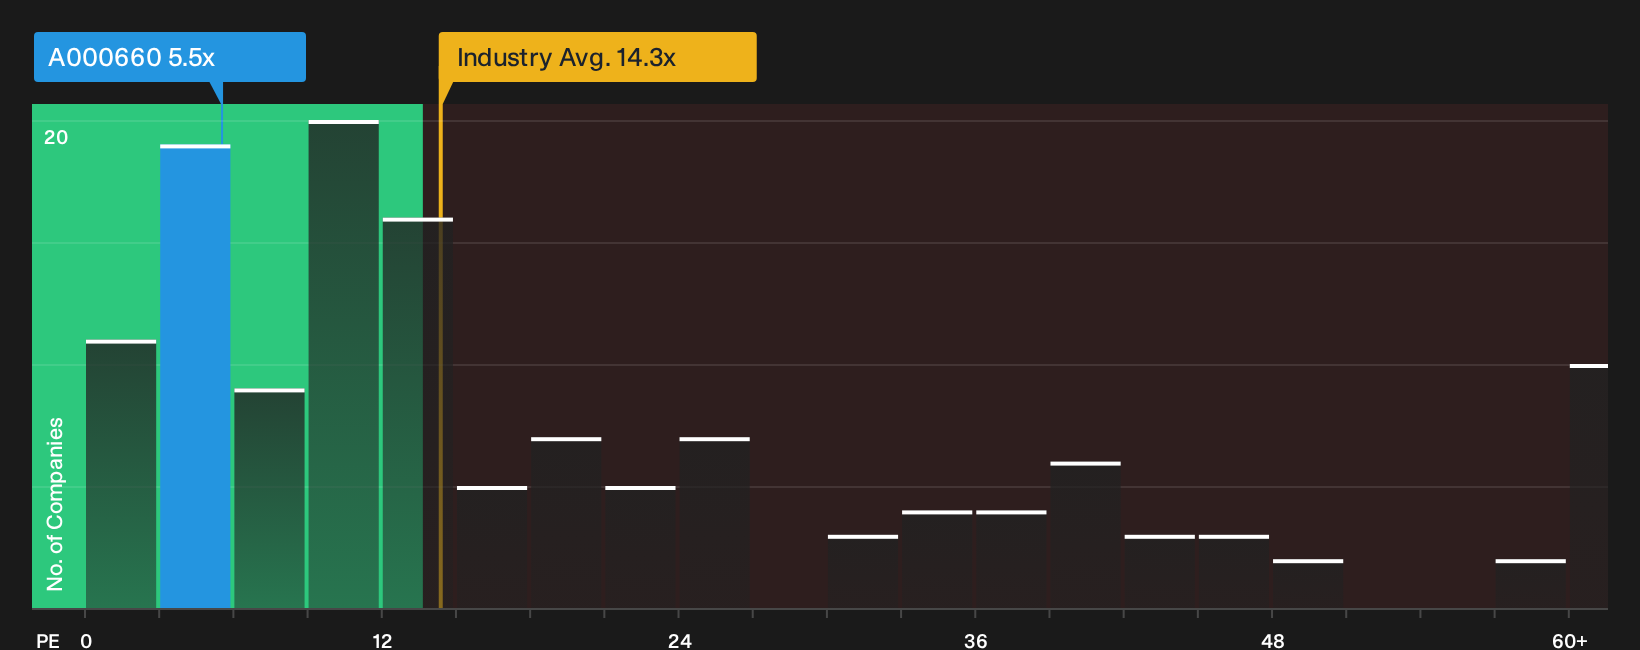
For SK hynix, the P/E ratio is a straightforward way to see what investors are paying for each unit of current earnings. The stock trades on about 5.5x earnings, which is less than half the 10.9x peer average and sits even further below the broader semiconductor industry on 14.3x. On this yardstick, the market is attaching a lower price tag to each won of SK hynix profit than to many other chip makers.
The fair multiple implied by Simply Wall St’s model, which blends the company’s growth profile, profitability, size and risk, is above the current P/E, so the shares screen as undervalued on this framework. Because the latest record quarter pushed revenue above ₩100t and lifted profitability, that gap exists despite investors already reacting positively to the AI memory story. For you as a shareholder or potential buyer, the key question is whether those earnings and contracts can sustain or improve from here, which would make a low P/E more meaningful than a simple headline discount. Explore the numbers behind SK hynix's P/E valuation.
The SK hynix Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for SK hynix pick up where the valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than it is today. Each scenario links its number to a clear view on how SK hynix's expansion, profitability and risk profile might evolve, giving you something concrete to revisit as new information comes through.
One of the top community narratives on SK hynix: 55% undervalued
"Close partnerships with large AI and GPU customers, including multiyear HBM co development and supply work with NVIDIA and around 10 long term agreements..."
Discover why this Narrative puts SK hynix at 55% undervalued.
Before acting on SK hynix’s valuation, there is one more lever to examine
Price and profits only tell part of the story, because the people setting SK hynix’s priorities and the way their pay is structured can heavily influence how those numbers evolve. See who runs SK hynix and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com