


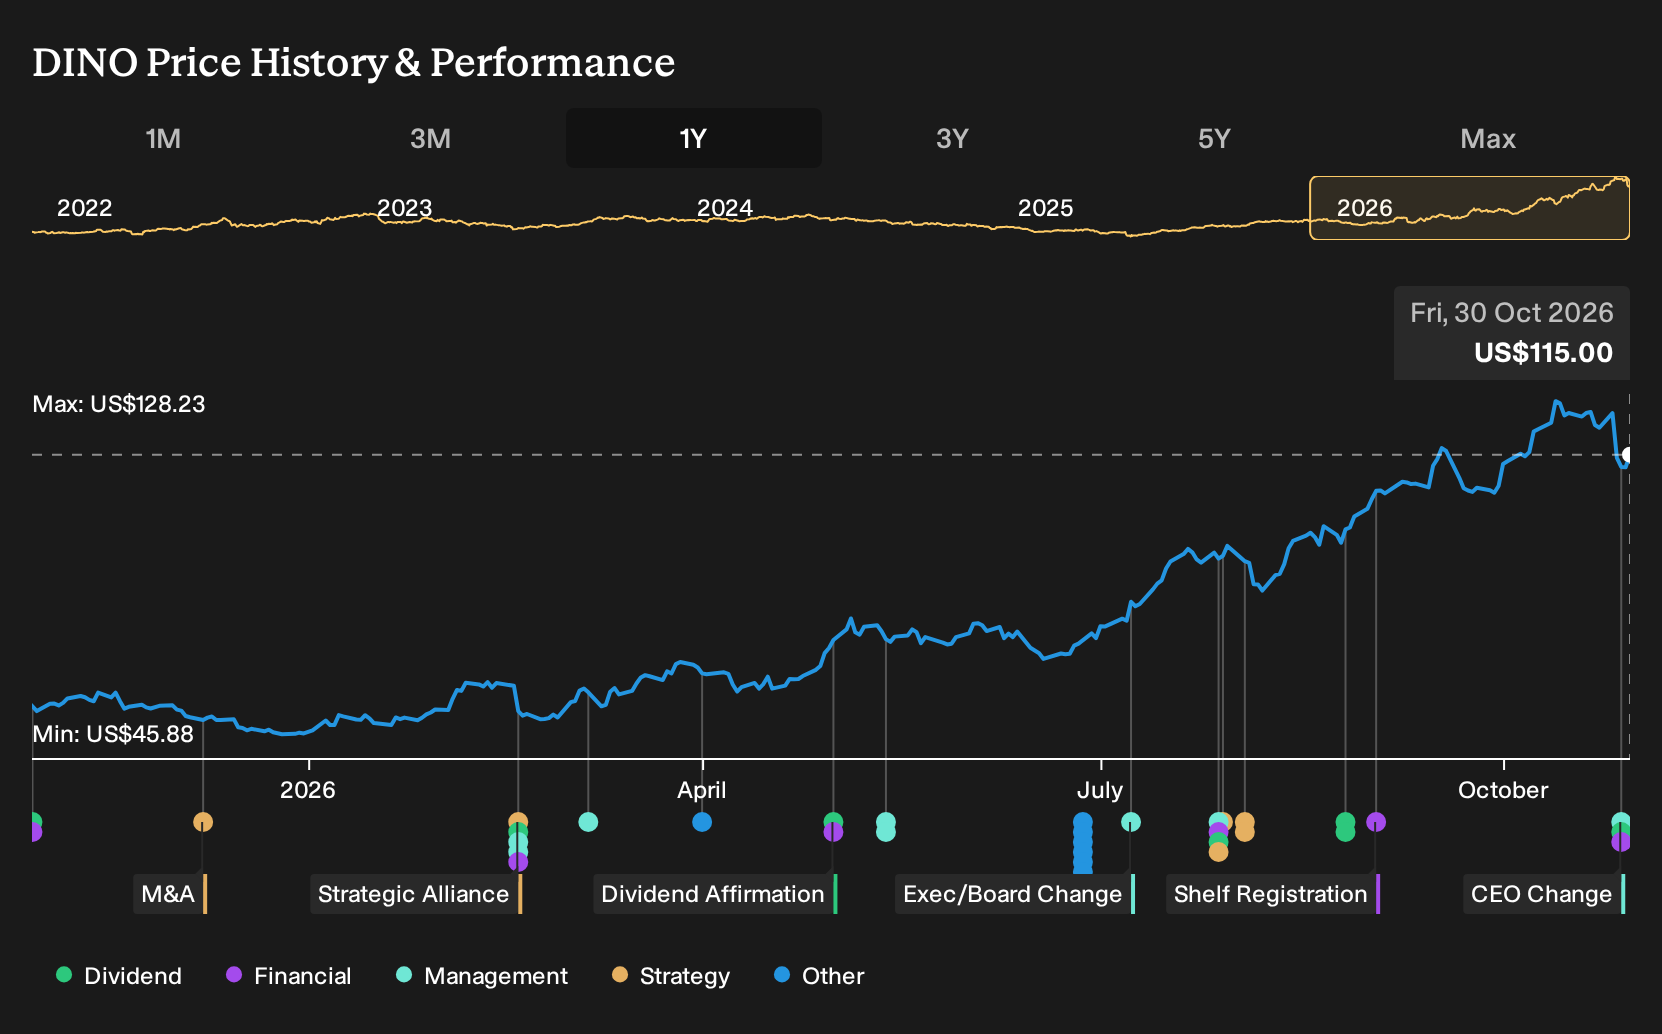
- HF Sinclair reported third quarter 2026 sales of US$10.857b and net income of US$2.015b, alongside a US$0.525 per share quarterly dividend, a completed US$281.56m buyback tranche, and confirmation of Steve Ledbetter as incoming CEO from January 1, 2027.
- The company paired very strong year over year earnings per share from continuing operations with ongoing capital returns and a planned separation of its Lubricants & Specialties segment. This gives investors a clearer view of how HF Sinclair is shaping its future business mix.
- This article examines how HF Sinclair's investment narrative is influenced by this earnings surge and the planned Lubricants separation.
Scan how HF Sinclair's earnings surge and capital returns compare with a hand picked 29 high quality undervalued stocks that also pair strong balance sheets with shareholder friendly cash deployment.
What Is HF Sinclair's Investment Narrative?
Owning HF Sinclair means you are effectively betting that this refining centered energy platform can keep turning volatile fuel markets into strong cash generation, then recycling a good chunk of that money into both projects and payouts. The latest quarter, with US$10.857b in sales, US$2.015b in net income and basic EPS from continuing operations of US$11.38, underlines how powerful the current refining backdrop has been. That kind of earnings surge can sharpen near term catalysts around further capital returns and support the regular US$0.525 dividend, even with an historically uneven payout record.
The confirmed CEO transition to Steve Ledbetter and progress toward separating Lubricants & Specialties put execution squarely in focus. Refining, renewables and midstream remain capital intensive and operationally complex, so the real question for you is whether this management team can sustain high quality earnings without leaning too hard on a very strong pricing window. Analysts currently flag potential earnings declines over the next few years, which means the recent buybacks and segment reshaping matter most if they help HF Sinclair run a leaner, more resilient system when margins cool.
Even so, there is a less obvious pressure point in the story that only shows up once you look closely at ...
There's only one way to know the right time to buy, sell or hold HF Sinclair. Head to Simply Wall St's company report for the latest analysis of HF Sinclair's Fair Value.
Exploring Other Perspectives
One alternate angle on HF Sinclair is pure earnings risk. The most bearish analysts were penciling in revenue of about US$26.8b and earnings of roughly US$1.2b by 2029, with EPS near US$6.8. That is far below more optimistic views. Use these gaps to test your own assumptions as this new quarter feeds into updated models.
Explore 4 other HF Sinclair fair value estimates, including one that suggests as much as 27% downside from the current price!
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your HF Sinclair research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for HF Sinclair. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HF Sinclair's overall financial health at a glance.
Looking For More Investment Ideas Beyond HF Sinclair?
If HF Sinclair's latest quarter has sharpened your appetite for ideas, use that momentum to widen your opportunity set with the Simply Wall St Screener. You can quickly filter for different return profiles, risk levels and balance sheet setups that fit how you like to invest.
- For investors who want potential growth with tighter risk controls, consider stocks screened as 30 resilient stocks with low risk scores that may better match a more conservative approach.
- If your focus tilts toward resilient finances and durable balance sheets, filter for companies in the list of solid balance sheet and fundamentals (25 results) to zero in on businesses that prioritize financial strength.
- When you are hunting for ideas that the market may be overlooking, broaden your shortlist with a curated group of 18 high quality undiscovered gems that pair quality fundamentals with lower visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com