


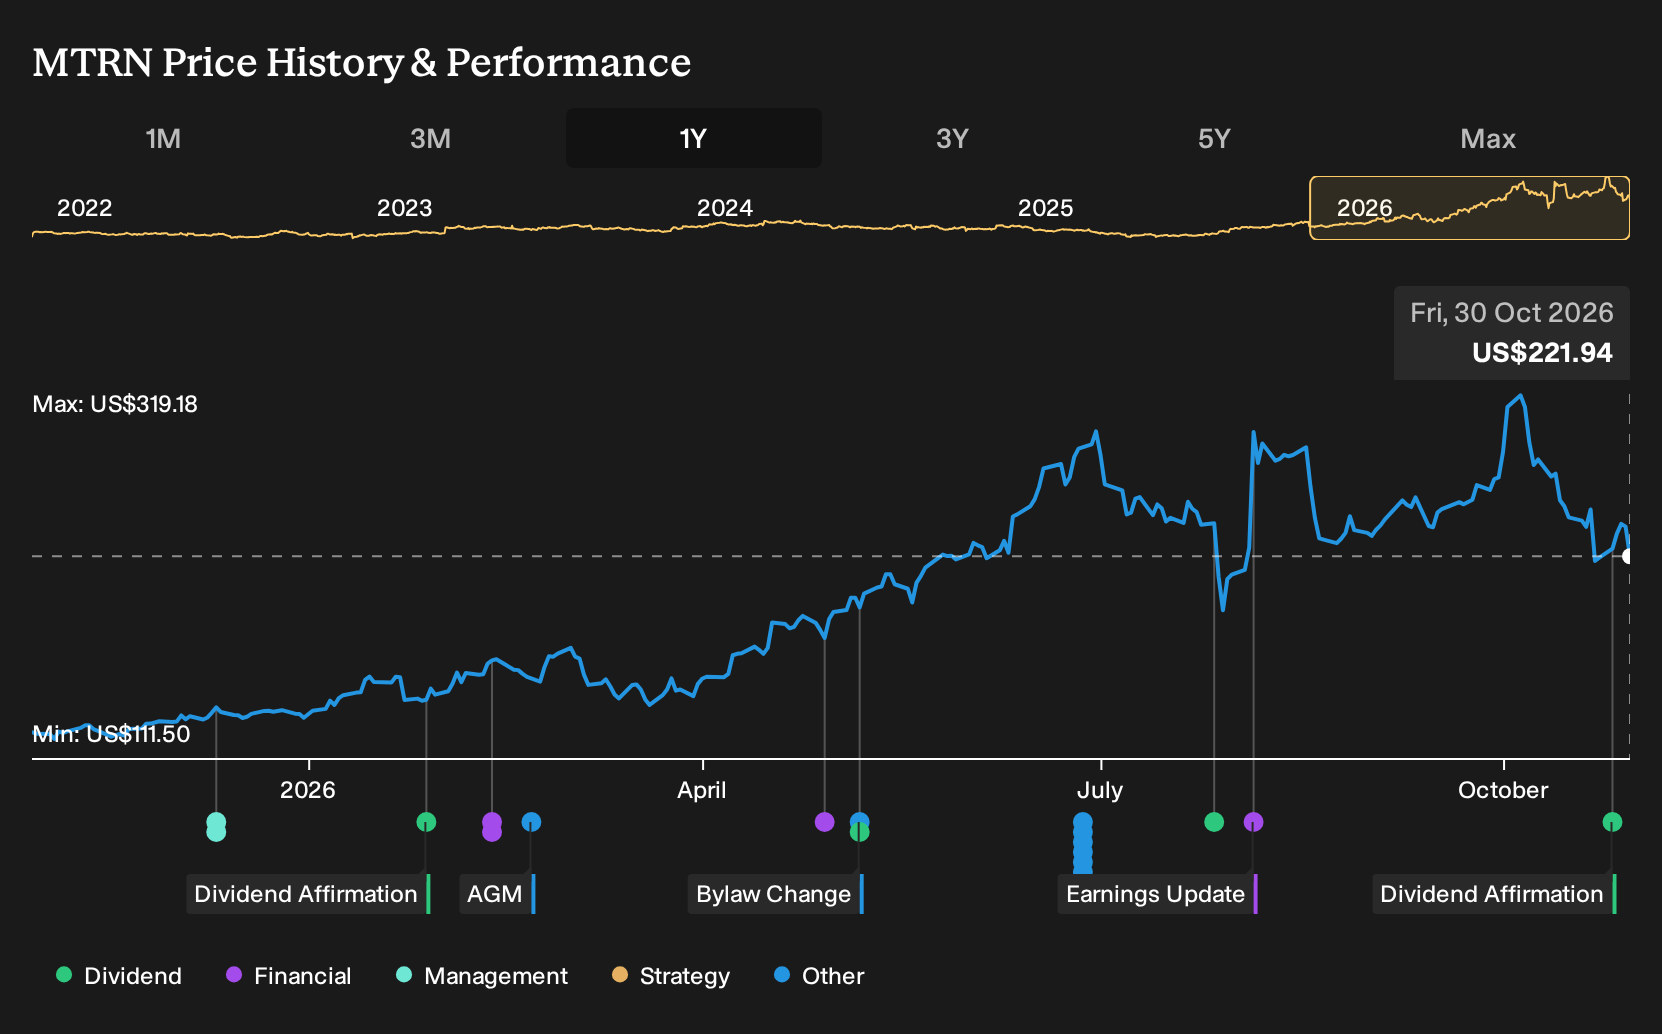
- Materion Corporation declared a fourth quarter 2026 dividend of US$0.145 per share, payable on 4 December 2026 to shareholders of record on 19 November 2026, alongside very strong year over year EPS growth from a previously low base.
- The combination of a cash dividend and very large EPS improvement highlights Materion’s focus on both returning capital and strengthening underlying earnings power from its operations.
- We will look at how Materion's investment narrative is affected by this sharp EPS improvement from a previously low earnings base.
Scan how Materion’s mix of dividend income and sharp EPS improvement compares with other hand-picked industrials in the list of solid balance sheet and fundamentals (25 results).
Materion Investment Narrative Recap
To own Materion, you need to believe its advanced materials will continue to find high value uses in semiconductors, aerospace, defense and energy projects, and that the current backlog converts cleanly into value added revenue. The sharp EPS rebound suggests better execution and mix. The key near term swing factor is whether AI related chip and data center demand holds up at current levels.
The biggest operational risk is how concentrated that strength is in a few end markets and large customers. Any pause in defense, space or data center programs would quickly pressure visibility and margins. The latest dividend decision does not materially change those near term catalysts or risks.
The recent fourth quarter 2026 dividend declaration of US$0.145 per share is the most relevant update here because it sits next to very large year over year EPS growth from a previously weak base. That combination points back to the core question: Can Materion keep converting its Electronic Materials, Performance Materials and Precision Optics backlog into higher margin earnings?
A continued dividend requires ongoing cash generation, so this payout ties directly into execution risk. If AI linked semiconductor orders, aerospace and defense awards or energy infrastructure projects lose momentum, both earnings and future distributions could come under pressure. The announcement simply indicates that the board currently views the earnings profile as sufficient to support a regular cash return.
Materion's narrative projects US$3.0b revenue and US$296.8 million earnings by 2029. This assumes 12.4% yearly revenue growth and an earnings increase of about US$206.7 million from US$90.1 million today.
Uncover why Materion's fair value indicates a 37% potential upside to its current price before this discount narrows.
Exploring Other Perspectives
Some of the most optimistic analysts frame Materion around long run defense and energy demand rather than today’s AI surge. Before this dividend news, that group was already penciling in about US$3.1b of revenue and US$310.1 million of earnings by 2029, based on the information provided. You can use this more upbeat script as a foil to test your own view, then explore how forecasts might shift once this latest payout is fully reflected.
Explore 2 other Materion fair value estimates, including one that suggests as much as 66% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? It can be difficult to achieve extraordinary investment returns by simply following the herd, so consider trusting your own analysis.
- A great starting point for your Materion research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Materion. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Materion's overall financial health at a glance.
Looking for more investment ideas beyond Materion?
If Materion's mix of earnings power and income appeal has caught your attention, it can help to compare it with other opportunities that offer different risk and return profiles using the Simply Wall St Screener.
- For investors who want potential mispricing with financial strength on their side, scan a curated 29 high quality undervalued stocks that combines earnings quality with balance sheet support.
- If steady income matters to you, focus on companies that prioritize consistent cash returns through a 5 dividend fortresses built around higher-yielding payers.
- For a lower volatility starting point, concentrate on businesses that score well on stability and financial resilience in a 30 resilient stocks with low risk scores tailored for defense-minded investors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com