


The UK Government's Your First Home scheme is back in focus, and Persimmon (LSE:PSN) sits near the center of that conversation for investors tracking listed housebuilders.
Persimmon’s share price has cooled in recent weeks, with a 30 day share price return of down 5.3% and year to date performance lower by 8.4%. However, a 90 day share price gain of 12.5% and 1 year total shareholder return of 8.6% suggest momentum has been rebuilding from earlier in the year as investors weigh the Your First Home scheme against longer term housing demand and valuation questions.
Scan how Persimmon compares to other potential beneficiaries of housing demand support by reviewing our hand picked list of list of solid balance sheet and fundamentals (10 results)
Persimmon has already delivered a solid rebound over 90 days, yet the five year share price record still looks weak. Is the bigger opportunity now in front of the stock or already in the rear view mirror as the Your First Home boost gets priced in?
Most Popular Narrative: 10% Undervalued
Against Persimmon’s last close of £12.46, the most followed narrative pins fair value at £13.83, which points to a modest valuation gap and puts the focus firmly on how the business converts UK housing demand and Your First Home tailwinds into future earnings and cash flows.
Recent and ongoing government planning reforms, as well as potential future homeownership incentives, are unlocking new site acquisitions and outlet openings (for example, 7% more plots with planning permission and a pipeline of 300 outlets within 18 months), positioning Persimmon to disproportionately capture market share and drive future top-line growth.
See why 94 investors see Persimmon as 10% undervalued.
Result: Fair Value of £13.83 (UNDERVALUED)
Still, that recovery story for Persimmon leans heavily on housing affordability improving and build costs easing, so any squeeze on buyers or renewed cost pressure could quickly challenge it.
Find out about the key risks to this Persimmon narrative.
Another View: Persimmon Through A Cash Flow Lens
While the analyst fair value pins Persimmon at £13.83 and frames the shares as modestly undervalued, the Simply Wall St DCF model paints a different picture. On that cash flow view, the stock at £12.46 sits above an estimated value of £9.10, so it screens as overvalued. Which story do you think fits Your First Home risk and reward better?
Look into how the SWS DCF model arrives at its fair value.
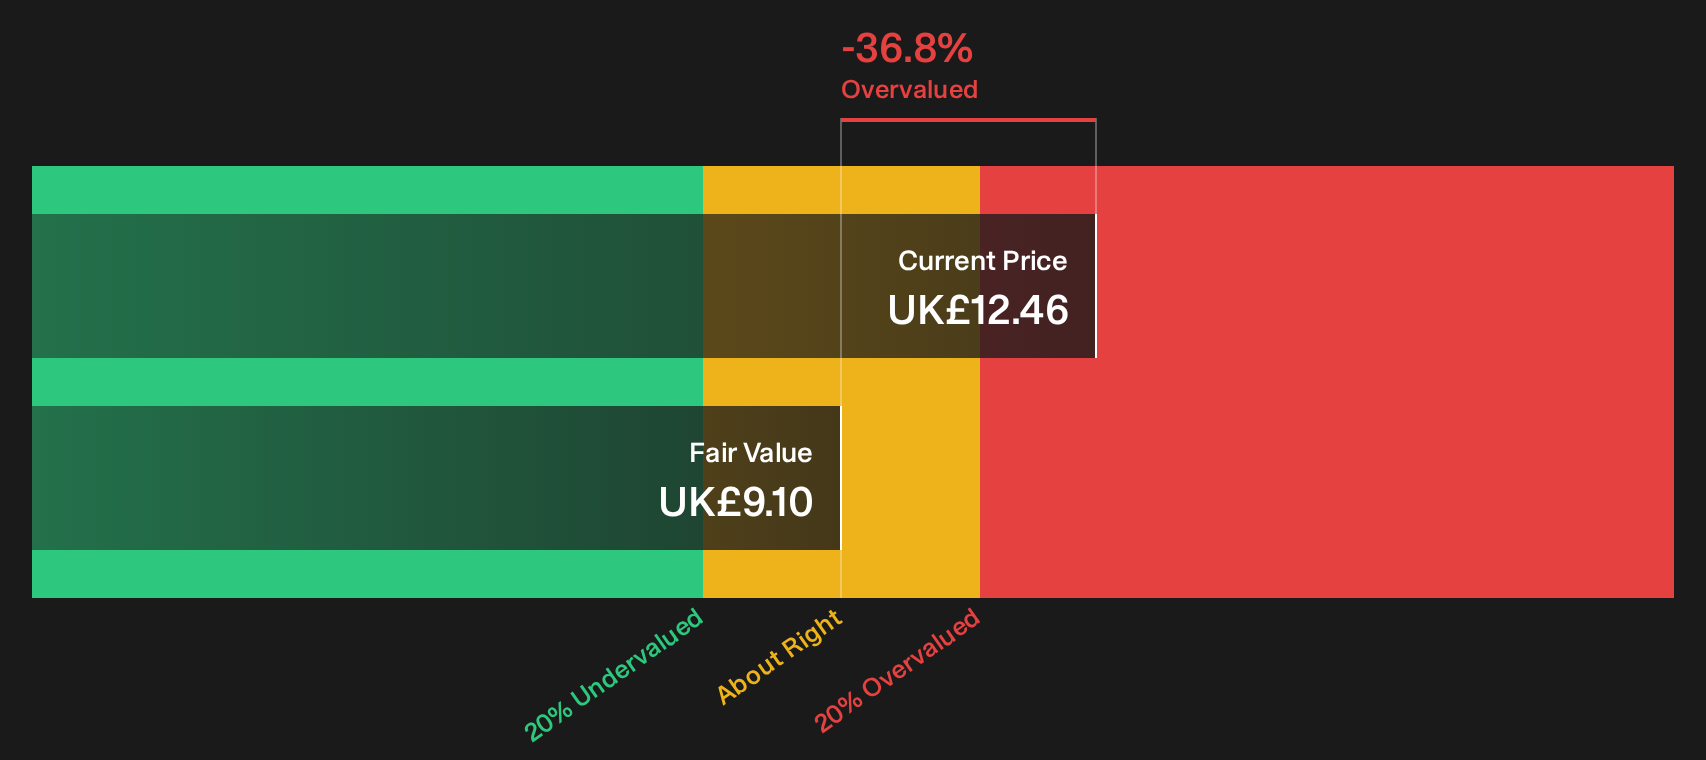
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Persimmon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Persimmon feels familiar, consider taking time to explore the situation while sentiment is still forming and examine both sides of the story. Balance your view by weighing the 3 key rewards and 1 important warning sign
Looking for more ideas beyond Persimmon?
If Persimmon has sharpened your focus on where capital works hardest, widen the lens and use the Simply Wall St screener to hunt for the next opportunity.
- Target resilient balance sheets and stress test your downside by scanning our 5 resilient stocks with low risk scores that aim to hold up when conditions get tougher.
- Hunt for quality at a discount by reviewing a curated 12 high quality undervalued stocks that pair solid fundamentals with room for sentiment to catch up.
- Build an income focused shortlist by zeroing in on 5 dividend fortresses designed to combine higher yields with businesses that aim to sustain payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com