


Europe’s benchmark natural gas price recently moved above 101 euros per megawatt hour, which keeps pressure on energy costs and business input prices across the region. British growth companies that can still invest, expand and retain staff in this backdrop may attract more attention. This piece looks at three high growth UK stocks where insiders hold meaningful stakes, and explains why that alignment can matter for long term investors.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders and external analysts both see room for further progress. However, if you want the absolute best, these 6 high growth high conviction stocks are the cream of the crop.
Playtech (LSE:PTEC)
Overview: Playtech is a gambling software group that supplies online casino, live casino, and sportsbook platforms to operators worldwide while also running selected B2C gaming brands.
Operations: Playtech generates most of its €801.7 million revenue from B2B activities at €735.5 million, with €64.8 million from Sun Bingo and other B2C operations and smaller HAPPYBET and intercompany items across the UK, Europe, Latin America and other international markets.
Market Cap: £990 million
Playtech sits at the sweet spot of this screener’s theme, where high insider commitment meets a scalable online casino and sports betting platform that can turn new content and partnerships into recurring licensing income.
"The structured agreements and equity stakes model, which already contributes €34m of adjusted EBITDA investment income in half a year and includes a Hard Rock Digital stake revalued at about €250m, creates room for Playtech to recycle cash flows into further equity-linked partnerships. These could add a separate stream of mark to market gains and dividends on top of software revenue and earnings."
What happens to Playtech’s earnings power if a single assumption about how quickly these partnerships convert into cash flow shifts either way?
If that timing question matters to you, read the full narrative for Playtech for how Playtech’s equity deals, cash generation and insider alignment could accelerate or stall from here.

Greencore Group (LSE:GNC)
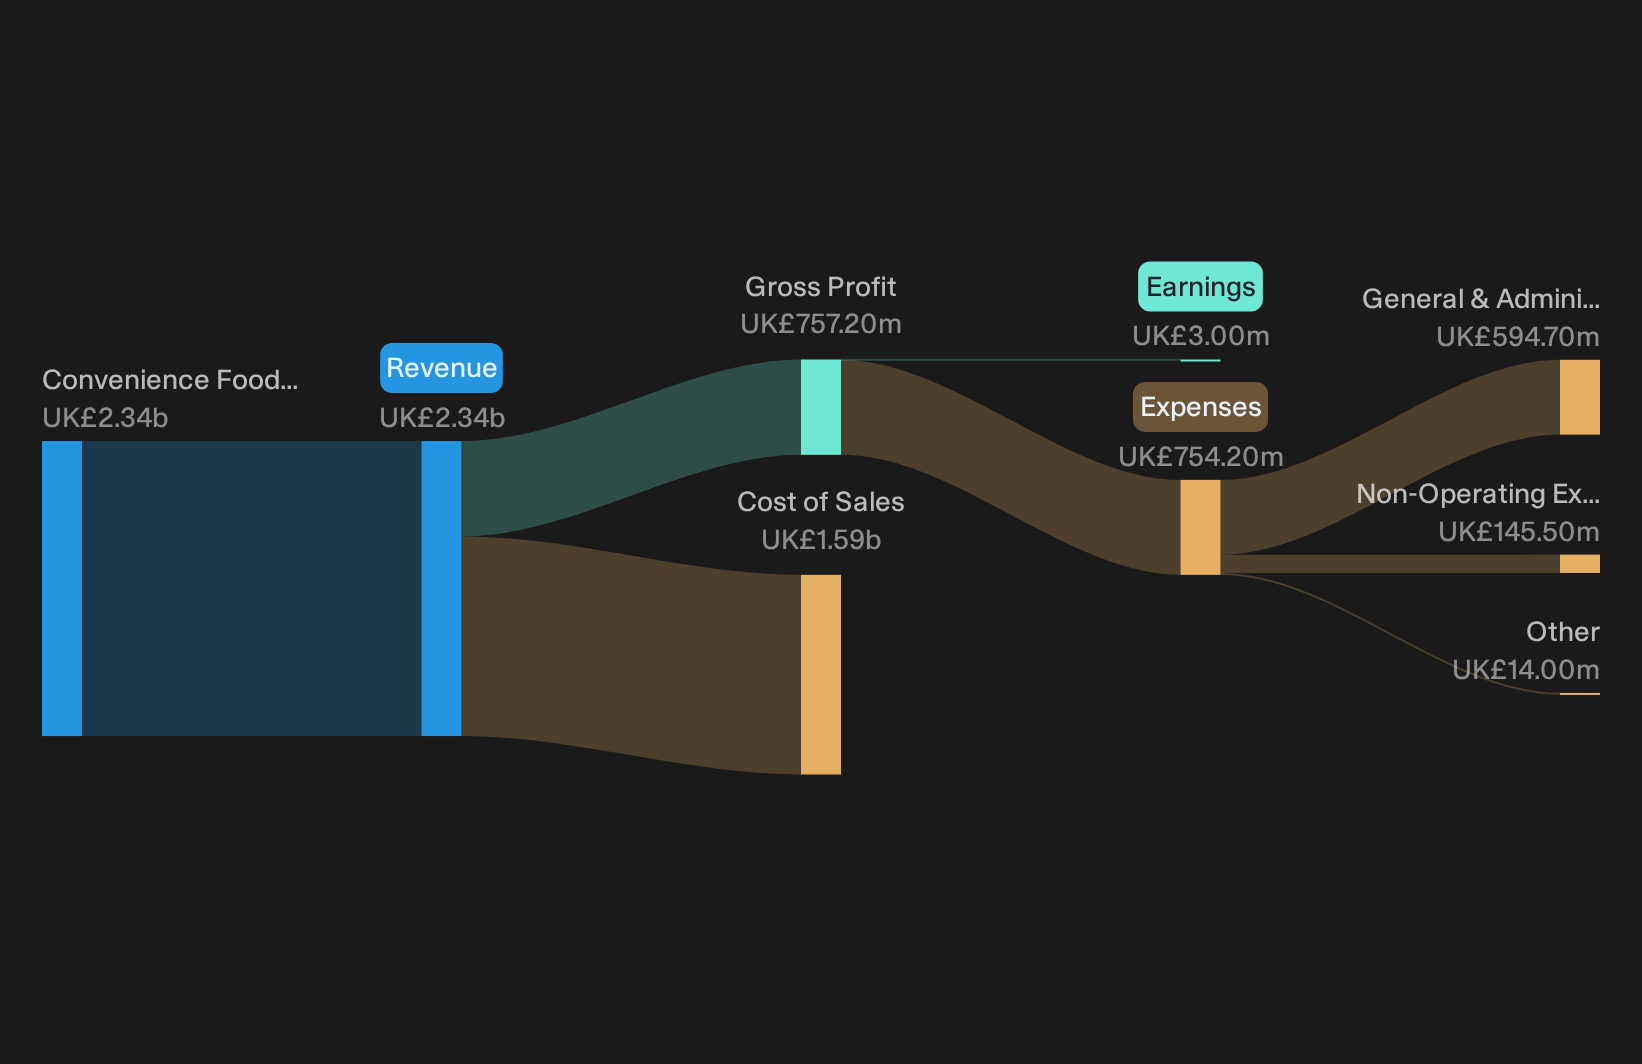
Overview: Greencore Group is a Dublin headquartered producer of sandwiches, salads and other convenience foods for UK and Irish retailers and travel outlets, with high insider ownership aligning management to this growth focused theme.
Operations: Greencore Group generates £2.3b in revenue from its Convenience Foods UK & Ireland division, centred on chilled and ambient ready to eat products.
Market Cap: £2.3b
Greencore Group matters for this screener because its convenience food shelves sit exactly where retailers, commuters and at home eaters are still trading time for ready to eat options.
"Operational excellence programs and a five year automation roadmap, which have already lifted units per labour hour and target at least 10% direct labour savings over time, can continue to support higher operating margins and earnings as more projects are rolled out across Greencore Group sites."
What happens to Greencore Group’s reshaped earnings profile if one crucial pressure point in its cash generation story fails to improve meaningfully?
If that pressure point has you weighing how much further the turnaround can run, the full narrative for Greencore Group shows where Greencore Group’s reset could accelerate or stall next.
TBC Bank Group (LSE:TBCG)
Overview: TBC Bank Group is a London based financial group that runs universal and digital banks across Georgia, Uzbekistan and nearby markets, with growth closely tied to its online consumer finance and BNPL platforms.
Operations: TBC Bank Group generates GEL 2.7b revenue from Georgian Financial Services and GEL 432 million from Uzbekistan Operations, with minimal contributions from Other Operations and Eliminations.
Market Cap: £2.5b
TBC Bank Group matters for this fast growing, high insider ownership screen because its digital banking and BNPL engines sit at the intersection of rising online engagement, higher fee consumer lending and management’s growth ambitions.
"The ongoing shift in Uzbekistan from a loan book dominated by unsecured cash loans toward business loans, credit cards, auto loans and secured SME lending is expected to diversify revenue streams and support a more balanced net interest margin over time. Rapid growth in Uzbekistan payment volumes and card issuance, alongside the integration of a large classifieds platform with millions of monthly users, is building a wider ecosystem that can feed loan growth and transaction based income."
What happens to TBC Bank Group’s margin story if a single unseen pressure in that expanding ecosystem tilts either toward higher risk or stronger pricing power?
That hidden tilt in TBC Bank Group’s ecosystem sits at the heart of the full narrative for TBC Bank Group, which maps where growth could accelerate or risk quietly build.

Seeking Fresh Alternatives Before Others?
Fresh ideas often move first. Breakout stories can gain momentum while they are still under the radar. Do not get caught falling behind the data. Consider your options carefully.
- Scan for dependable income while rates and inflation keep shifting using a curated set of 5 dividend fortresses to explore opportunities before yield hunters focus on them.
- Target potential enablers of AI infrastructure, power demand and data growth through a focused group of 39 power grid technology and infrastructure stocks to build exposure as trends develop.
- Look for potential early compounders with resilient balance sheets in a carefully filtered 5 resilient stocks with low risk scores while prices may still reflect limited attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com