


Why Ermenegildo Zegna’s Latest Revenue Update Matters
Ermenegildo Zegna (ZGN) drew fresh attention on 22 October 2026 after reporting unaudited revenues for the third quarter and nine-month period that were higher than the same stages a year earlier.
The fresh revenue update comes as Ermenegildo Zegna’s share price stands at $13.49, reflecting a strong year-to-date share price return of 29.34% and a 1-year total shareholder return of 33.52%. This performance contrasts with weaker 90-day momentum, during which the share price has declined 8.29%.
Scan how Ermenegildo Zegna’s revenue momentum compares with other potential opportunities by reviewing the hand picked 29 high quality undervalued stocks that pair balance sheet strength with cash flow support.
Ermenegildo Zegna has delivered higher revenue and a strong 1 year return, yet the share price has slipped over the past three months. Is most of the rerating already in the rear view mirror, or does valuation still leave room ahead?
Most Popular Narrative: 6.9% Undervalued
The most followed narrative currently values Ermenegildo Zegna at $14.48 per share, a touch above the latest close at $13.49. This frames the recent revenue update against expectations for a gradually improving earnings mix.
The ongoing shift at Ermenegildo Zegna toward a retail first, DTC heavy model, with DTC contributing 85% to 86% of branded revenues while wholesale is deliberately reduced, continues to support a higher gross margin mix and operating leverage that can benefit group EBIT.
Geographic reweighting toward the Americas and higher spending clients in Greater China, where both regions show double digit or high single digit organic DTC growth, points to further top line and EBIT expansion as these markets build a larger share of Ermenegildo Zegna revenues.
See why 9 investors see Ermenegildo Zegna as 7% undervalued.
Result: Fair Value of $14.48 (UNDERVALUED)
Still, the bullish Ermenegildo Zegna story can crack if Greater China spending softens again or if Thom Browne’s wholesale reset continues to drag on margins.
Find out about the key risks to this Ermenegildo Zegna narrative.
Another View: Ermenegildo Zegna Looks Expensive On Earnings
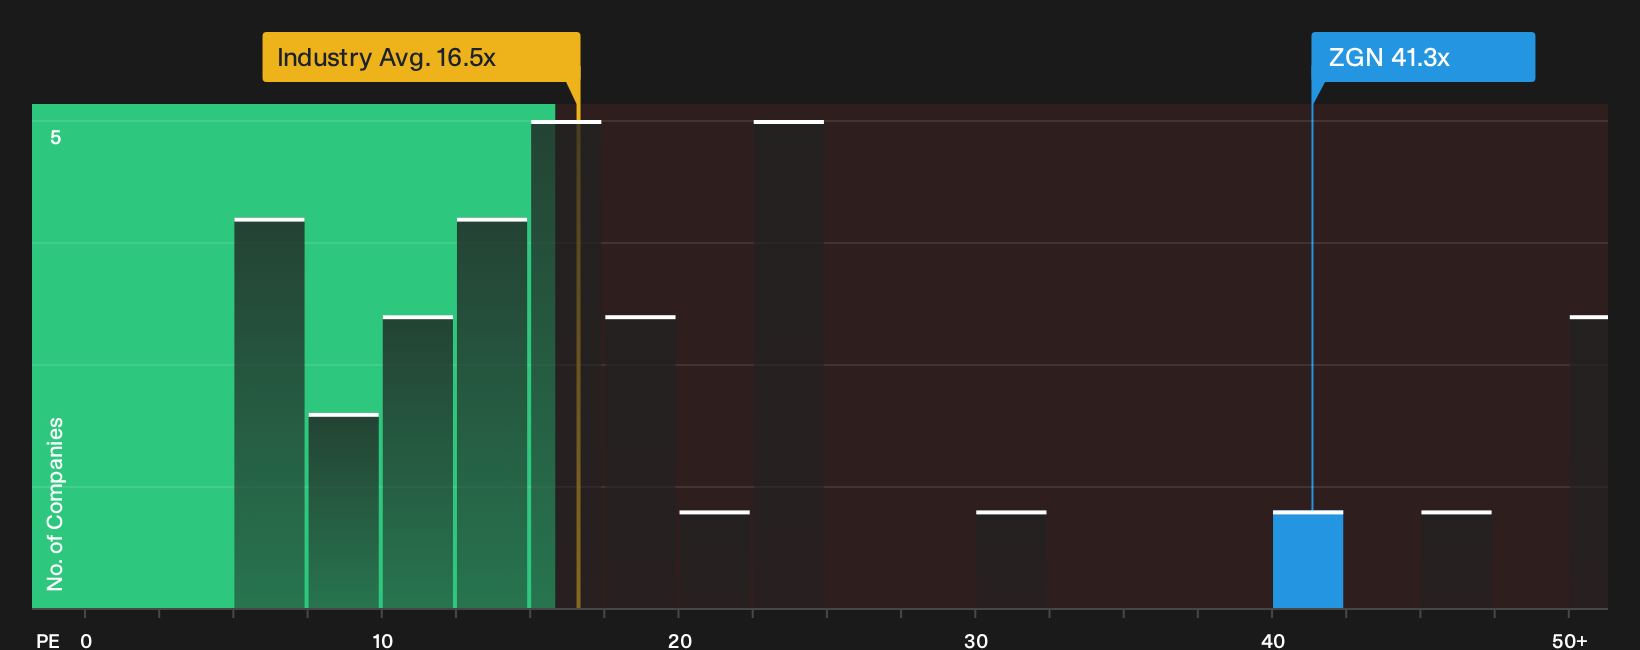
The analyst narrative leans on a fair value of $14.48 per Ermenegildo Zegna share, yet the current P/E of 41.3x paints a tougher picture. That multiple is well above the US Luxury industry at 16.5x, the peer average at 26.5x, and even the fair ratio of 24.9x that the market could move toward.
Such a gap suggests meaningful valuation risk if sentiment cools. The question for investors is whether the growth story justifies paying this much more for each dollar of earnings, or if patience is the better call.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Ermenegildo Zegna’s valuation can spark debate, so act quickly and review the underlying metrics yourself before sentiment shifts again. To see exactly what optimistic investors are focusing on in the reward profile, start with the 1 key reward.
Looking for more Ermenegildo Zegna style ideas?
If Ermenegildo Zegna’s setup has you thinking harder about valuation and quality, now is the moment to widen your search before the next wave of opportunities moves.
- Target businesses where quality and price work together by scanning a 29 high quality undervalued stocks that highlights financially strong companies trading below their implied worth.
- Strengthen potential downside protection by reviewing a list of solid balance sheet and fundamentals (25 results) that surfaces businesses with healthier debt levels and sturdier financial footing.
- Spot potential future leaders early by using a 18 high quality undiscovered gems that surfaces under-followed companies with robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com