


Annaly Capital Management (NLY) just swung to a third quarter net loss of US$1.00b, compared with net income of US$832.45m a year earlier. This sharp reversal puts earnings quality under the microscope for shareholders.
The earnings shock appears to be landing on a stock that was already under pressure, with the share price at US$18.23 and a 90 day share price return that has fallen 19.76%, contributing to a year to date share price decline of 20.39%. Over a longer stretch, the picture looks different, with a 3 year total shareholder return of 59.37% and a 5 year total shareholder return of 4.26%. Taken together, these figures suggest the recent weakness may reflect a reset in expectations and perceived risk around Annaly Capital Management after this latest quarterly result.
Stress test your income REIT exposure by comparing Annaly Capital Management with our hand picked list of 5 dividend fortresses that have yields and include additional filters around balance sheet strength.
So is this drop telling you something new about Annaly Capital Management’s earnings power, or has sentiment simply swung too far on one tough quarter, setting up a valuation gap to examine next?
Price-to-Earnings of 15.1x: Is it justified?
Annaly Capital Management changes hands at a P/E of 15.1x, while our estimate of a fair P/E sits higher at 23.1x. The shares last closed at $18.23, so the question is whether the current pricing reflects a cautious view of future earnings or an opening for investors who see the story differently.
The P/E ratio compares what you pay today for each dollar of forecast profit. For a mortgage REIT like Annaly Capital Management, that matters because earnings quality, rate sensitivity, and balance sheet structure all feed into how sustainable those profits look over time.
Here, the picture is mixed. The stock is assessed as good value relative to the 23.1x fair P/E level, which implies the market is assigning a lower multiple than the regression based fair ratio could support. At the same time, the P/E of 15.1x screens as expensive compared with both the peer average of 12x and the wider Global Mortgage REITs group at 10.5x, which signals that investors are already paying a premium multiple versus much of the sector and would need to be comfortable with that trade off.
Explore the SWS fair ratio for Annaly Capital Management.
Result: Price-to-earnings of 15.1x (ABOUT RIGHT)
Still, the recent net loss and the share price slide over the past 90 days and year to date keep the risk of further sentiment shocks firmly on the table.
Find out about the key risks to this Annaly Capital Management narrative.
Another view on Annaly Capital Management’s value
The P/E work suggests Annaly Capital Management might be on the cheaper side, while the SWS DCF model points to something stronger. On that framework, NLY at $18.23 sits below an estimated future cash flow value of $27.68, which screens as undervalued. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
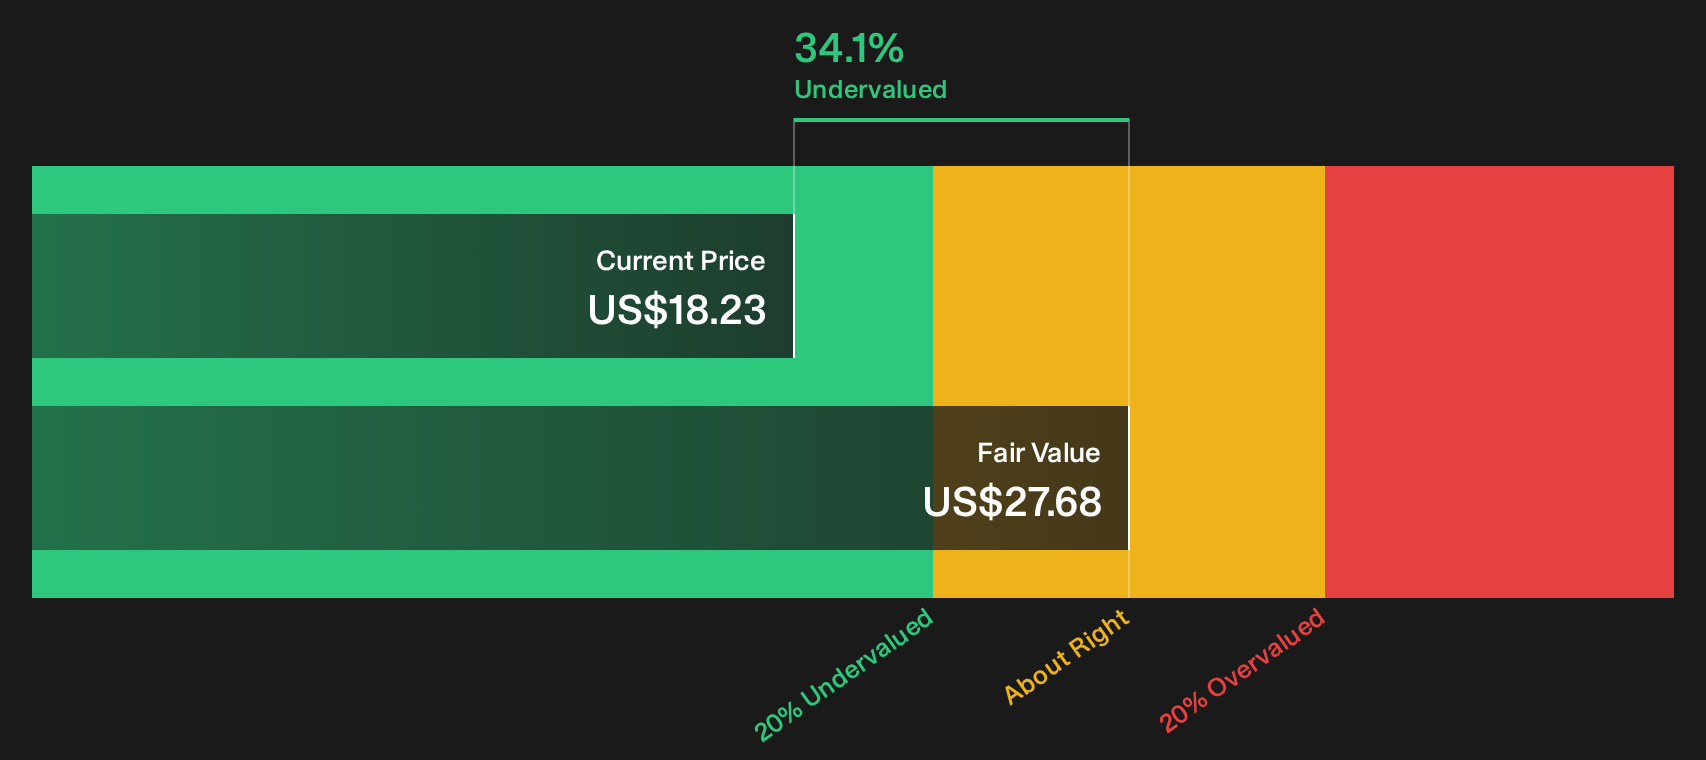
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Annaly Capital Management for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling torn between the risks flagged in Annaly Capital Management’s latest numbers and the potential rewards highlighted earlier in the piece? Consider reviewing the underlying data for yourself, and pressure test your own thesis against the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Annaly Capital Management?
Once you have a view on Annaly Capital Management, the next smart move is lining up fresh ideas that match your risk tolerance and income goals.
- Target quality at a discount by scanning companies that combine solid fundamentals with attractive pricing through the 29 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can help you focus on businesses with financial strength at their back.
- Get ahead of the crowd by hunting through 18 high quality undiscovered gems that may not yet be on most investors' radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com