


Fund disclosures around DCC Energy (LSE:DCC) have picked up, with Millennium, Balyasny, Qube and Dimensional all reporting opening positions in the stock under Irish Takeover Panel Rule 8.3 in late October 2026.
Despite the flurry of Rule 8.3 disclosures, DCC Energy’s share price has held around £64.45. A 41.84% year to date share price return and a 33.72% one year total shareholder return point to momentum that has been building rather than fading.
Scan how professional flows into DCC Energy compare with other potential breakouts across our hand picked 12 high quality undervalued stocks that also pair momentum with fundamental support.
DCC Energy now trades close to analyst targets, yet carries an intrinsic value estimate that suggests almost half the worth is still on the table. Is the market’s caution about this recent run justified or mispriced?
Most Popular Narrative: Fairly Valued
DCC Energy’s most followed valuation storyline pegs fair value almost exactly in line with the recent £64.45 close. This puts the spotlight on how the reshaped energy focused group actually performs rather than on any obvious pricing gap.
The current valuation suggests DCC Energy is fairly valued and that the market already reflects a continued combination of disciplined capital returns, such as the £800m shareholder payout, together with the balance sheet capacity created by net debt at 0.9x EBITDA to fund further energy acquisitions.
See why 29 investors see DCC Energy as 0% overvalued.
Result: Fair Value of £64.20 (ABOUT RIGHT)
Still, weak Energy Services profitability and softer Energy Products volumes linked to warm weather and demand could continue to chip away at the DCC Energy fair value story.
Find out about the key risks to this DCC Energy narrative.
Another View: What Multiples Say About DCC Energy
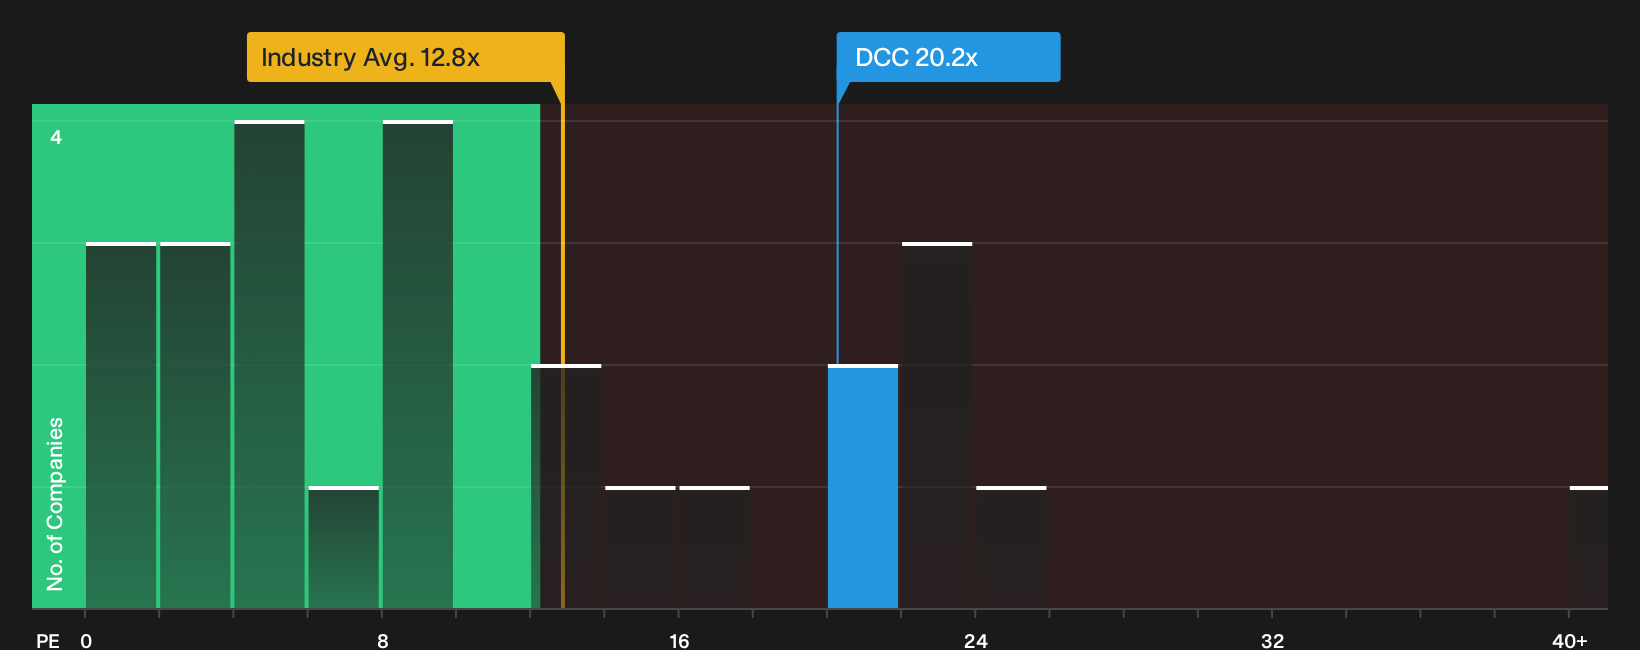
DCC Energy screens as cheap on some metrics and expensive on others. The stock trades on a P/E of 20.2x, below the peer average of 21.1x but well above the European Oil and Gas sector on 13.4x. The fair ratio points to 23.3x as a level the market could move toward over time. That mix of discount to peers but premium to the wider industry raises the question of whether the real risk is paying up for quality or underestimating how far the rerating has already run.
Before leaning too heavily on any single comparison, it is worth checking how these P/E gaps stack up against earnings quality, growth forecasts and your own margin of safety assumptions. It is then important to decide whether those numbers still feel comfortable if sentiment cools. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around DCC Energy is mixed, which makes this a moment to move fast and test the story against your own framework. To weigh those positives against your expectations, start with the 3 key rewards.
Looking for more investment ideas beyond DCC Energy?
If DCC Energy is already on your radar, broadening your watchlist now can help you spot the next potential opportunity before the crowd does.
- Hunt for mispriced quality by scanning our hand picked 12 high quality undervalued stocks that line up solid fundamentals with valuations that still look reasonable.
- Prioritise resilience with a list of solid balance sheet and fundamentals (10 results) so you can focus on businesses that pair financial strength with room to execute their plans.
- Get ahead of the crowd by tracking 5 high quality undiscovered gems that combine strong financials with lower visibility, before attention and liquidity catch up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com