


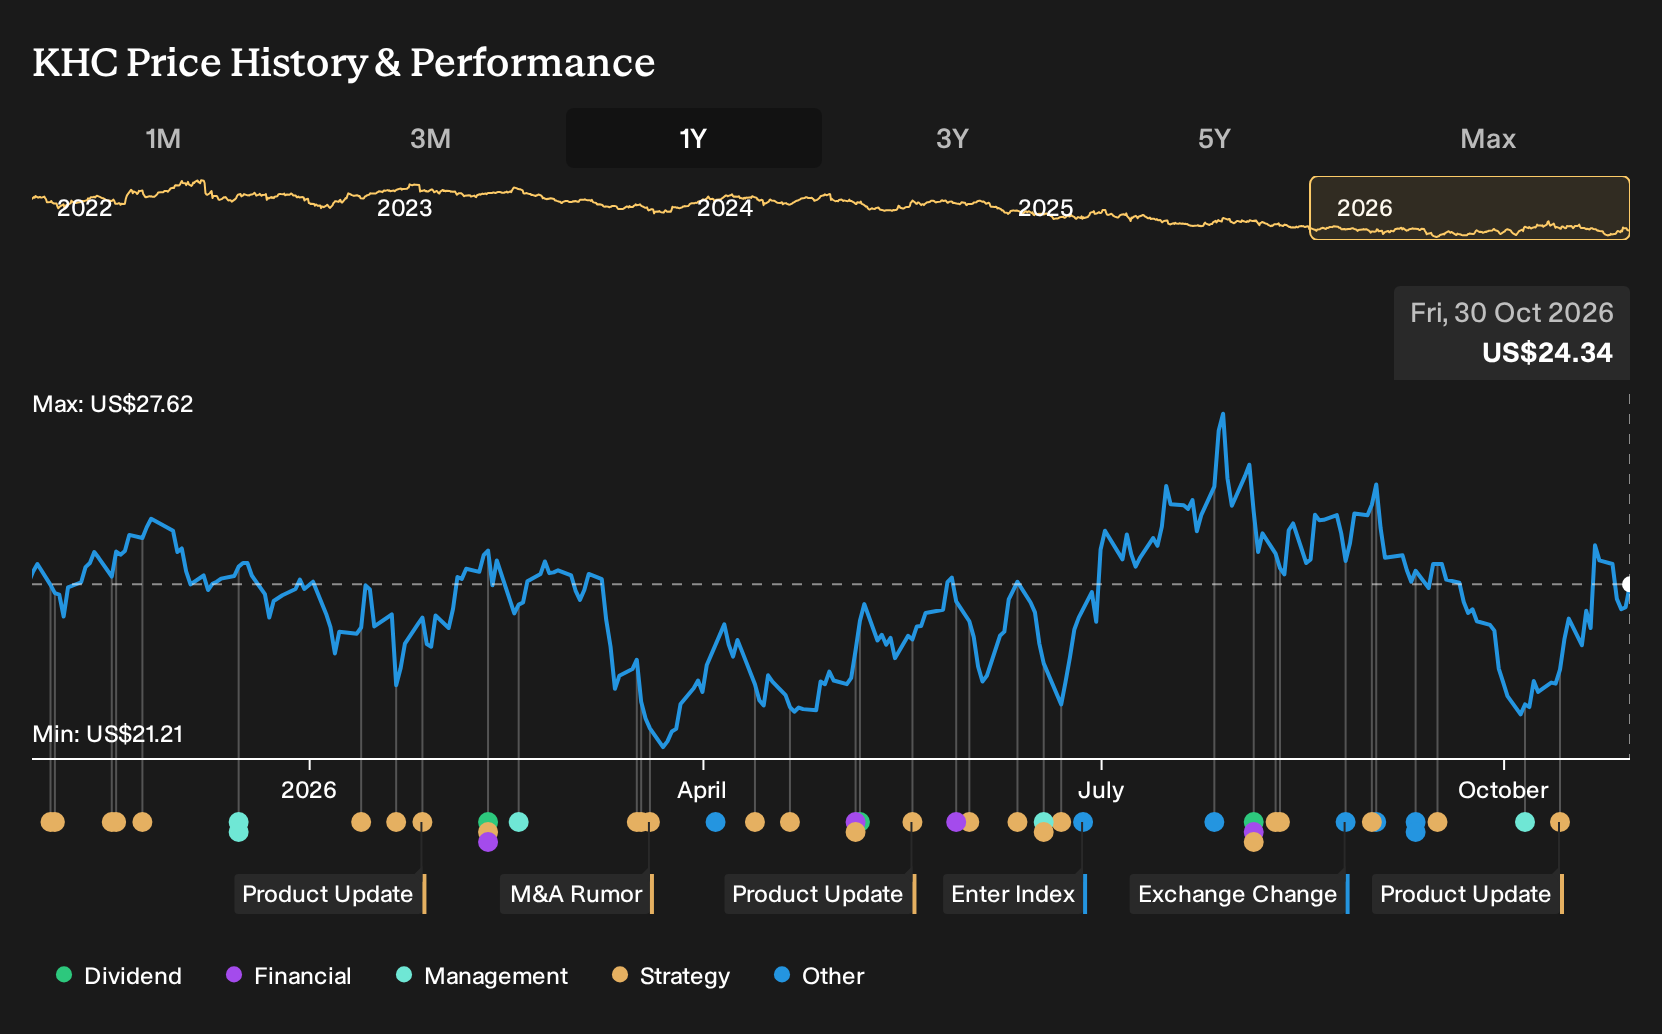
- Kraft Heinz is preparing to report quarterly earnings for the September 2026 period, with consensus expectations of $0.43 in earnings per share and a year over year decline in profitability.
- The slight downward revision to earnings estimates over the past month, alongside an uncertain earnings outcome, highlights ongoing pressure on Kraft Heinz's underlying profit engine.
- The upcoming results will show how Kraft Heinz's investment narrative could be influenced by softer earnings expectations and the risk of an earnings miss.
Scan beyond Kraft Heinz before earnings hit and compare its setup with a hand picked 29 high quality undervalued stocks that may offer sturdier profit engines and more resilient expectations.
Kraft Heinz Investment Narrative Recap
To own Kraft Heinz, you need to believe the heavy reinvestment in brands, product refreshes and emerging markets can eventually turn a mature packaged food portfolio into a steadier, volume driven earnings story. The near term earnings soft patch and expected year over year EPS decline test that idea, but they do not rewrite it on their own.
Right now, the swing factor is whether those US$700 million of extra marketing and the ongoing cost savings program can offset soft organic sales and changing consumption habits, including GLP 1 related volume pressure. The key risk is that North America retail demand and brand equity stay weaker for longer, which would keep revenue and profit trends under strain.
Recent commentary around full year guidance, including organic net sales expected to be down between 0.5% and 2.0% in 2026, is most relevant against this earnings update. That framing indicates management already sees a tougher topline backdrop, even as Kraft Heinz continues to spend more on advertising and product support to protect its brands.
For catalysts, that same outlook places more weight on productivity savings and portfolio adjustments toward zero sugar, hydration and lactose free products. If execution in these areas appears on track when earnings are reported, it can support the view that margin structure and category relevance are being rebuilt. If progress appears slow, it reinforces the risk that higher marketing spending and a richer dividend are relying on a balance sheet that already carries meaningful debt.
Kraft Heinz Earnings Path Assumptions
Kraft Heinz's narrative projects US$25.2b revenue and US$2.9b earnings by 2029. This assumes revenue stays broadly flat over the next few years and requires a US$6.3b earnings increase from current earnings of a US$3.4b loss.
Uncover why Kraft Heinz's fair value indicates a valuation gap that is broadly in line with its current price.
Exploring Other Perspectives
Some of the most optimistic Kraft Heinz analysts focus on rising free cash flow as the real swing factor. Before this earnings report, they were penciling in about US$25.4b of 2029 revenue and roughly US$4.6b of earnings. That is far above consensus, and your view may shift as fresh results challenge both stories.
Explore 10 other Kraft Heinz fair value estimates, including one that suggests as much as 154% potential increase from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Kraft Heinz research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kraft Heinz. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kraft Heinz's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kraft Heinz?
Once you have formed a view on Kraft Heinz, it can help to line it up against other potential opportunities that offer different mixes of quality, risk and income. The Simply Wall St Screener gives you a way to quickly narrow the market to stocks that better fit your own return goals and risk limits.
- If capital preservation sits high on your list, consider starting with a basket of companies that score well on stability and financial strength through the 30 resilient stocks with low risk scores.
- If income matters most to you, focus on cash generators that currently offer stronger yields and payout profiles via the 5 dividend fortresses.
- If you prefer to hunt for underappreciated opportunities, compare Kraft Heinz with a curated 18 high quality undiscovered gems that pair solid fundamentals with thinner analyst coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com