


AMETEK has rewarded long term shareholders, with the stock returning 76.7% over the past 5 years. The big question now is whether its current price still lines up with the earnings that support it. With fresh earnings news in the mix, the market is effectively asking how much profit power investors are paying for at today’s level.
- A 76.7% gain over 5 years has materially raised the bar for AMETEK, so any valuation check now hinges on how firmly those returns are backed by its earnings profile.
- Management recently lifted its future earnings expectations, which can support a higher price tag if those profits arrive on time and with healthy margins.
- Your read on AMETEK is one view; the desks covering it have another. See what analysts think AMETEK's shares could be worth.
For investors, the debate is whether AMETEK's current share price is adequately explained by the earnings it is generating today and is expected to produce in the years ahead.
If you want context around whether AMETEK's earnings-based valuation feels stretched or fair, compare it with other companies screened for 29 high quality undervalued stocks.
Does AMETEK Look Pricey on Earnings?
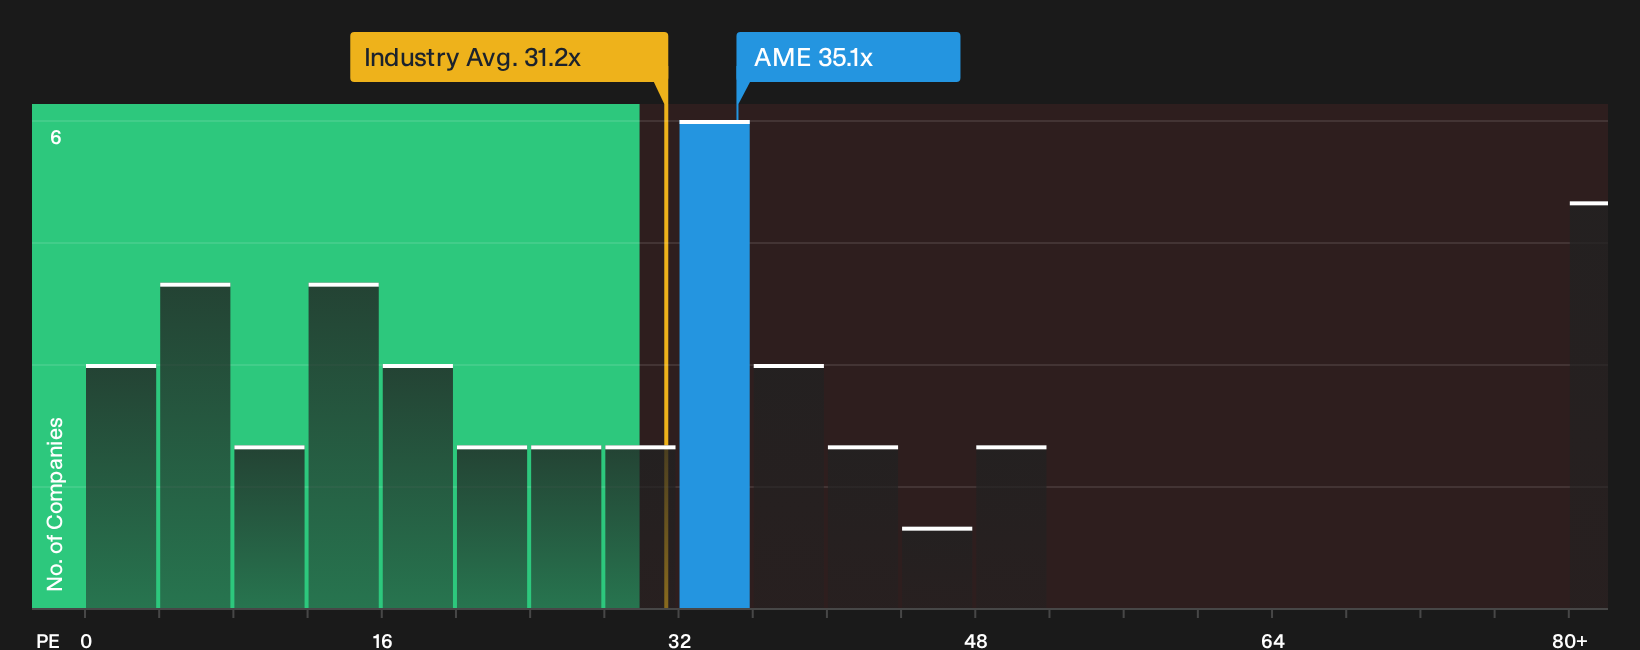
The P/E ratio works well for AMETEK because earnings are a key focus for both management and investors following its guidance. The stock trades on roughly 35.1x earnings, which is slightly below the peer group on 35.8x and above the wider Electrical industry on about 31.2x. That mix points to a premium over the broader sector, but not an especially stretched one relative to closer comparables.
On a more tailored yardstick that weighs AMETEK's growth profile, profitability, sector and risk into a single "fair" P/E range, the current multiple screens higher and therefore screens as overvalued. Because management has lifted 2026 EPS guidance, the market is effectively paying upfront for those higher profit targets, so any wobble in delivery would leave less room for error in this valuation. Investors weighing the set up can compare the current P/E, the peer group and that modelled fair range in more detail in the full multiples breakdown. Explore the numbers behind AMETEK's P/E valuation.
The AMETEK Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for AMETEK pick up where the valuation puzzle leaves off. They explain which assumptions about AMETEK's future growth, profit margins and earnings would need to occur for the share price to appear meaningfully higher or lower than it is today. Where a single ratio or valuation model gives one number, Narratives unpack the future that number relies on so you can monitor whether that story is actually unfolding on the Community page.
One of the top community narratives on AMETEK: 13% undervalued
"The main thing that has to go right is continued delivery on acquisitive growth and integration, including realizing planned cost synergies and cash EPS accretion..."
Discover why this Narrative puts AMETEK at 13% undervalued.
One more AMETEK check that belongs beside the price tag
Share price and earnings only tell part of the story for AMETEK, because the people steering the business and the way their pay is structured can strongly influence what happens next. See who runs AMETEK and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com