


Precinct Properties New Zealand Limited Precinct Properties Investments (NZSE:PCT) has scrapped its planned Downtown Car Park development in Auckland, instead rolling out a NZ$103 million capital return and wider capital management reset.
The share price reaction has been sharp. Precinct Properties New Zealand Limited Precinct Properties Investments has a 1-day share price return of 7.45% and a 7-day and 30-day share price return of 6.88%. However, the year-to-date share price return is down 15.48%, and the 1-year total shareholder return is down 13.23%, pointing to short-term momentum after a weaker period. The 3-year total shareholder return of 7.09% and 5-year total shareholder return decline of 16.70% indicate a mixed longer-term record.
Spot potential follow-through ideas from the Precinct Properties New Zealand Limited Precinct Properties Investments news by scanning a curated list of 199 high quality undervalued stocks with similar value characteristics.Bulls see Precinct Properties New Zealand Limited Precinct Properties Investments as a mispriced yield and asset play after the capital return, while bears see a value trap in weaker recent returns. The valuation work now shows which case has more support.
Preferred Price-to-Sales of 6.6x: Is it justified?
On the value side, Precinct Properties New Zealand Limited Precinct Properties Investments trades on a P/S ratio of 6.6x. Our work shows this as above a fair level of 4.9x, yet still below the 7.6x peer average and above the 4.5x global office REIT benchmark.
P/S compares the company’s market value to its NZ$281.7 million of revenue and is often used for property vehicles where earnings can swing with valuation movements. For Precinct Properties New Zealand Limited Precinct Properties Investments, this ratio needs to be read alongside forecast earnings, since the business is currently loss making with net income of NZ$8.2 million in the red.
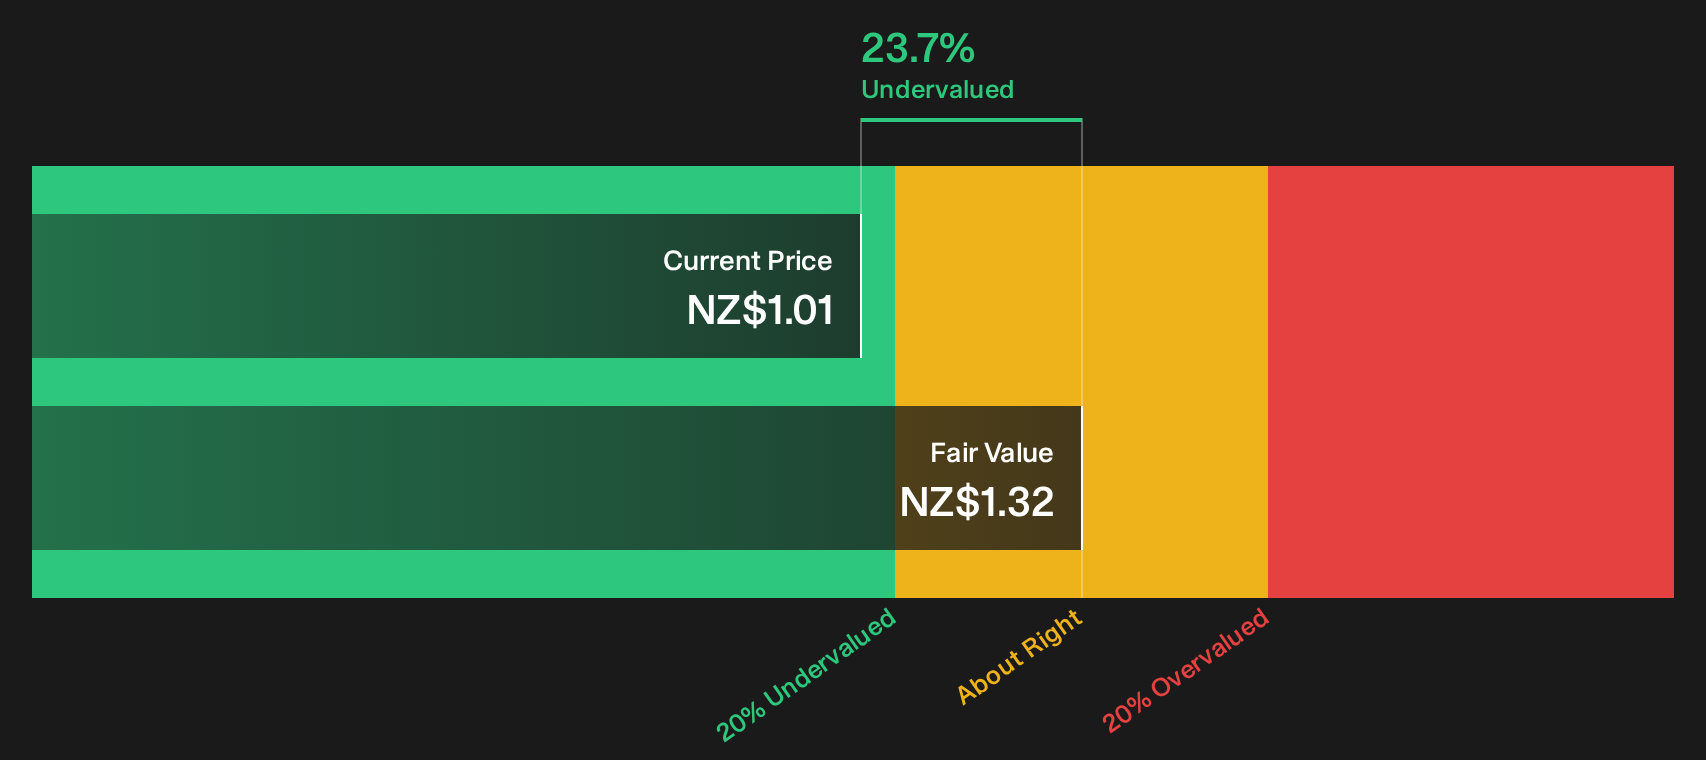
There is a tug of war in the data. The SWS DCF model flags the shares at NZ$1.01 as trading below an estimated future cash flow value of NZ$1.32. At the same time, the current 6.6x P/S sits above the 4.9x fair ratio level that the valuation work suggests the market could eventually move toward. Against that, the stock looks cheaper than peers on 7.6x P/S but richer than the wider global office REIT group on 4.5x. This points to investors paying up compared to international comparables.
Result: Price-to-sales of 6.6x (ABOUT RIGHT)
Still, the loss of NZ$8.2 million and the revenue decline of 14.2% raise questions about how resilient Precinct Properties New Zealand Limited Precinct Properties Investments really is.
Find out about the key risks to this Precinct Properties New Zealand Limited Precinct Properties Investments narrative.
Another View: SWS DCF flags Precinct Properties New Zealand Limited Precinct Properties Investments as undervalued
The earlier P/S work hinted at a full price. The SWS DCF model tells a different story. On that framework, Precinct Properties New Zealand Limited Precinct Properties Investments at NZ$1.01 screens at about 24% below an estimated cash flow value of NZ$1.32. Which signal do you weigh more heavily when the ratio looks rich but the cash flows suggest a discount?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Precinct Properties New Zealand Limited Precinct Properties Investments for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 199 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Precinct Properties New Zealand Limited Precinct Properties Investments so far. If this all feels finely balanced, act while the details are fresh and walk through the data yourself to stress test both sides of the story, then weigh the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Precinct Properties New Zealand Limited Precinct Properties Investments?
If Precinct Properties New Zealand Limited Precinct Properties Investments has sharpened your focus on value and risk, you can keep that momentum and widen your watchlist while the market is still offering mispricings.
- Chase quality at a discount by scanning the 199 high quality undervalued stocks and see which companies line up on both fundamentals and price.
- Prioritise resilience with the 218 resilient stocks with low risk scores so you can focus on businesses that score well on stability while others overlook them.
- Hunt for future leaders hiding in plain sight through the 603 high quality undiscovered gems before broader attention starts to narrow the opportunity set.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com