


Roper Technologies (ROP) just paired fresh third quarter numbers with new earnings guidance for late 2026, giving investors a concentrated look at how its software heavy portfolio is translating into profits.
Those results and the fresh guidance appear to have reset expectations around Roper Technologies. The 30 day share price return of 33.61% and 19.10% gain over 90 days point to momentum building again, even though the 3 year total shareholder return declined 5.10% and the 5 year total shareholder return is slightly negative at 0.37%.
Spot fresh momentum in Roper Technologies, and then scan for other software focused compounders showing similar earnings traction with the hand picked 29 high quality undervalued stocks.The share price now hovers around analyst targets, yet intrinsic value estimates still point to a discount. Is the market being appropriately cautious about Roper Technologies, or is it giving you an opening on valuation?
Most Popular Narrative: 2% Overvalued
Against a last close of $466.84, the most followed narrative pegs fair value for Roper Technologies at about $457.29, implying a small premium that hinges on how much weight you give to its software compounding story and acquisition machine.
The numbers imply that the current share price assumes Roper Technologies can sustain mid teens free cash flow per share compounding while effectively redeploying more than $5 billion into software M&A over time without eroding the quality of its vertical software and recurring revenue profile.
See why 43 investors see Roper Technologies as 2% overvalued.
Result: Fair Value of $457.29 (OVERVALUED)
Still, the Roper Technologies story can unwind if AI driven rivals undercut its niche platforms or if heavy software acquisitions fail to deliver planned returns.
Find out about the key risks to this Roper Technologies narrative.
Another View: What Roper Technologies’ P/E Is Signalling
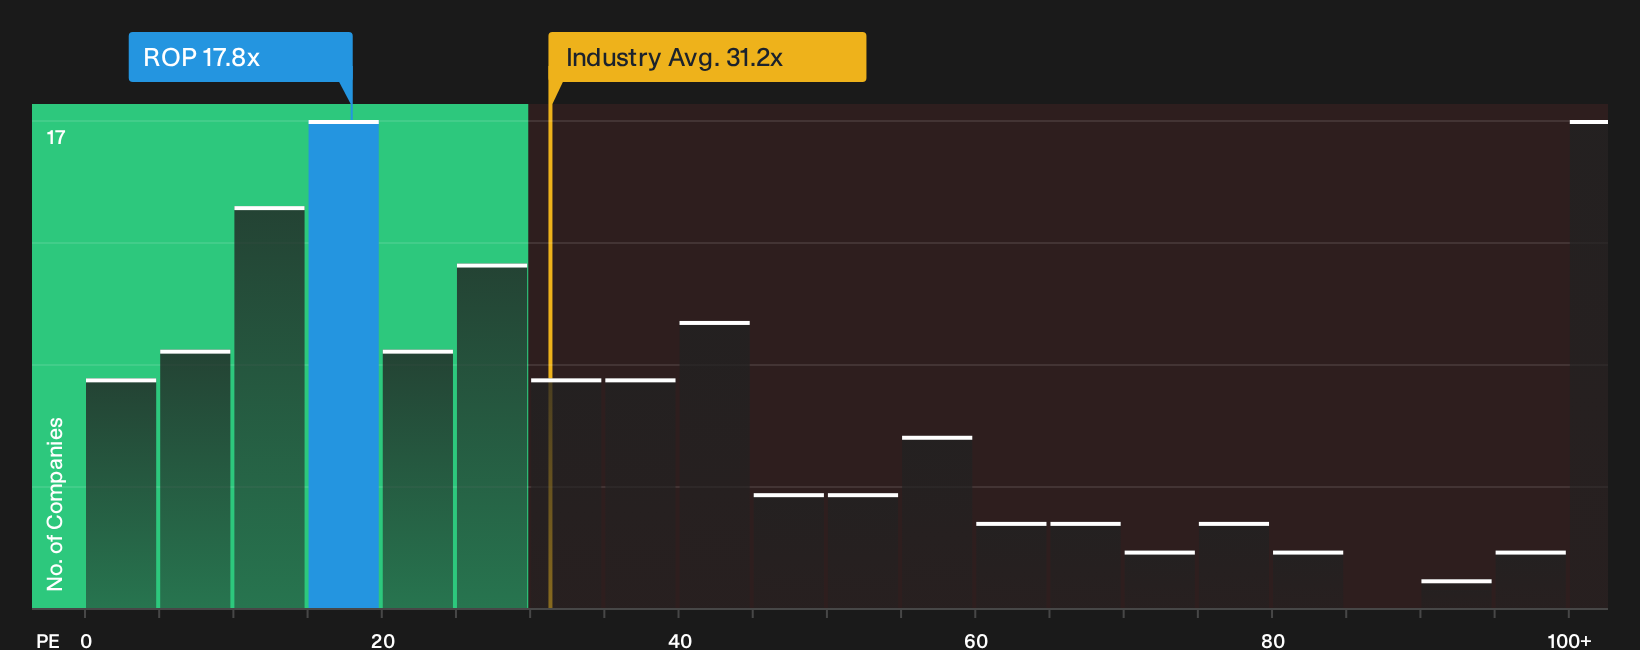
Where the narrative fair value casts Roper Technologies as slightly overvalued, the plain P/E math reads differently. The stock trades around 17.8x earnings, compared with 23.9x for peers and 31.2x for the broader US software group. The fair ratio sits at 20.9x.
That mix means the market is pricing Roper Technologies below both peers and the level our fair ratio suggests it could move toward, even as analysts forecast earnings to decline 7.7% a year for the next 3 years. Is that discount a cushion against those forecasts, or a signal that the market is already bracing for more disappointment than the models show?
To pressure test that gap between current P/E, peers and the fair ratio, and see what the numbers imply about valuation risk versus upside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment across Roper Technologies is mixed, with clear enthusiasm sitting right beside concern. Act while the data is fresh and weigh those trade offs for yourself, then pressure test that view by walking through the 3 key rewards and 3 important warning signs
Hunting For More Ideas Beyond Roper Technologies?
If Roper Technologies has sharpened your focus on quality and price, do not stop here. Broaden your watchlist now and keep your edge.
- Target resilient balance sheets by scanning our hand picked list of solid balance sheet and fundamentals (25 results) that combine financial strength with cleaner fundamentals.
- Spot potential mispricings early and review the curated 18 high quality undiscovered gems before the crowd pays attention.
- Prioritise smoother rides and stress test your risk tolerance against companies highlighted in the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com