


Angelalign Technology (SEHK:6699) is under fresh scrutiny after the Paris Local Division of the Unified Patent Court ruled that its Torque Ridges aligner systems infringe an Align Technology patent, triggering injunctions and product recalls across multiple EU countries.
Angelalign Technology’s legal hit in Europe lands after a mixed run in the market, with the latest share price at HK$76.55 and a year-to-date share price return of 25.7%. The 1-year total shareholder return of 34.45% contrasts with a much weaker 5-year total shareholder return that declined 71.45%, which hints that recent momentum has improved from a low base. At the same time, the past month’s 10.36% share price pullback and 7-day share price return that fell 5.73% suggest investors are now reassessing risk as litigation headlines build.
Scan beyond Angelalign Technology and stress test your dental and medical holdings against our curated list of solid balance sheet and fundamentals (203 results), which includes companies with the financial cushion to absorb regulatory and legal shocks.
After a sharp rebound from deep losses and a fresh legal overhang from Europe, Angelalign Technology now sits at a crossroads. Does the current valuation still compensate you for this legal and operational risk?
Preferred P/E of 40.6x: Is it justified for Angelalign Technology?
On simple earnings multiples, Angelalign Technology trades on a P/E of 40.6x, which is a rich tag relative to much of the Hong Kong Medical Equipment sector.
The P/E ratio compares the current share price to earnings per share and gives you a quick sense of how much investors are paying for each unit of profit. For a specialist dental equipment and services business like Angelalign Technology, that valuation anchor matters because earnings are closely watched as a proxy for how well the aligner and clinic model is converting demand into bottom line results.
Recent numbers show earnings growth of 74% over the past year and revenue growth of 16.1% annually, with current net profit margins at 9.3% compared with 7.6% last year. Forecasts point to earnings increasing 31.1% per year and revenue rising 16.1% per year, which suggests the market is paying up for a stronger profit trajectory after a difficult 5 year stretch where earnings declined 10% per year.
Set against peers, that 40.6x P/E is more than double the Hong Kong Medical Equipment industry average of 18x and above the peer average of 19.1x. It is also comfortably higher than the estimated fair P/E of 18.6x, which is the level the market could move towards if sentiment cools on the current growth story.
Explore the SWS fair ratio for Angelalign Technology.
Result: Price-to-earnings of 40.6x (OVERVALUED)
Still, Angelalign Technology now faces the Unified Patent Court ruling and ongoing product recalls, which could weigh on earnings visibility and investor confidence if disruption widens.
Find out about the key risks to this Angelalign Technology narrative.
Another View: What Our DCF Model Says About Angelalign Technology
The high P/E ratio paints Angelalign Technology as expensive, yet the SWS DCF model tells a very different story. On estimated future cash flows, the stock trades at HK$76.55 compared with a DCF fair value of HK$134.32, which points to a 43% discount.
That gap suggests the current price reflects a lot of uncertainty around legal risk and earnings durability. It raises a simple question for you as an investor: Is the market being too harsh on Angelalign Technology, or is the model too optimistic about future cash generation?
Look into how the SWS DCF model arrives at its fair value.
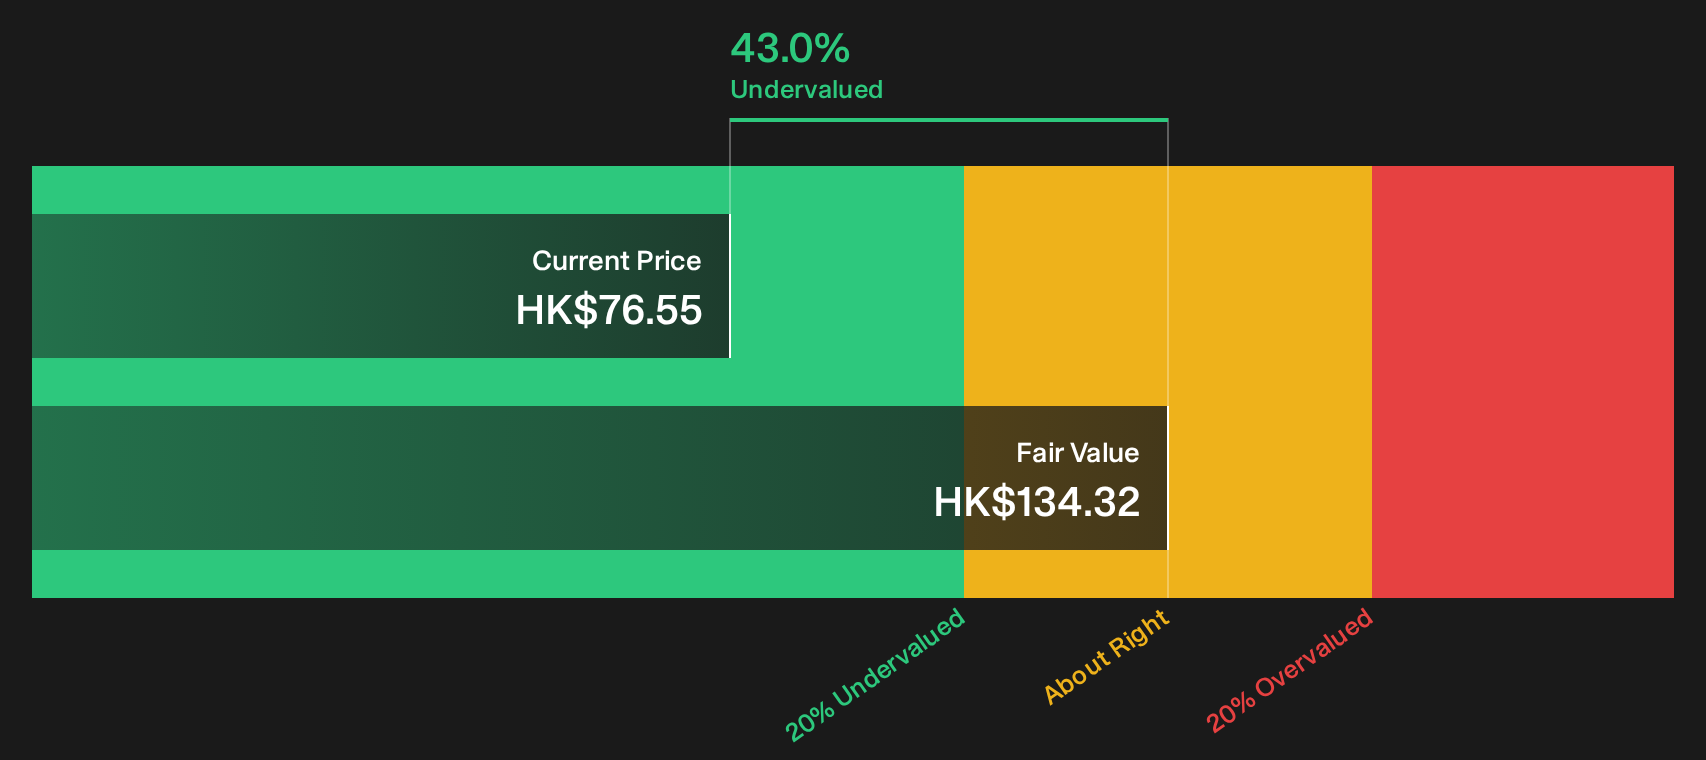
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Angelalign Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 199 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Angelalign Technology is split, which is exactly when it helps to move fast and test the data yourself before views harden. To weigh the upside against the legal and operational questions, start with the 4 key rewards and 2 important warning signs.
Looking for more Angelalign Technology investment ideas?
Do not stop your research with Angelalign Technology. Broaden your watchlist with focused stock ideas that fit different goals, risk levels, and income needs using the Simply Wall St Screener.
- Target potential mispricing by scanning for quality companies trading at attractive valuations through the 199 high quality undervalued stocks.
- Build a steadier portfolio by focusing on payout strength and income resilience with the 221 dividend fortresses.
- Dial down portfolio stress by concentrating on financially sturdy businesses using the 218 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com