


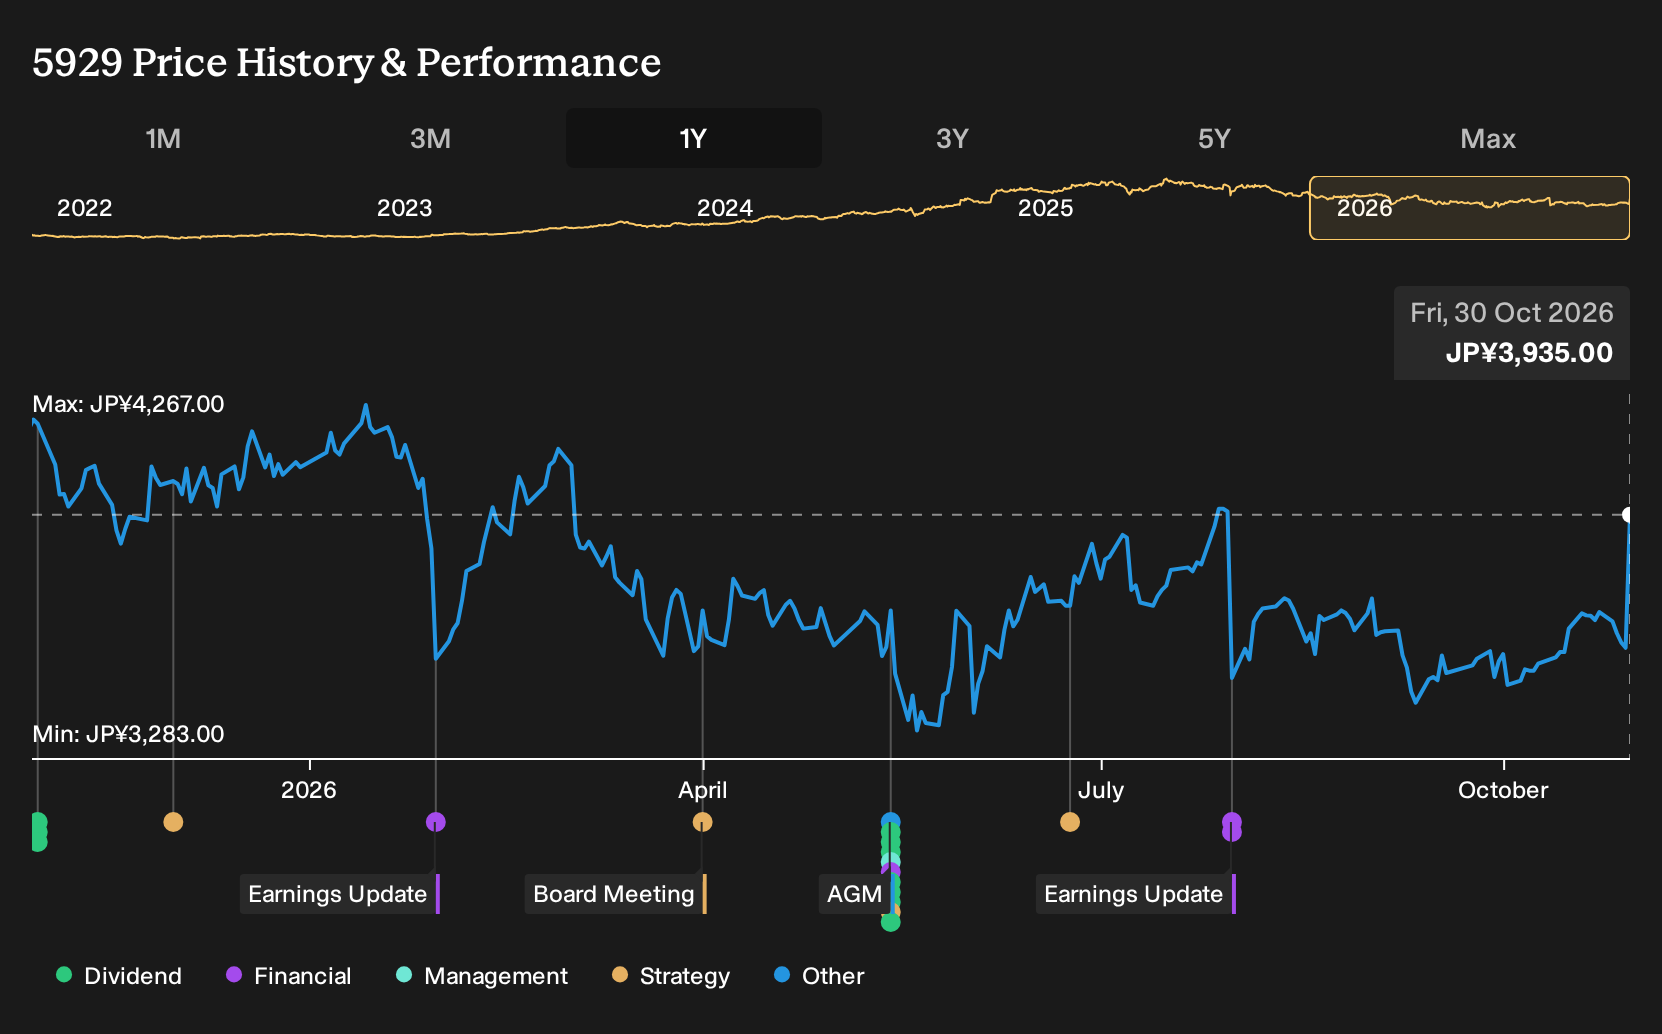
- Sanwa Holdings held a board meeting on 30 October 2026 to consider publishing a supplementary version of its Sanwa Global Vision 2030 Medium-term Management Plan 2027, updating investors on how management intends to steer the business toward its longer term goals.
- The updated plan signals that Sanwa Holdings is reassessing operational priorities and capital allocation, which can reshape expectations around growth initiatives, profitability focus, and overall execution risk across its core businesses.
- We now examine how Sanwa Holdings’ investment narrative could shift as management revisits its medium term roadmap through the 2030 vision update.
Compare how Sanwa Holdings is repositioning itself with a curated group of peers by scanning the 71 high quality undiscovered gems that may also be quietly resetting their long term plans.
What Is Sanwa Holdings' Investment Narrative?
Sanwa Holdings appeals to shareholders who want an industrial business tied to real assets, with products embedded in everyday infrastructure across Japan, North America, Europe and Asia. The appeal rests on steady demand for shutters, doors and related services, moderate forecast earnings and revenue growth of around 3% a year, and a dividend yield of 3.35%. The recent board meeting around the Sanwa Global Vision 2030 Supplementary Plan matters mainly if it reshuffles spending between growth projects, maintenance capital and shareholder returns.
In the short term, the key swing factors are execution on installation and maintenance work, pricing power in construction end markets and how capital intensive expansion becomes. The stock has been volatile over the past three months and has lagged both the broader Japanese market and building peers over one year, even with a P/E of 14.2x and some valuation support. Any shift in capital allocation or regional priorities flagged in the updated plan could either calm or amplify that volatility.
That said, there is a less visible pressure point in Sanwa Holdings’ funding mix that could matter more than the headline valuation story...
There's only one way to know the right time to buy, sell or hold Sanwa Holdings. Head to Simply Wall St's company report for the latest analysis of Sanwa Holdings's Fair Value.
Exploring Other Perspectives
Retail views on Sanwa Holdings in the Simply Wall St Community cover a wide span, from around ¥4,271 to roughly ¥8,821 per share across three separate fair value estimates. Those opinions were formed before the 30 October 2026 board meeting. Treat the new medium term plan as fresh information that could shift how you weigh these contrasting viewpoints.
Explore 2 other Sanwa Holdings fair value estimates, including one that suggests as much as 124% upside from the current price!
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so trust your own judgment.
- A great starting point for your Sanwa Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sanwa Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Sanwa Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Sanwa Holdings?
If the Sanwa Holdings story has sharpened your view on what you want from a business, you can use that clarity to look for other opportunities that better match your risk tolerance, income needs or valuation discipline.
- If you want resilient balance sheets and cleaner fundamentals, start by scanning a list of solid balance sheet and fundamentals (22 results) that meets tighter financial quality filters.
- For investors who care most about income, focus on companies that offer steadier cash returns to shareholders by reviewing a curated group of 27 dividend fortresses.
- If your priority is limiting downside, concentrate on capital preservation first and review a targeted universe of 24 resilient stocks with low risk scores that pass tougher risk screens.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com